

Venture Global's +32% dates to Hormuz, not a bear-band exit
Prompt v1.0
VG's gap-free +31.6% month is real, but the "early leg out of a downtrend" thesis fails — six of seven US LNG names have been in bull bands continuously since April. The move dates almost exactly to JKM's +32.6% spike after the 7 July strike on a Qatari carrier, and VG now sits only 8-10% below consensus targets.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
VG | Venture Global | LNG Liquefaction | 🟢 Cont. Bull | +17.0% | −16.3% |
LNG | Cheniere Energy | LNG Liquefaction | 🟢 Cont. Bull | +6.0% | +10.9% |
NEXT | Nextdecade | International E&P | 🟢 Cont. Bull | −13.9% | −44.5% |
EE | Excelerate Energy | Floating LNG Infrastructure | 🟢 Cont. Bull | +0.6% | +52.2% |
GLNG | Golar LNG | Floating LNG Infrastructure | 🟢 Cont. Bull | −4.6% | +17.8% |
FLNG | FLEX LNG | Liquefied Gas Carriers | 🟢 Cont. Bull | +6.8% | +33.2% |
NFE | New Fortress Energy | Oil & Gas Midstream | 🔴 Cont. Bear | −4.3% | −90.4% |
CQP | Cheniere Energy Partners | LNG Liquefaction | 🟢 Cont. Bull | +4.0% | +14.3% |
BKR | Baker Hughes | Integrated Oilfield Services | 🟢 Cont. Bull | +4.3% | +30.1% |
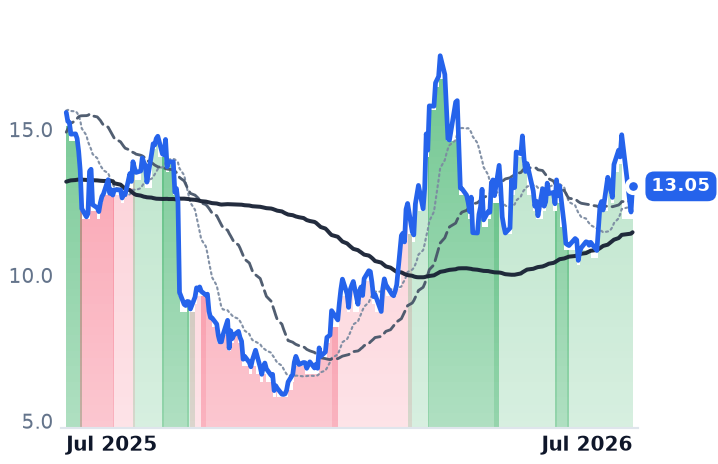
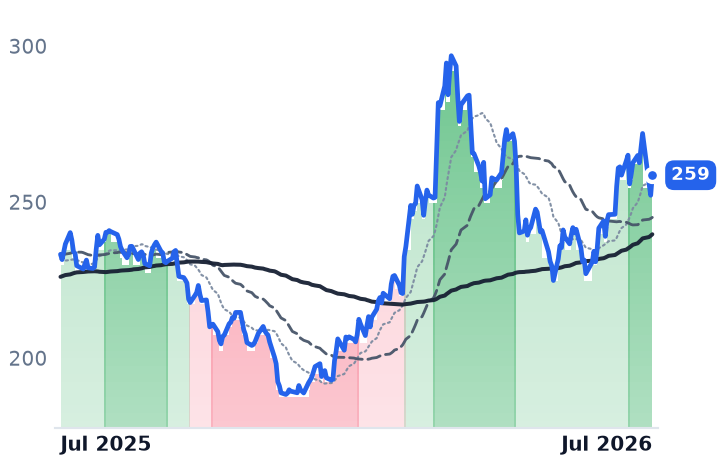
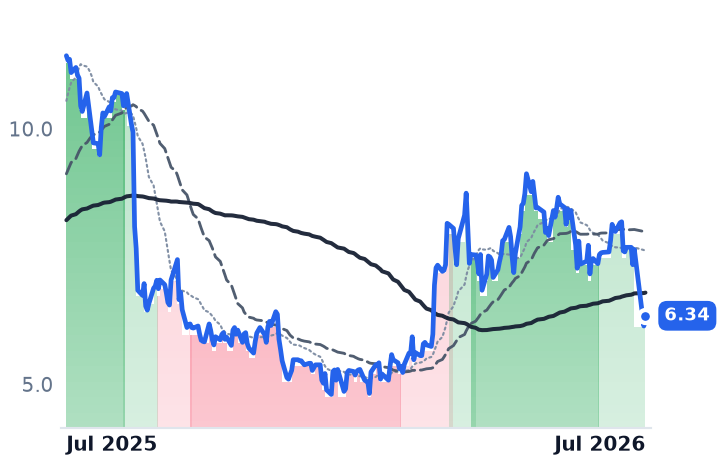
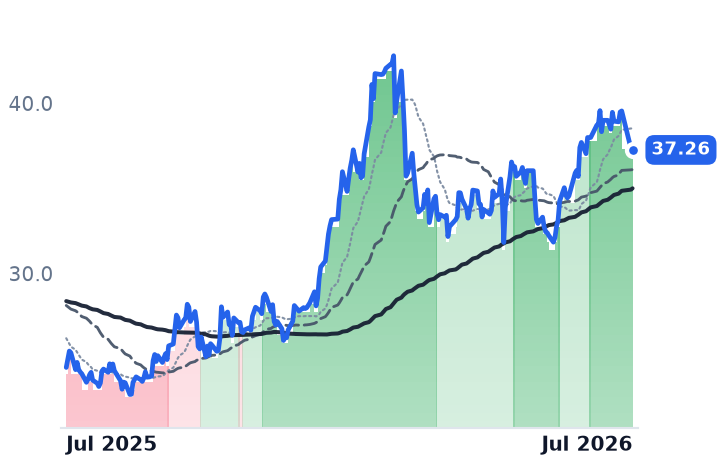
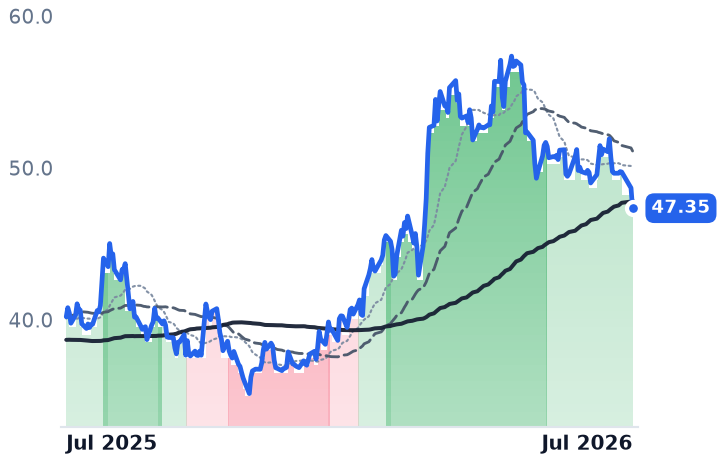
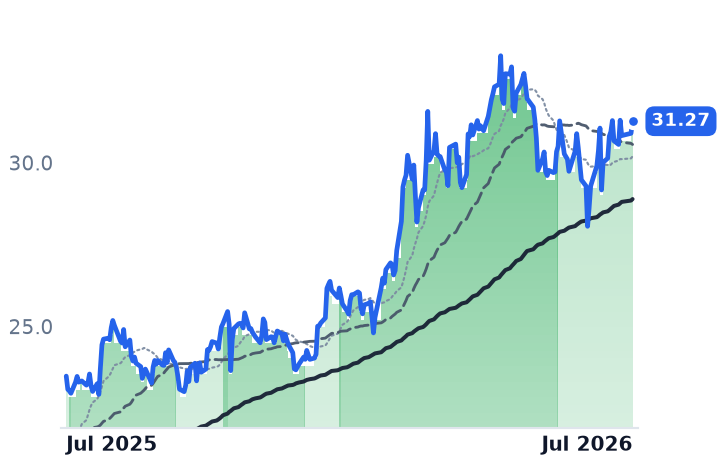
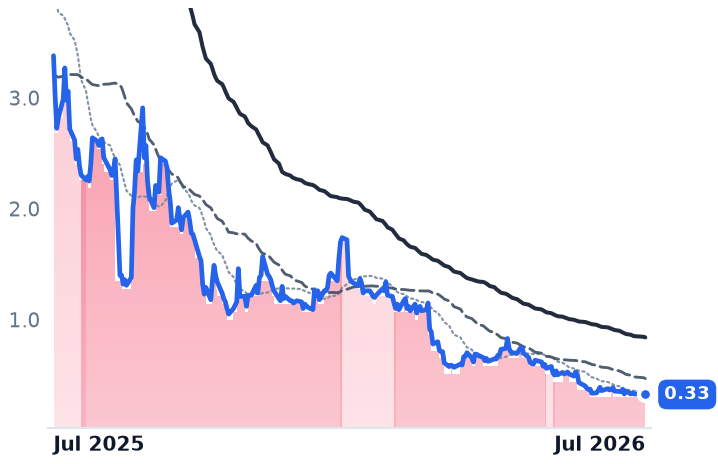
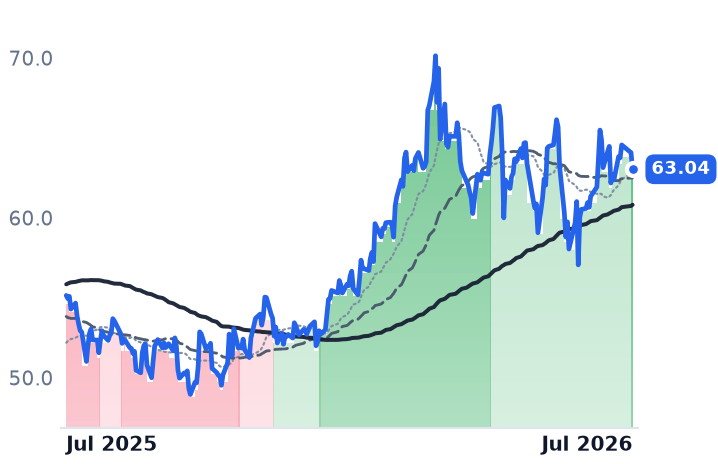
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VG | $37.8B | 11.4x | 9.2x | 2.2x | 2.0x | 4.7x | 4.3x | 10.6x | -24.9% |
LNG | $58.2B | 20.6x | 50.5x | 2.6x | 2.5x | 4.9x | 4.8x | 10.2x | 12.1% |
NEXT | $1.9B | n/m | — | n/m | 6.1x | — | — | n/m | -201.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EE | $4.6B | 26.6x | 24.7x | 3.1x | 3.0x | 8.4x | 8.2x | 11.6x | 0.8% |
GLNG | $5.3B | 32.5x | 47.0x | 10.1x | 12.7x | 18.4x | 23.1x | 20.2x | -5.2% |
FLNG | $1.6B | 15.6x | 12.8x | 4.4x | 4.4x | 8.6x | 8.5x | 11.5x | 9.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NFE | $79.7M | n/m | — | 0.1x | 0.0x | 1.7x | 0.7x | n/m | -702.1% |
CQP | $33.3B | 11.5x | 14.7x | 2.9x | 2.8x | 7.8x | 7.6x | 11.2x | 9.8% |
BKR | $62.0B | 19.9x | 23.7x | 2.2x | 2.2x | 9.5x | 9.4x | 13.2x | 5.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
VG | Revenue | +36.1% | −13.8% | +27.3% |
| EPS | +104.3% | −52.2% | +65.3% | |
LNG | Revenue | +15.4% | +2.1% | +3.8% |
| EPS | −65.4% | +214.6% | −8.0% | |
NEXT | Revenue | — | +267.6% | +129.4% |
| EPS | +25.3% | −62.3% | −17.3% | |
EE | Revenue | +27.8% | +27.9% | +21.4% |
| EPS | +16.4% | +28.8% | +23.2% | |
GLNG | Revenue | +4.5% | −3.1% | +106.0% |
| EPS | −20.3% | −55.3% | +733.7% | |
FLNG | Revenue | +8.7% | −2.8% | +2.2% |
| EPS | +29.1% | −9.8% | +13.4% | |
NFE | Revenue | +89.1% | +3.5% | −36.7% |
| EPS | −72.6% | −104.2% | −180.0% | |
CQP | Revenue | +10.8% | −1.0% | +3.5% |
| EPS | +13.7% | −6.9% | +1.6% | |
BKR | Revenue | +2.3% | +10.9% | +7.5% |
| EPS | +6.7% | +14.6% | +20.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The move is real; the framing isn't
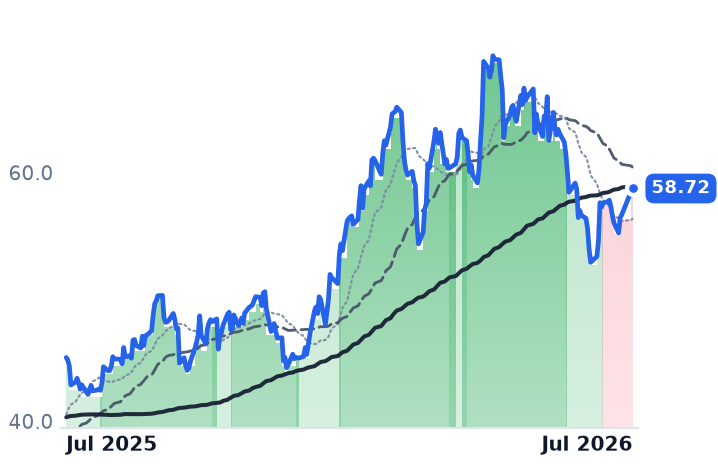
VG closed at $14.82 on 22 July, up 31.6% in 30 days, 20.1% in 90 and 55.5% in 180. It was a grind, not a pop: a 20-session stair-step off a $10.51 low on 24 June, largest single day +9.2% on 13 July, no overnight gap wider than ~4.7%, with volume expanding from ~6.7M shares in early July to 21.7M, 23.6M and 20.9M in the 17-22 July window.
The cohort test fails, though. None of the seven names exited a bear band in the trailing 90 days. VG, LNG, EE, GLNG, FLNG and NEXT have all been in mild or strong bull bands continuously since at least 1 April, and all six trade above their 200-day averages — VG +38.9%, EE +20.1%, NEXT +15.6%, LNG +10.2%, FLNG and GLNG +9.4%. Only NFE is in strongly bearish, 67.6% below its 200-day. Cheniere did not fall over the window either: LNG rose 15.8% to $267.40 before easing to $255.88 on 27 July.
What actually dated it
The arbitrage leg confirms precisely. JKM reached $21.03/MMBtu on 20 July, up 32.57% in a month — near-identical to VG's +31.6% — while Henry Hub slid to a three-month low near $2.72-2.80, after a $2.94 prompt-month settlement on 10 July on strong production and ample storage. That is a roughly $18 gross spread.
The trigger was geopolitical, not feedgas. On 7 July the Qatari carrier Al Rekayyat was struck near Limah, Oman, after which QatarEnergy paused its Ras Laffan ramp-up. JKM jumped from the mid-$16s to the mid-$18s that week and TTF from $14.8 to $16.8, with EU storage just 51.5% full on 10 July — 22.9 points below the five-year average. EIA still forecasts 9% US LNG export growth in 2026, but that is structural, not the July catalyst.
Company news layered on: a binding EnBW 820kt/yr five-year SPA, Mizuho's target lift to $15 at Neutral, and a Baker Hughes order for six CP2 liquefaction blocks following March's CP2 Phase 2 FID and $8.6B financing.
What's left
Runway is thin. Consensus on VG sits near $16.06-16.32, 8-10% above the close, versus ~18% for Cheniere against a ~$302 average. VG is the cheaper trailing multiple (P/E 11.4 vs 40.8) on $8.2-8.5B FY26 EBITDA guidance and a $3.82/MMBtu implied Q1 liquefaction fee. Offsetting: an October 2025 BP arbitration loss exposing over $1B, 225 MTPA under construction globally, and a US-EU $750B energy purchase target analysts call unrealistic. Next checkpoint: Q2 results on 11 August.