

800VDC Power-Semis Basket Sinks on Macro Reset, Not Broken Fundamentals
Hypothesis Opus 5 · Research Sonnet 5 · Writing Sonnet 5 · Prompt v1.0
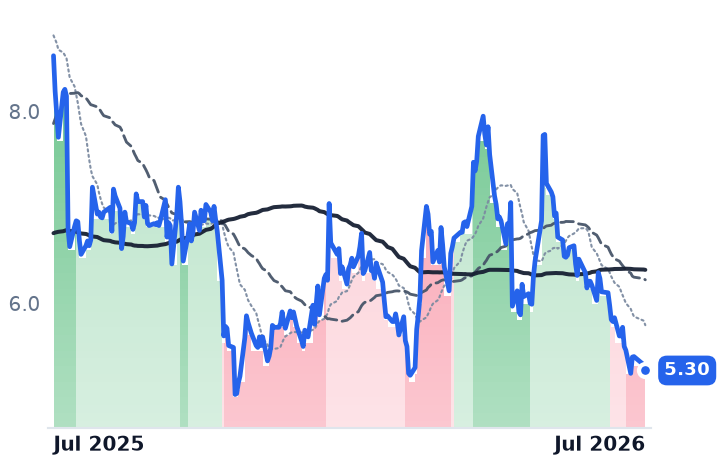
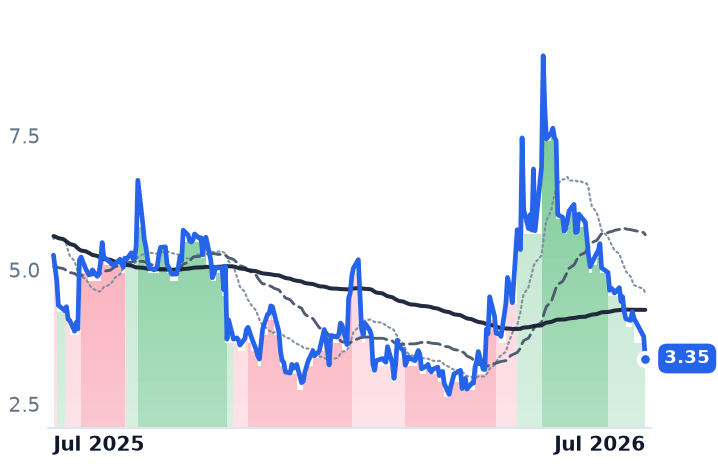
The AI2 800VDC power-semis/magnetics basket (NVTS, VICR, BELFB, BELFA, ULBI, IPWR) is down sharply over 30 days, but trend-band data shows only ULBI has actually rolled into a bear signal — the rest merely eased off strong-bull. The decline tracks a broad AI-chip valuation selloff and one company-specific patent suit, not a backlog or bookings break; both Vicor and Navitas beat and raised guidance in July.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
NVTS | Navitas Semiconductor | Other | 🟢 Cont. Bull | −45.1% | +29.5% |
VICR | Vicor | Other | 🟢 Cont. Bull | −50.2% | +299.7% |
BELFB | Bel Fuse | Connectors & Interconnect Systems | 🟢 Cont. Bull | −23.2% | +86.0% |
BELFA | Bel Fuse | Hardware, Equipment & Parts | 🟢 Cont. Bull | −25.7% | +75.0% |
ULBI | Ultralife | Electrical Equipment & Parts | 🔴 Cont. Bear | −12.1% | −38.2% |
IPWR | Ideal Power | Semiconductors | 🌱 Emerging Bull | −36.9% | −36.5% |
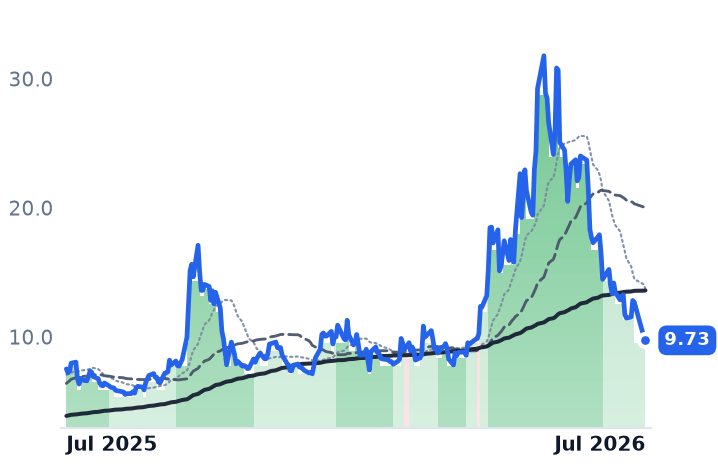
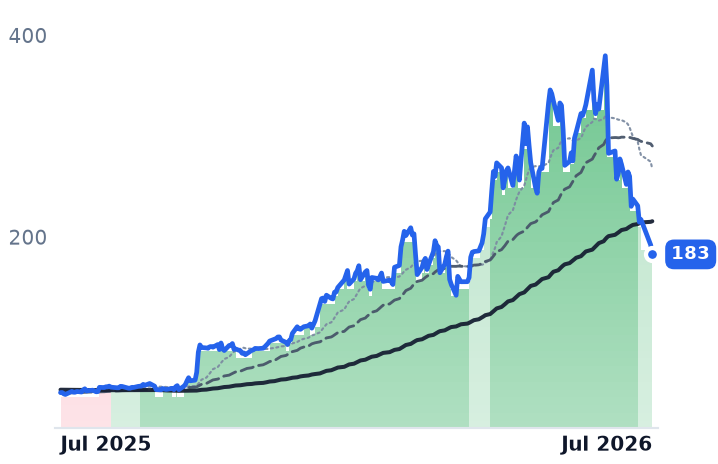
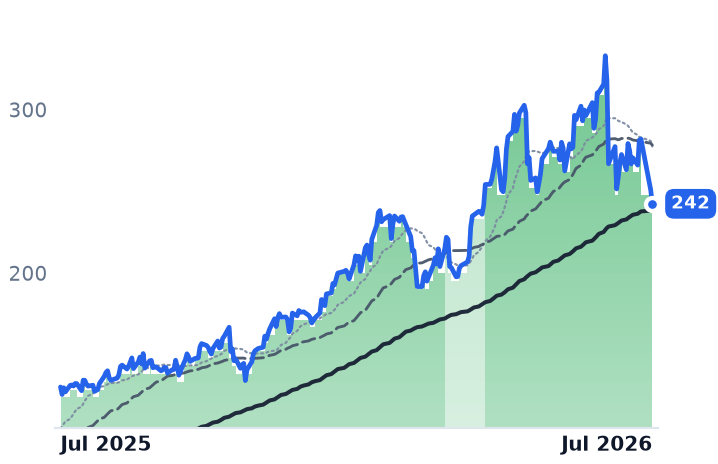
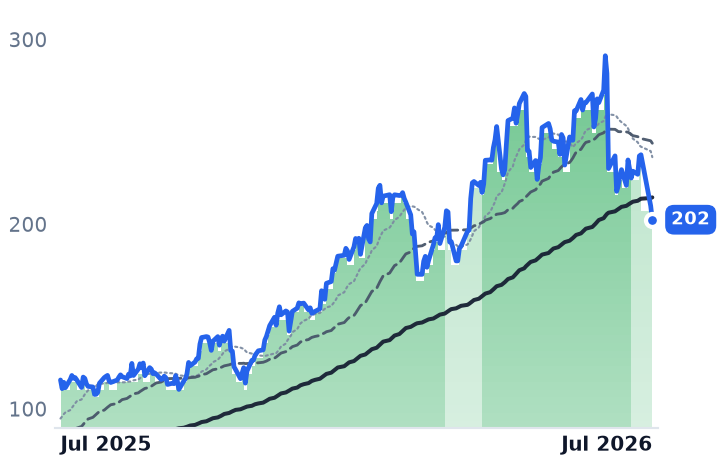
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NVTS | $3.8B | n/m | — | 104.3x | 81.1x | — | — | n/m | -1.8% |
VICR | $11.5B | 79.7x | 74.0x | 24.3x | 19.1x | 42.9x | 33.7x | 86.8x | 0.4% |
BELFB | $3.6B | 75.0x | 31.5x | 4.9x | 4.5x | 12.4x | 11.3x | 25.9x | 2.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BELFA | $3.7B | 75.0x | 26.6x | 4.9x | 4.6x | 12.4x | 11.5x | 25.9x | 2.0% |
ULBI | $122.1M | n/m | 8.5x | 0.7x | 0.5x | 2.7x | 2.3x | n/m | 1.7% |
IPWR | $86.2M | n/m | — | — | 107.8x | — | — | n/m | -11.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NVTS | Revenue | +3.3% | +57.9% | +66.9% |
| EPS | −26.5% | −10.2% | −51.3% | |
VICR | Revenue | +33.1% | +55.6% | +22.2% |
| EPS | +58.9% | +73.2% | +33.0% | |
BELFB | Revenue | +20.5% | +8.0% | +13.3% |
| EPS | +41.6% | +13.7% | +30.4% | |
BELFA | Revenue | +20.3% | +7.6% | +12.6% |
| EPS | +39.7% | +13.2% | +34.5% | |
ULBI | Revenue | +6.2% | — | — |
| EPS | +22.9% | — | — | |
IPWR | Revenue | +1500.0% | +275.0% | +186.7% |
| EPS | −21.8% | −17.5% | −11.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The band data doesn't match the price data
Six members of this bucket fell 11%-48% over the past 30 days, but the trend-band signal tells a more selective story: only ULBI — a battery/military-comms name with the weakest read-through to 800VDC rack power anyway — has actually rolled from bull into a strongly bearish band. NVTS, VICR, BELFA and IPWR softened from strongly bullish to mildly bullish, and BELFB never left strongly bullish at all. Notably, the two biggest decliners by price, VICR (-47.6% over 30 days) and NVTS (-43.6%), held bullish bands longer than smaller-cap peers, meaning the drawdown's magnitude and its band-break timing don't line up cleanly with either the "cohort rollover" or "speculative pair drags cohort" framing in isolation.
A sector-wide reset, not a fundamentals break
The proximate catalyst is macro: a broad AI-chip valuation selloff began around July 2, with Micron falling roughly 13% and erasing about $138B of market value in a single session, alongside declines in Intel, AMD, and the SMH semiconductor ETF amid AI-capex-ROI skepticism and a hawkish Fed. That pressure extended into the worst two-day sector selloff in a month by mid-July, consistent with a sustained multi-session bleed rather than a single shock. Vicor itself dropped over multiple distinct sessions in July, including its own post-earnings session.
The fundamentals didn't confirm the price action
Vicor's Q2 print, released July 21, was a genuine beat: revenue of $143.4M, up 26.9% sequentially, with a record one-year backlog up 26% to $379.7M and a raised full-year revenue outlook above $600M. Shares still slipped on the print, and an earlier patent judgment against Vicor was already resolved in March, well before the July slide — pointing to multiple compression on a richly valued stock, not a bookings problem.
Navitas similarly beat on revenue ($10.53M, +22% QoQ) and guided Q3 to accelerate to +28% QoQ growth, but a large non-GAAP EPS miss driven mostly by a non-cash earnout remeasurement charge and a July 7 Wolfspeed patent suit seeking a US sales ban across its entire GaN/SiC lineup have overshadowed otherwise constructive guidance.
Bel Fuse's Q2 print was not yet reported as of this pullback, and its own pre-announced guidance range cited strength across multiple segments — no fresh negative data point there, though a segment realignment away from a standalone Power Solutions line may reduce future visibility into AI-specific magnetics mix.
Meanwhile, NVIDIA's full Kyber rack architecture remains slated for H2 2027 — a timeline that was already known before this selloff, not a newly revealed slip.