

Asia's substrate and MLCC cohort de-rates on record fundamentals
Prompt v1.0
Six Asian substrate and passive-component names all topped inside a four-week window in late May–June and have since fallen 11% to 60% from peak — but every fundamental leg (MLCC book-to-bill, pricing, FC-BGA utilisation, forward estimates) is still improving. This is a multiple unwind driven by Korea/Asia chip flows, and the local trend-band file has not caught up to it.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
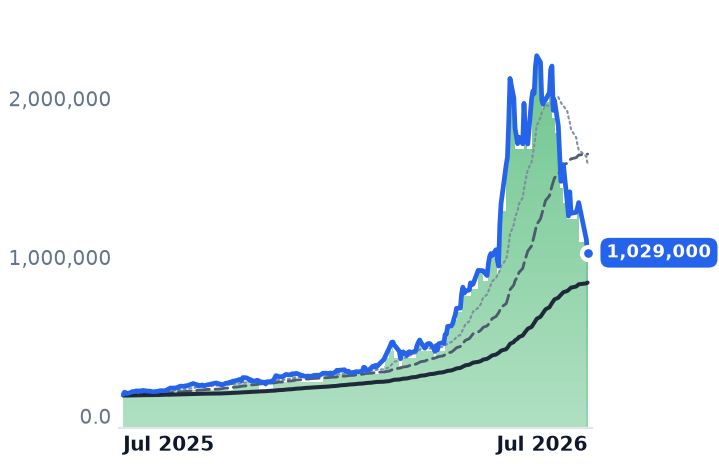
009150.KS | Samsung Electro-Mechanics | Hardware, Equipment & Parts | 🟢 Cont. Bull | −49.5% | +655.8% |
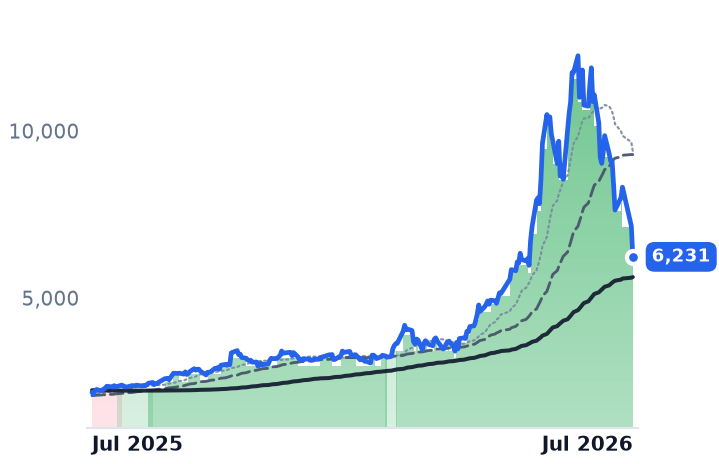
6981.T | Murata Manufacturing | Hardware, Equipment & Parts | 🟢 Cont. Bull | −42.0% | +185.7% |
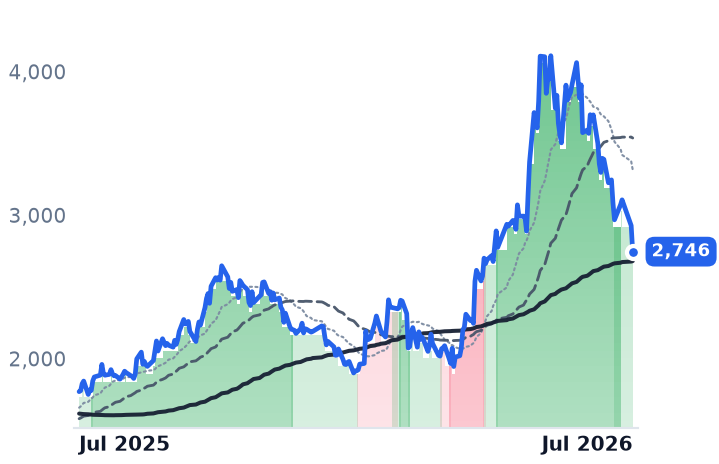
6762.T | TDK | Hardware, Equipment & Parts | 🟢 Cont. Bull | −23.6% | +55.1% |
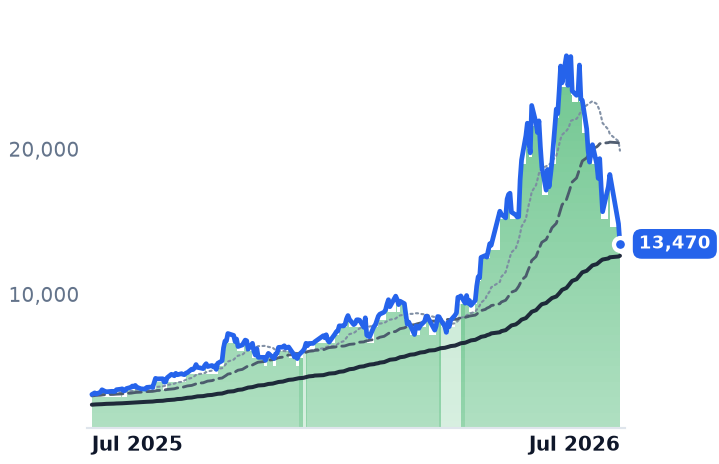
4062.T | Ibiden Co.,Ltd | Hardware, Equipment & Parts | 🟢 Cont. Bull | −43.2% | +334.3% |
3037.TW | Unimicron Technology | Hardware, Equipment & Parts | 🟢 Cont. Bull | −29.4% | +391.4% |
3189.TW | Kinsus Interconnect Technology | Semiconductors | 🟢 Cont. Bull | −28.8% | +443.4% |
005930.KS | Samsung Electronics | Consumer Electronics | 🟢 Cont. Bull | −35.4% | +198.7% |
000660.KS | SK hynix | Semiconductors | 🟢 Cont. Bull | −46.7% | +435.9% |
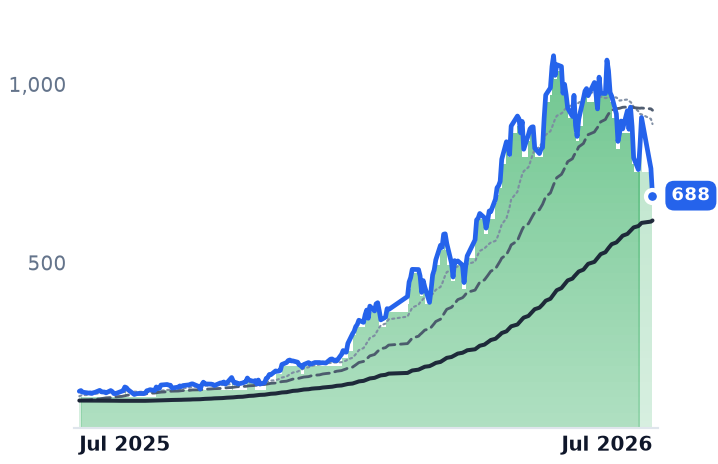
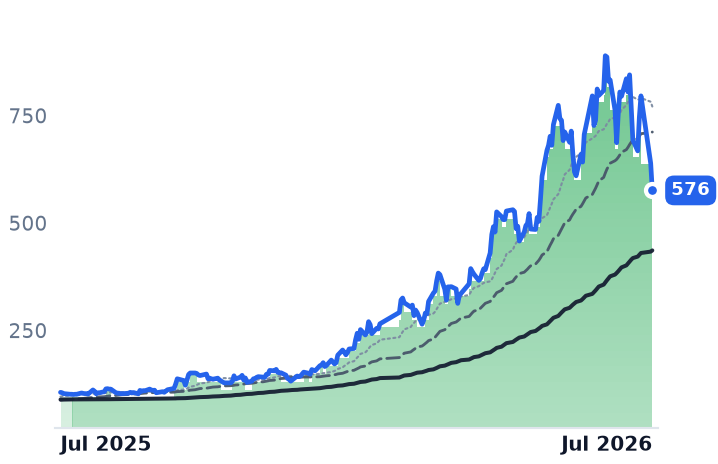
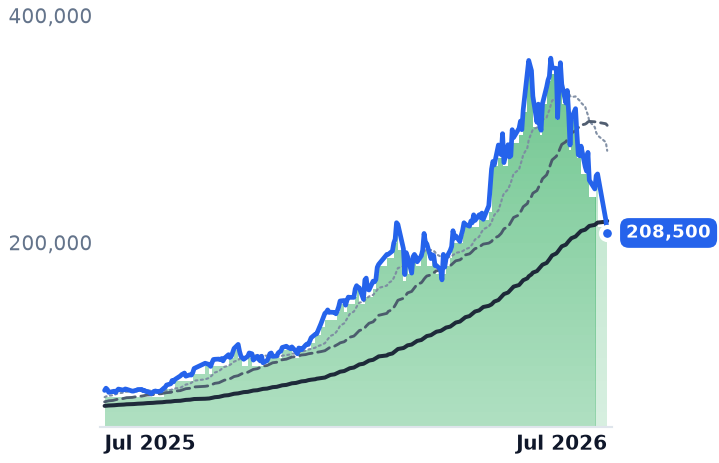
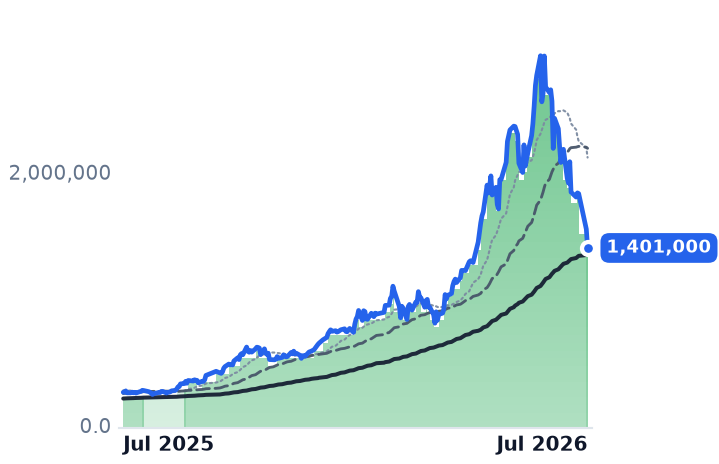
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
009150.KS | $100.8T | 104.9x | 68.5x | 8.1x | 7.1x | 40.0x | 34.9x | 46.4x | 0.4% |
6981.T | $10.2T | 43.6x | 33.3x | 5.6x | 5.2x | 13.2x | 12.3x | 20.1x | 1.8% |
6762.T | $5.6T | 28.6x | 25.4x | 2.2x | 2.1x | 7.1x | 6.9x | 11.0x | 3.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
4062.T | $5.5T | 79.9x | 72.6x | 12.5x | 10.4x | 40.0x | 33.4x | 30.7x | 1.7% |
3037.TW | $1.8T | 73.0x | 57.6x | 12.0x | 9.6x | 65.3x | 52.3x | 47.2x | -0.3% |
3189.TW | $447.4B | 144.9x | 79.8x | 10.0x | 8.3x | 45.0x | 37.4x | 35.7x | 0.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
005930.KS | $1800.1T | 22.0x | 7.0x | 4.6x | 2.8x | 17.8x | 10.8x | 13.9x | 2.0% |
000660.KS | $1135.3T | 15.5x | 6.1x | 8.6x | 3.6x | 12.6x | 5.3x | 11.8x | 3.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
009150.KS | Revenue | +26.8% | +32.3% | +30.0% |
| EPS | +127.8% | +107.2% | +54.8% | |
6981.T | Revenue | +4.4% | +8.2% | +12.1% |
| EPS | −8.8% | +40.5% | +27.5% | |
6762.T | Revenue | +13.1% | +5.3% | +6.2% |
| EPS | +16.5% | +12.3% | +13.7% | |
4062.T | Revenue | +13.2% | +26.7% | +26.1% |
| EPS | +45.1% | +81.7% | +54.8% | |
3037.TW | Revenue | +41.6% | +48.7% | +34.8% |
| EPS | +453.6% | +93.3% | +69.4% | |
3189.TW | Revenue | +37.0% | +45.9% | +51.2% |
| EPS | +230.3% | +136.2% | +110.5% | |
005930.KS | Revenue | +93.0% | +19.5% | +7.5% |
| EPS | +521.0% | +25.1% | +5.2% | |
000660.KS | Revenue | +225.0% | +34.1% | +9.7% |
| EPS | +373.8% | +29.8% | +6.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
A synchronized top, then a synchronized break
The cohort topped almost together: Unimicron on 27 May at NT$1,080, TDK 5 June at ¥4,111, Samsung Electro-Mechanics 19 June at ₩2,270,000, Ibiden and Murata both 22 June at ¥26,425 and ¥12,250, and Kinsus 30 June at NT$891. Every one has fallen since. Through the 22 July price cutoff the 30-day moves were 009150.KS -39.6%, Murata -32.1%, Ibiden -30.9%, TDK -23.5%, Unimicron -9.8% and Kinsus flat. Later FMP snapshots put drawdowns from peak at roughly -60%, -54%, -43%, -28% and -17% for SEMCO, Murata, Ibiden, TDK and Unimicron.
The Samsung Electro-Mechanics move is real, not a corporate-action artifact — OHLCV is continuous with normal 0.3–1.5m share volumes — but it is violent rather than gradual: -9.8% on 7 July, -10.2% on 8 July, -14.9% on 13 July, then +12.1% on 15 July. Of the eight names in the original cohort only six are analysable: Yageo has no local history, and Shinko is gone entirely after JIC Capital's ¥5,920/share tender offer completed in March 2025 and the shares were delisted.
The fundamentals went the other way
Every demand-side leg of a distribution thesis fails. Murata, SEMCO and Taiyo Yuden posted MLCC book-to-bill ratios of 1.30, 1.31 and 1.25 in late June, described as post-pandemic highs. Instead of Taiwanese price competition, Yageo launched its broadest capacitor price hike in years on 1 July, extending increases to direct customers for the first time this cycle. Industry-wide, high-end MLCC lead times stretched from 8 to over 20 weeks with capacity unlikely to catch up before late 2027 — though TrendForce frames it as AI strength against a weak consumer segment, not a uniform boom.
Substrates are equally tight: FCBGA demand exceeds capacity by more than 50%, with Ibiden's ¥500bn plan only reaching first output in fiscal 2027, while Unimicron, Kinsus and Nan Ya PCB run at full utilisation. SEMCO itself guided Q2 revenue of ₩3.3tn and operating profit of ₩398.3bn, above consensus. Consensus FY2026–27 revenue and EPS growth for the cohort is still accelerating.
What actually moved
The KOSPI peaked at 9,114.55 on 22 June — the same week the cohort topped — then collapsed 10.84% on 28 July to 6,023.66 after China's first domestic immersion DUV tools entered service at SMIC and CXMT, knocking Samsung and SK Hynix down ~13-14%. The sell-off spread across Seoul and Tokyo, matching the cohort's cross-market behaviour.
Two residual observations. Valuations remain demanding — Unimicron 127x trailing, Ibiden 106x, SEMCO 85x — and every name still sits 19% to 124% above its 200-day average. And the signal layer is badly stale: through 22 July the band file still showed SEMCO, Kinsus, Ibiden and Murata in unbroken strongly bullish despite 24-41% drawdowns.