

Stock-Photo Merger Collapse, Not Sector-Wide AI Rot, Drives Creative-SaaS Bucket Down
Hypothesis Opus 5 · Research Sonnet 5 · Writing Sonnet 5 · Prompt v1.0
The watchlist's Creative & Content bucket's -13.7% monthly drop is concentrated almost entirely in Shutterstock and Getty Images after their merger collapsed on July 7, triggering a genuine debt-refinancing crisis at Getty — while Adobe and Figma, the cohort's actual AI-monetization stories, look mislabeled by a shared bearish band.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
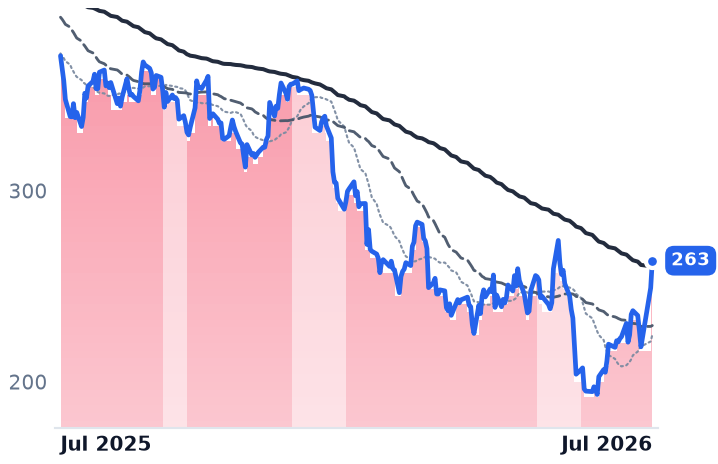
ADBE | Adobe | Design & Content Creation | 🔴 Cont. Bear | +27.6% | −28.9% |
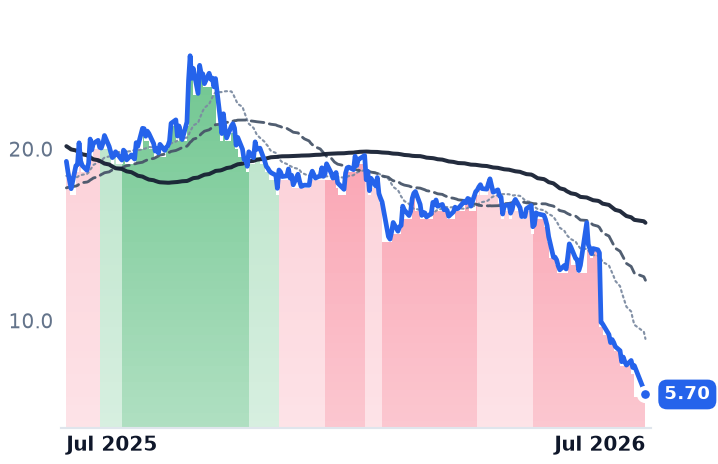
SSTK | Shutterstock | Media & Content Distribution | 🔴 Cont. Bear | −59.7% | −70.4% |
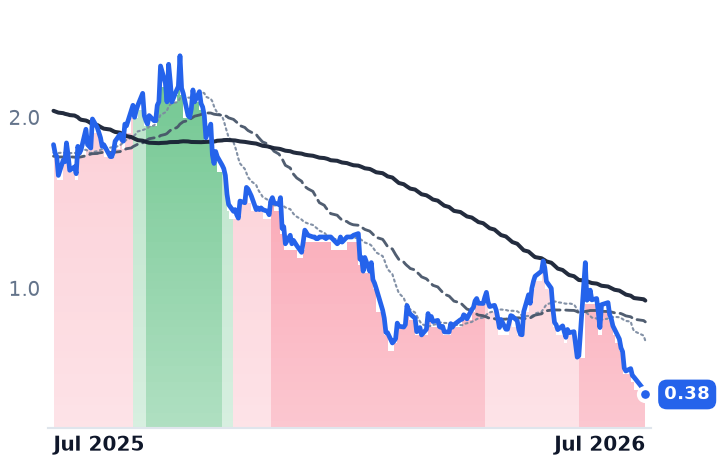
GETY | Getty Images | Internet Content & Information | 🔴 Cont. Bear | −59.7% | −79.4% |
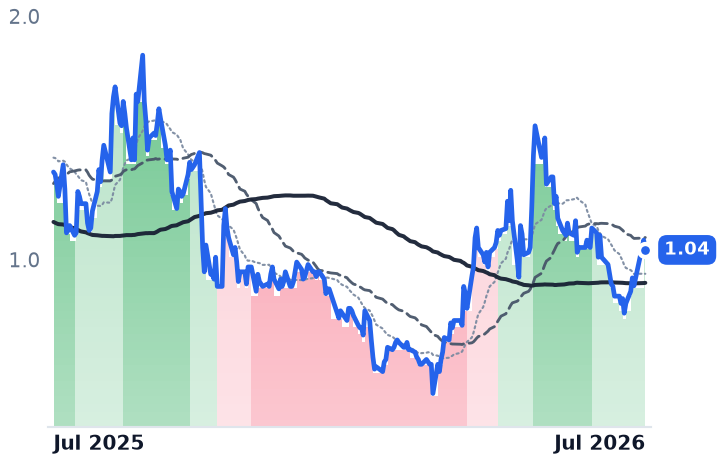
CHGG | Chegg | Education & Training Services | 🌱 Emerging Bull | −6.3% | −23.5% |
FIG | Figma | Design & Content Creation | 🔴 Cont. Bear | +29.8% | −78.6% |
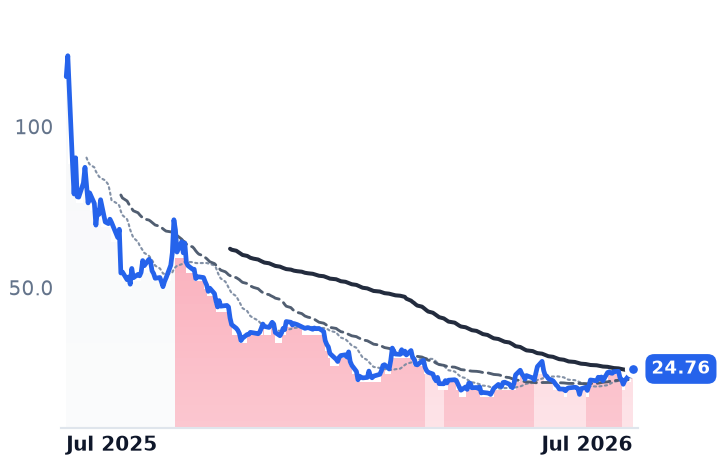
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ADBE | $101.0B | 14.5x | 10.4x | 4.0x | 3.8x | 4.5x | 4.3x | 10.4x | 10.5% |
SSTK | $198.8M | n/m | — | 0.2x | 0.3x | 0.4x | 0.4x | n/m | 44.7% |
GETY | $128.8M | n/m | 13.4x | 0.1x | 0.1x | 0.2x | 0.2x | 11.7x | -65.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CHGG | $88.2M | n/m | — | 0.3x | 0.4x | 0.6x | 0.7x | 3.0x | -0.9% |
FIG | $12.7B | n/m | 90.8x | 9.9x | 8.6x | 12.5x | 10.9x | n/m | 1.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ADBE | Revenue | +12.0% | +9.1% | +8.8% |
| EPS | +17.2% | +12.7% | +14.2% | |
SSTK | Revenue | −23.3% | −8.0% | −4.9% |
| EPS | −145.9% | −148.0% | +10.2% | |
GETY | Revenue | +1.8% | +0.9% | +3.8% |
| EPS | −112.1% | +126.0% | +185.7% | |
CHGG | Revenue | −45.2% | −21.3% | — |
| EPS | +61.4% | −50.0% | — | |
FIG | Revenue | +40.5% | +23.8% | +24.2% |
| EPS | −24.5% | +26.7% | +34.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
A merger death, not a sector melt-down
Shutterstock and Getty Images together account for nearly all of the Creative & Content bucket's brutal one-month move. On July 7, 2026, Getty's board terminated the two companies' merger agreement after the UK Competition and Markets Authority demanded a forced sale of Shutterstock's editorial business as a condition of approval — ending a deal that would have combined the two largest stock-image licensors. SSTK closed at $5.98 (-57.7% over 30 days, -69.8% over 12 months) and GETY at $0.408 (-56.6%/30d, -77.8%/12m).
The termination is not just sentiment — it has a hard mechanical consequence. It triggers a special mandatory redemption of Getty's $628.4M of 10.5% senior secured notes due 2030 at par plus accrued interest unless the deal is revived by October 6, and Getty's board is now engaging a financial advisor to review strategic financing alternatives against a roughly $171M equity base — a live refinancing overhang, not a discounted risk.
SSTK's core business is also decaying on its own: Q1 2026 revenue fell 17.9% year-over-year with gross margin compression, and FY2026 consensus models a further 23.3% revenue decline into a net loss, even as the stock's 2.96x trailing EV/EBITDA and roughly 52% trailing free-cash-flow yield already appear to price continued deterioration rather than mispricing.
Chegg's bounce looks unrelated to fundamentals
Chegg sits apart from the licensors. After cutting roughly 45% of its workforce in October 2025 — its second round of layoffs in five months, blaming reduced traffic and "the new realities of AI" — the company ended 2025 with $85M in cash and a stated goal of ending 2026 debt-free while pivoting toward B2B skilling. Its trend band has stayed mild-bullish through July even as Academic Services revenue fell 57% year-over-year, a divergence the desk's own analysis reads as takeout speculation on a cash stub rather than operating recovery.
The counter-examples: Figma and Adobe
Figma is the cohort's clearest growth story: Q1 2026 revenue rose 46% year-over-year with net dollar retention hitting 139%, its highest mark in over two years, alongside raised guidance — even though Anthropic's April 2026 Claude Design launch knocked the stock 6-7.7% on a single announcement.
Adobe presents the sharpest disconnect between fundamentals and its label: AI-first ARR more than tripled year-over-year past $500M, with Firefly ARR near $300M, on record $6.62B quarterly revenue, yet its trend band has held strong-bear continuously through July 28 alongside SSTK and GETY. Four of five cohort members carry bearish trend bands, but the underlying stories driving them — a collapsed merger and refinancing scramble versus genuine AI monetization at a profitable incumbent — are not the same trade.