

SMID Biotech Takeout Cohort's 73% Year Is a Two-Speed Story
Prompt v1.0
The Barrons SMID biotech takeout bucket's +72.8% one-year return is real but concentrated in CGON, DYN and CYTK, while ALNY and MLTX are outright drags -- including a violent MLTX single-day crash the original thesis said didn't happen. Six of eight names remain in strongly bullish bands and the M&A/financing backdrop is genuinely accelerating, but ALNY, ASND and CYTK have grown too large for the bolt-on-sized deals actually getting done in 2026.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
ASND | Ascendis Pharma A/S | Autoimmune & Inflammatory Diseases | 🟢 Cont. Bull | −4.4% | +54.3% |
MLTX | MoonLake Immunotherapeutics | Monoclonal Antibodies & Immunotherapies | 🟢 Cont. Bull | −7.7% | −64.9% |
DYN | Dyne Therapeutics | Other | 🟢 Cont. Bull | +18.1% | +172.8% |
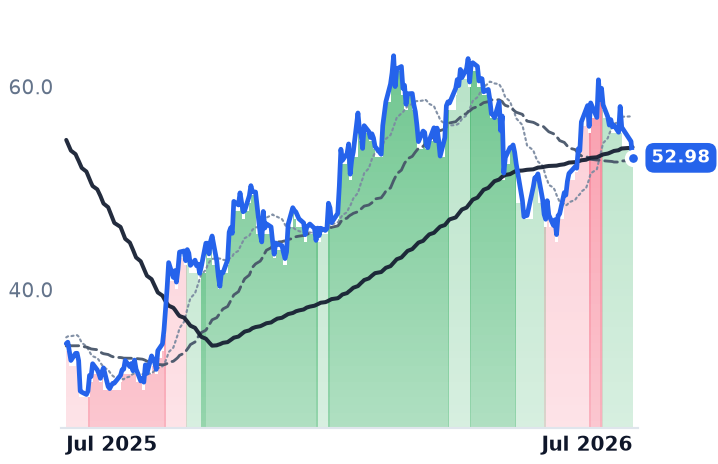
PCVX | Vaxcyte | Vaccines & Infectious Disease | 🟢 Cont. Bull | −8.2% | +52.8% |
CYTK | Cytokinetics, Incorporated | Other | 🟢 Cont. Bull | −10.2% | +118.3% |
CGON | CG Oncology | Other | 🟢 Cont. Bull | −6.3% | +165.4% |
DNLI | Denali Therapeutics | Other | 🟢 Cont. Bull | −7.9% | +75.2% |
ALNY | Alnylam Pharmaceuticals | Gene & RNA Therapeutics | 🔴 Cont. Bear | −2.4% | −13.3% |
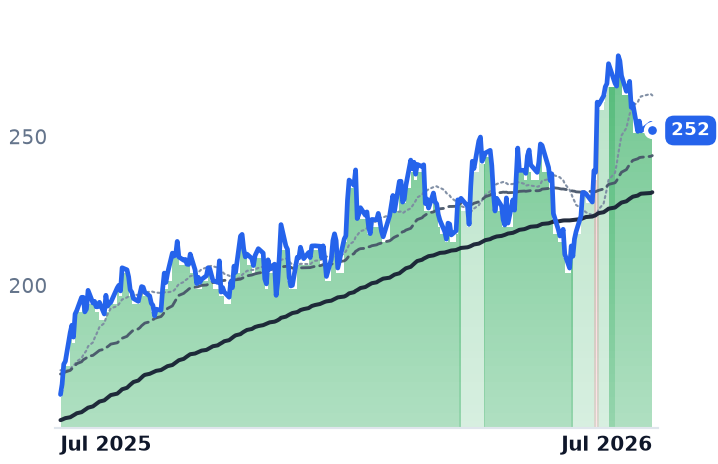
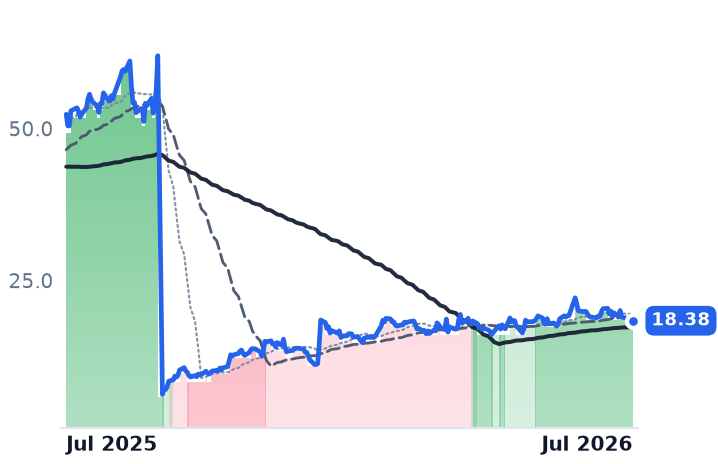
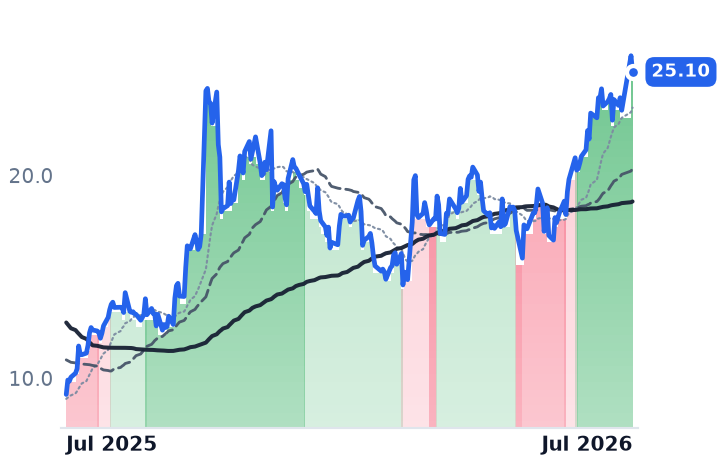
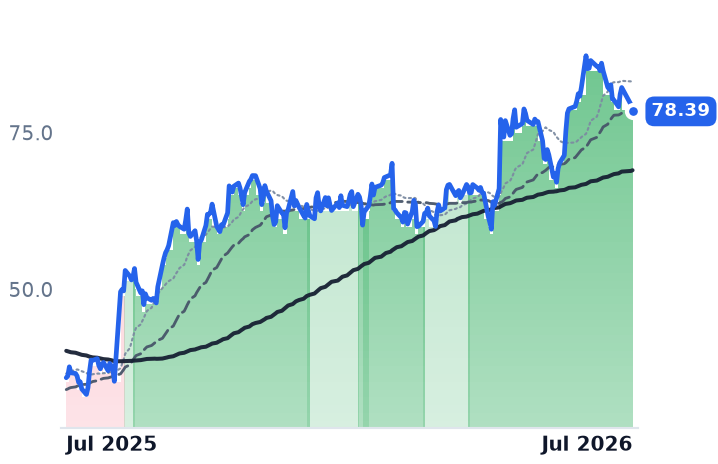
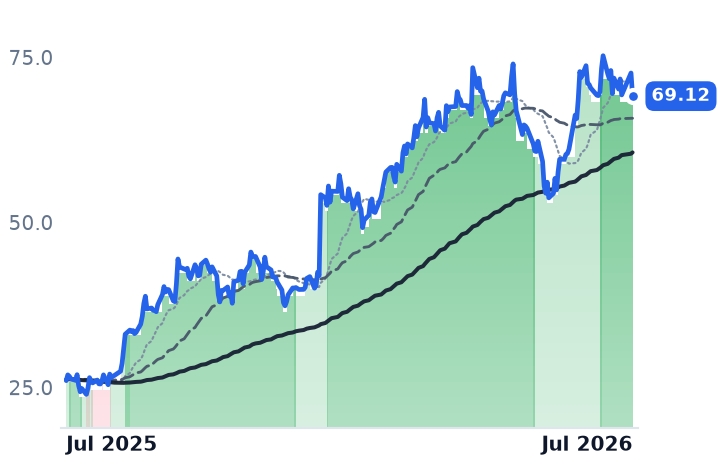
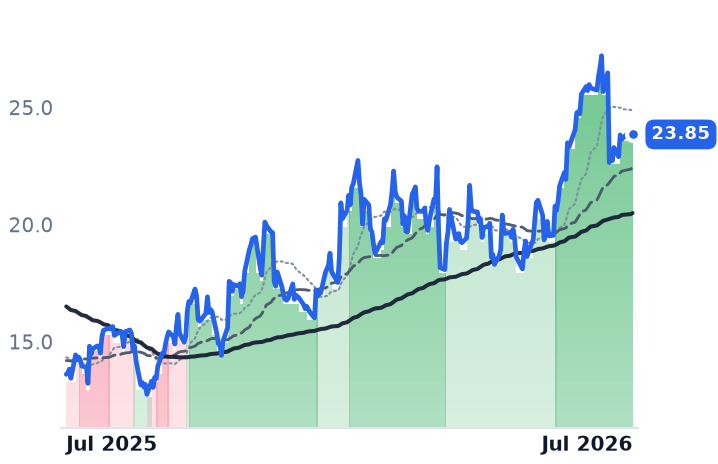
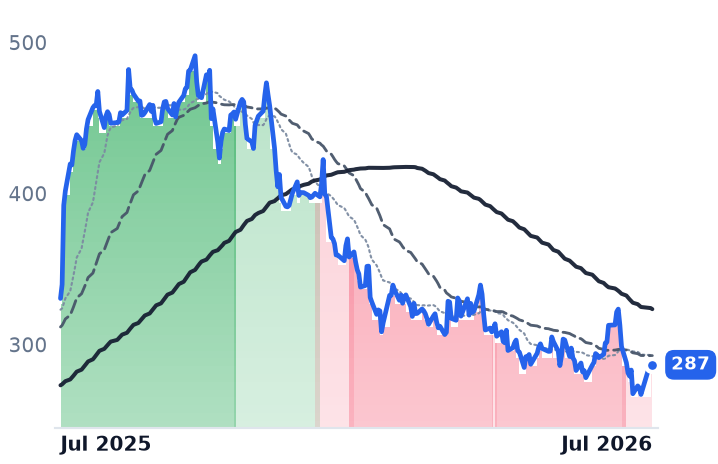
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ASND | $14.0B | 16.4x | 16.2x | 11.7x | 10.4x | 12.9x | 11.5x | 152.8x | 2.7% |
MLTX | $1.6B | n/m | — | n/m | — | — | — | n/m | -14.5% |
DYN | $3.0B | n/m | — | n/m | — | — | — | n/m | -16.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PCVX | $8.4B | n/m | — | n/m | 335.4x | — | — | n/m | -14.3% |
CYTK | $8.0B | n/m | — | 113.4x | 53.7x | 133.4x | 63.2x | n/m | -7.2% |
CGON | $6.3B | n/m | — | — | 568.3x | — | — | n/m | -2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DNLI | $3.7B | n/m | — | n/m | 104.4x | — | — | n/m | -11.5% |
ALNY | $34.2B | 42.0x | 38.4x | 7.1x | 6.3x | 8.9x | 7.9x | 29.4x | 1.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ASND | Revenue | +90.9% | +46.5% | +27.1% |
| EPS | −516.5% | −35.2% | +58.5% | |
MLTX | Revenue | — | — | +499.2% |
| EPS | +6.4% | −5.3% | −19.5% | |
DYN | Revenue | +43.8% | +5202.8% | +423.5% |
| EPS | +3.5% | −7.7% | −24.6% | |
PCVX | Revenue | — | +248.6% | +103.3% |
| EPS | +51.9% | −19.8% | −5.5% | |
CYTK | Revenue | +94.8% | +182.8% | +110.5% |
| EPS | −6.8% | −26.1% | −52.9% | |
CGON | Revenue | +292.5% | +669.5% | +432.7% |
| EPS | +26.5% | +2.4% | −97.0% | |
DNLI | Revenue | +1299.4% | +204.0% | +150.9% |
| EPS | −18.1% | +0.8% | −24.6% | |
ALNY | Revenue | +45.6% | +26.9% | +19.6% |
| EPS | +171.3% | +51.0% | +24.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The two-speed year
The headline +72.8% one-year average return for the eight-name bucket (ALNY, ASND, CGON, CYTK, DNLI, DYN, MLTX, PCVX) checks out exactly, but it is not broad-based. CGON (+180.9%), DYN (+178.2%) and CYTK (+116.9%) carry the bucket, while ALNY (-11.2%) and MLTX (-65.7%) are drags. The MLTX number is the biggest correction to the original thesis: the stock did not have a gradual re-rating -- it crashed roughly 90% in a single session on September 29, 2025 after Phase 3 VELA data showed sonelokimab was uncompetitive with Bimzelx in hidradenitis suppurativa, a result that also triggered a securities fraud class action. Alnylam tells a different but equally unflattering story: it rotated from strongly bullish in mid-2025 into strongly bearish for most of Jan-June 2026 and now sits in mildly bearish, the bucket's only bear-band name, after concerning 2026/2030 guidance sent shares down nearly 19% between October 2025 and January 2026.
Why the flat month isn't a rollover
Despite the -1.6% average 30-day return, the intact-trend read holds up: six of eight names (ASND, CGON, CYTK, DNLI, DYN, MLTX) currently sit in strongly bullish bands and PCVX is mildly bullish -- only ALNY is bearish. The flat month is a shallow, broad pullback (seven of eight names down 1.5-9%) almost entirely offset by DYN's +21.8% surge, which itself reflects an abrupt reversal rather than a slow grind: DYN was in a strongly bearish band as recently as June 1 before flipping to strongly bullish by June 23, coinciding with completion of enrollment in Dyne's ACHIEVE registrational trial for DM1, a move Yahoo Finance tied to growing confidence in Dyne's late-stage neuromuscular pipeline. ASND's mildly bullish-to-strongly bullish upgrade on July 2 is confirmed and coincides with an accelerating Yorvipath launch: full-year 2025 revenue of €477M and Q1 2026 revenue of €197M, with patient enrollments climbing from ~5,300 to over 6,300.
The M&A backdrop is real, but sizes matter
The deal environment underpinning this thesis has genuinely strengthened: 24 biopharma deals worth over $64B closed in the first four months of 2026 versus 14 deals worth $24.5B a year earlier, against a backdrop of $230B in revenue facing patent expiry by 2030. But deal structure has shifted toward $1B-$10B bolt-ons rather than mega-mergers, and antitrust regulators have kept the stricter 2023 merger guidelines in place rather than loosening them. That matters because ALNY ($39.9B), ASND ($16.7B) and CYTK ($11.5B) have all grown past the bolt-on sweet spot, even as speculative chatter persists -- Novartis and Amgen interest in Cytokinetics and unresolved takeover rumors around Ascendis. DYN ($2.86B), CGON ($5.9B), DNLI ($2.96B), MLTX ($1.29B) and PCVX ($8.4B) remain squarely in the range pharma is actually buying.
Catalysts still ahead
The binary readouts underpinning the bucket's re-rating haven't fired yet. Cytokinetics launched aficamten commercially in the EU in June 2026 following U.S. and China approvals. Vaxcyte's VAX-31 pivotal trial completed enrollment in March 2026, with topline data due Q4 2026. CG Oncology expects its cretostimogene BLA submission in Q4 2026 and holds cash into 2029, reducing near-term deal urgency for that name specifically. A biotech IPO and financing surge -- the strongest since the COVID era -- supports the broader re-rating thesis, but all eight names still carry deeply negative trailing earnings multiples, meaning the case rests on pipeline execution and takeout optionality rather than current fundamentals.