

Behind-the-meter power: BE and AGX are the last out, not the leading edge
Prompt v1.0
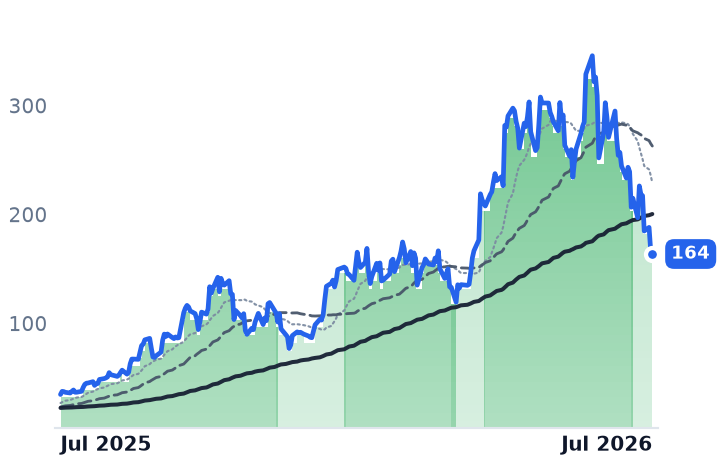
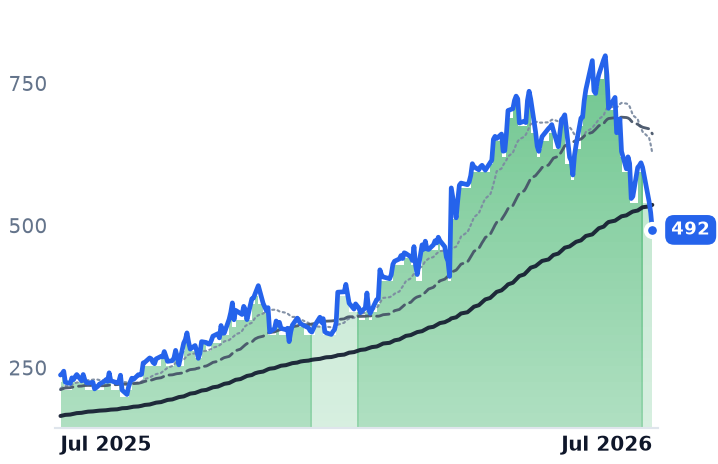
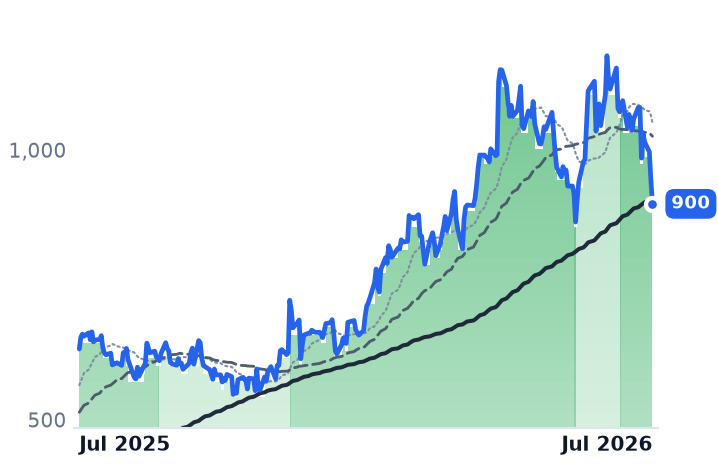
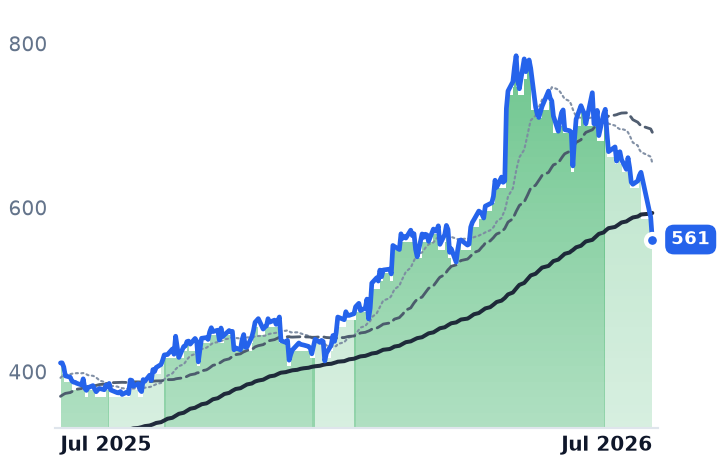
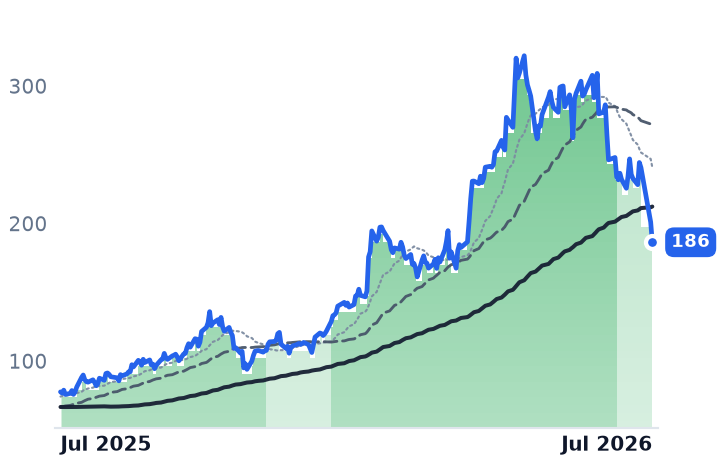
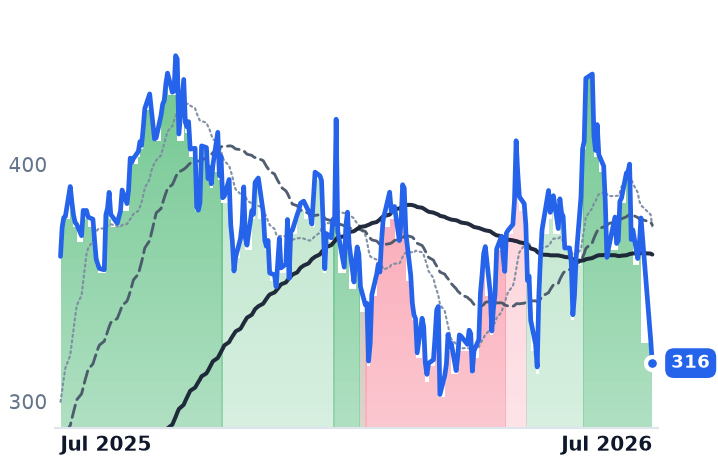
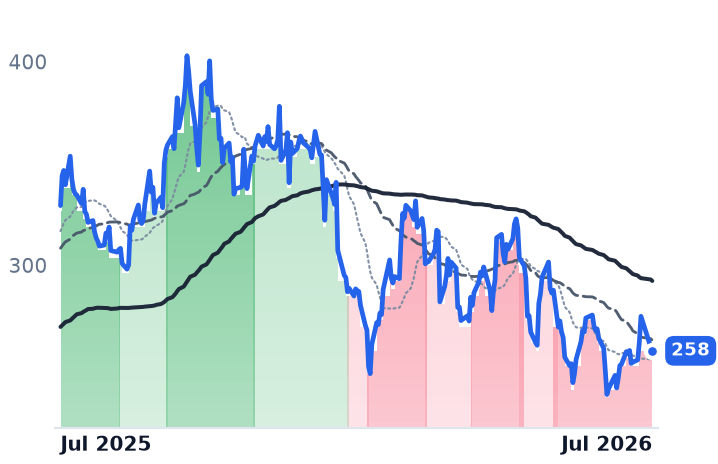
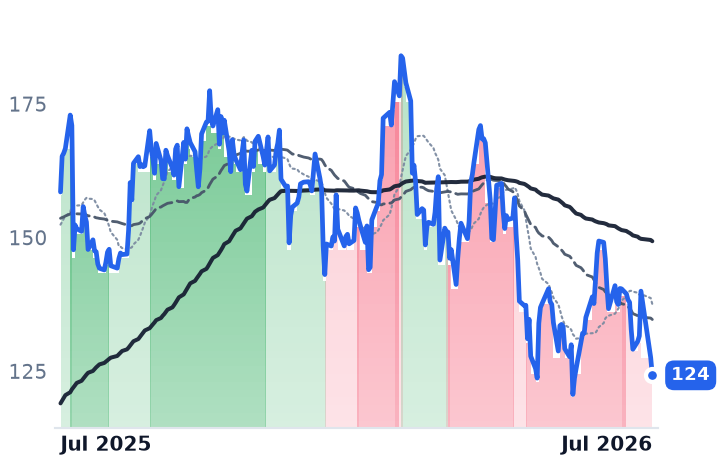
The nine-name on-site power cohort is not rolling over as one trade. Trend bands date BE (7/16) and AGX (7/22) as the last equipment names to leave strongly bullish after GEV, VRT, PWR and POWL, while the merchant/IPP leg broke a quarter earlier and is now recovering — and every macro leg of the downtrend thesis (hyperscaler capex, 48E, FERC/ERCOT co-location rules) points the other way.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
BE | Bloom Energy | Fuel Cell & Hydrogen | 🟢 Cont. Bull | −40.5% | +371.2% |
AGX | Argan | Energy Solutions | 🟢 Cont. Bull | −37.8% | +107.6% |
GEV | GE Vernova | Power Generation & Propulsion | 🟢 Cont. Bull | −18.3% | +42.6% |
PWR | Quanta Services | Power Grid & Distribution | 🟢 Cont. Bull | −21.4% | +36.6% |
POWL | Powell Industries | Power Distribution Systems | 🟢 Cont. Bull | −33.7% | +140.2% |
TLN | Talen Energy | Wholesale Generators | 🟢 Cont. Bull | −20.8% | −12.5% |
CEG | Constellation Energy | Wholesale Generators | 🔴 Cont. Bear | −0.5% | −21.7% |
NRG | NRG Energy | Retail-Focused Operators | 🔴 Cont. Bear | −16.7% | −21.6% |
VRT | Vertiv | Advanced Power Systems | 🟢 Cont. Bull | −27.3% | +56.4% |
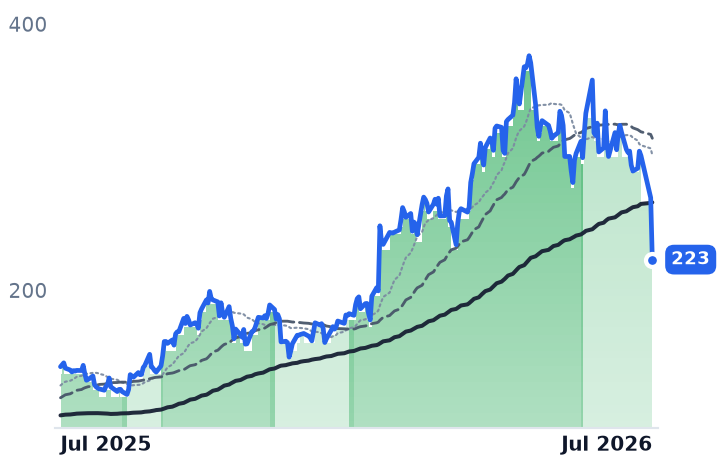
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BE | $58.1B | 110.2x | 61.7x | 15.2x | 13.1x | 46.9x | 40.4x | 94.8x | 0.8% |
AGX | $5.5B | 30.5x | 29.7x | 4.6x | 3.9x | 22.2x | 18.8x | 23.6x | 9.9% |
GEV | $211.0B | 20.7x | 25.2x | 4.8x | 4.5x | 22.0x | 20.7x | 19.0x | 8.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PWR | $82.2B | 61.8x | 32.6x | 2.5x | 2.1x | 17.4x | 14.4x | 28.5x | 2.9% |
POWL | $4.8B | 25.4x | 19.3x | 4.2x | 3.2x | 13.9x | 10.7x | 16.9x | 5.0% |
TLN | $17.2B | n/m | 18.4x | 4.9x | 3.9x | 10.9x | 8.7x | 36.8x | 3.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CEG | $107.0B | 29.0x | 24.7x | 3.5x | 3.2x | 20.0x | 18.4x | 15.8x | 0.3% |
NRG | $21.2B | — | 11.3x | — | 0.6x | — | — | 10.5x | 1.6% |
VRT | $74.8B | 35.5x | 27.1x | 5.7x | 5.1x | 15.0x | 13.4x | 24.6x | 4.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BE | Revenue | +133.5% | +61.7% | +46.1% |
| EPS | +478.2% | +67.5% | +61.2% | |
AGX | Revenue | +12.1% | +48.9% | +20.4% |
| EPS | +65.8% | +57.7% | +19.4% | |
GEV | Revenue | +25.7% | +14.1% | +15.7% |
| EPS | +334.6% | −18.6% | +38.8% | |
PWR | Revenue | +41.1% | +16.3% | +14.1% |
| EPS | +57.7% | +17.9% | +18.3% | |
POWL | Revenue | +8.8% | +25.8% | +14.4% |
| EPS | +12.1% | +27.8% | +19.8% | |
TLN | Revenue | +84.0% | +16.0% | +4.9% |
| EPS | +247.2% | +49.2% | +17.7% | |
CEG | Revenue | +37.2% | +2.5% | +5.3% |
| EPS | +28.9% | +10.4% | +26.4% | |
NRG | Revenue | +17.7% | +0.8% | +3.7% |
| EPS | +14.0% | +24.5% | +15.8% | |
VRT | Revenue | +43.2% | +32.8% | +21.3% |
| EPS | +73.3% | +37.7% | +26.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The sequence runs backwards
Band history dates a six-week stagger, not a synchronized break: GEV left strongly bullish on 6/9, VRT 6/15, PWR 6/29, POWL 7/7, BE 7/16 and AGX 7/22. GEV then re-entered strongly bullish on 7/8 and was still there at its last session on 7/27. All six names sit below their 50-day but above their 200-day averages — BE at $188.18 against a $176.98 200-day, AGX $542.52 vs $480.55, GEV $996.57 vs $830.15, PWR $643.14 vs $554.45, POWL $240.68 vs $186.72, VRT $301.16 vs $242.92. BE and AGX are the laggards of the move, not its leading edge.
The IPP leg went the other way
CEG has been in strongly bearish since 5/29 yet rose 11.8% between 7/6 and 7/22 — the same window in which BE fell 36% and AGX 25%. NRG improved from strongly bearish to mildly bearish on 7/10; TLN has held strongly bullish since 6/16. CEG's strength traces to dated sector catalysts including a Walmart nuclear PPA and the closed $27bn Calpine deal. The regulatory backdrop is constructive too: FERC's December 2025 order directed PJM to write co-location and behind-the-meter rules — the product of Constellation's 2024 complaint that followed FERC's Susquehanna rejection — while Texas SB6 gives large loads with on-site generation preferential batch-study treatment.
Every macro leg fails on the dates
Hyperscaler spend was raised, not digested: the big four are tracking roughly $725bn of 2026 capex, up 77%, with Microsoft near $190bn and Amazon ~$200bn, and 2027 consensus above $1tn. What did change was sentiment — Amazon, Meta and Microsoft sold off into their prints after Alphabet's report was panned. The OBBBA made fuel cells 48E-eligible at a flat 30% with no emissions threshold. Quanta printed record $48.5bn backlog. Bloom's 7/28 print beat on revenue (~$1.065bn vs ~$828m) and EPS and raised full-year guidance, with shares up ~11% after hours; the pre-print pressure was a dispute over ~$20bn cited backlog vs ~$492m of audited performance obligations, and Argan's slide tracks ~$119.4m of insider selling plus a small sequential backlog dip.
Two data caveats
Six of the nine symbols' prices stop on 7/22 while BE, AGX and GEV run to 7/27, so the "two worst on the watchlist" ranking is partly a window artifact. And the slide was not gap-free: BE opened 7/24 at its session high of $214.19 and closed $184.89 (-14.9% on 16m shares), while AGX has no 7/24 bar and gapped down 5.6% on 7/27. The residual bear case in the desk's notes is fuel supply — Chronometer Partners' argument that Bloom cannot source ~150 MMcf/d per GW for 24/7 baseload — not order books.