

The AI content/data-services cohort has no breadth — and Indian IT is bouncing
Prompt v1.0
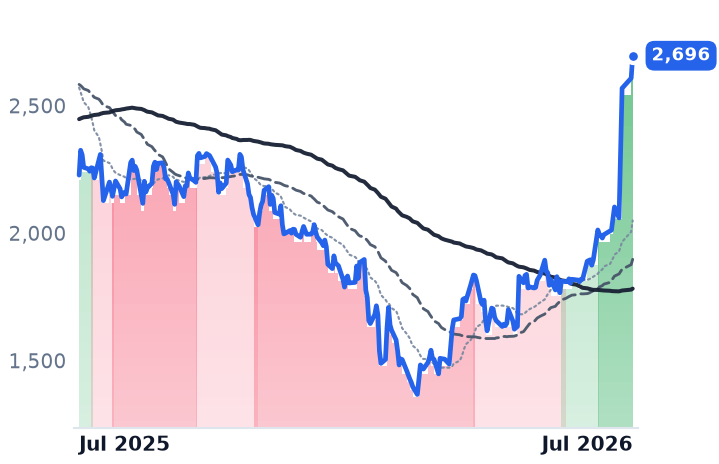
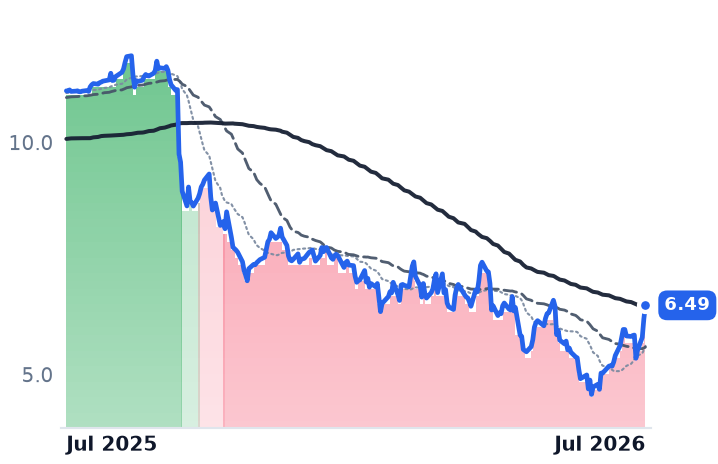
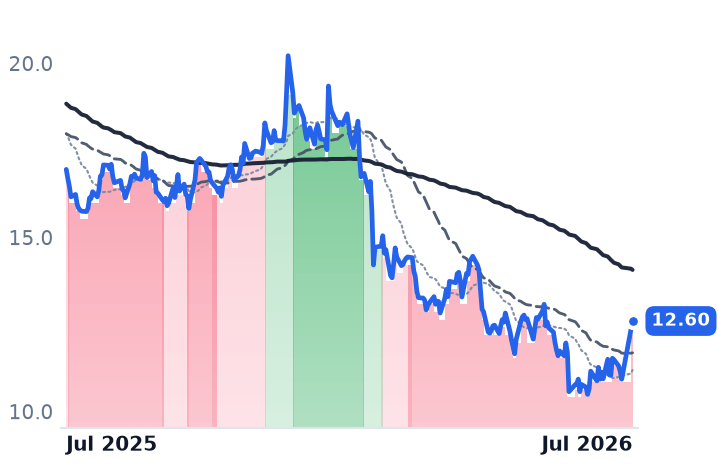
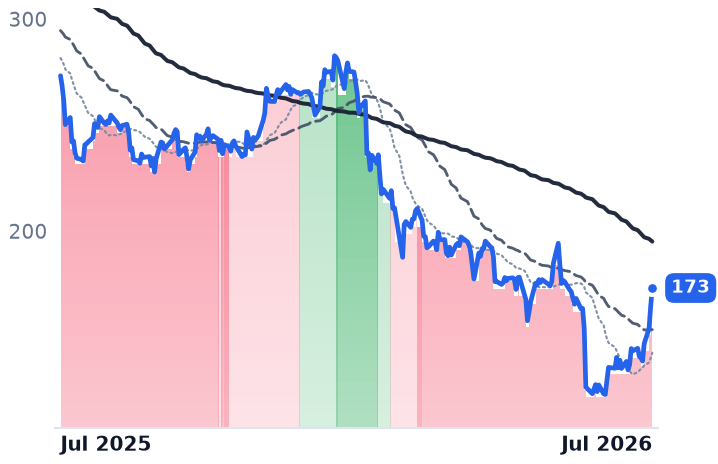
MPS's +42% month is really two sessions at a 20% upper circuit on 80x volume, and the cohort meant to confirm it doesn't exist: Tata Elxsi is at a 52-week low, TaskUs is 71% below its high, Firstsource is -26% on the year. Meanwhile large-cap Indian IT rose 12.2% in July on a broker upgrade — a sector-wide bounce, not a rotation into content operations.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
MPSLTD.BO | MPS | Publishing | 🌱 Emerging Bull | +42.7% | +21.0% |
ECLERX.NS | ECLERX.NS | — | 🔴 Cont. Bear | — | — |
FSL.NS | FSL.NS | — | 🔴 Cont. Bear | — | — |
TATAELXSI.NS | TATAELXSI.NS | — | 🔴 Cont. Bear | — | — |
TASK | TaskUs | Customer Experience & Operations | 🔴 Cont. Bear | +35.5% | −41.6% |
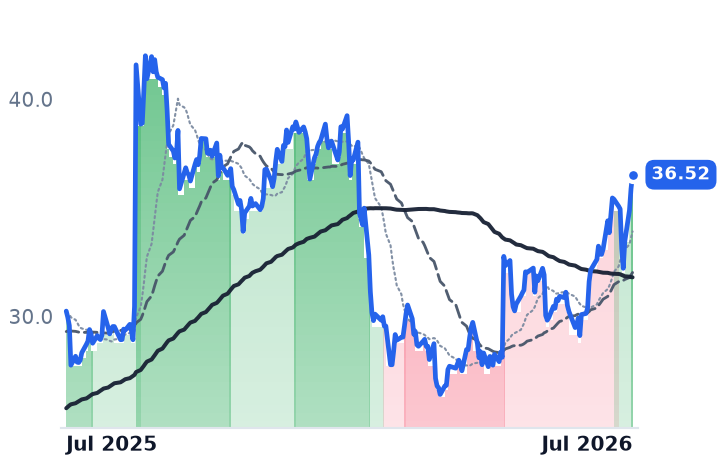
IBEX | IBEX | Customer Experience & Operations | 🟢 Cont. Bull | +21.2% | +20.8% |
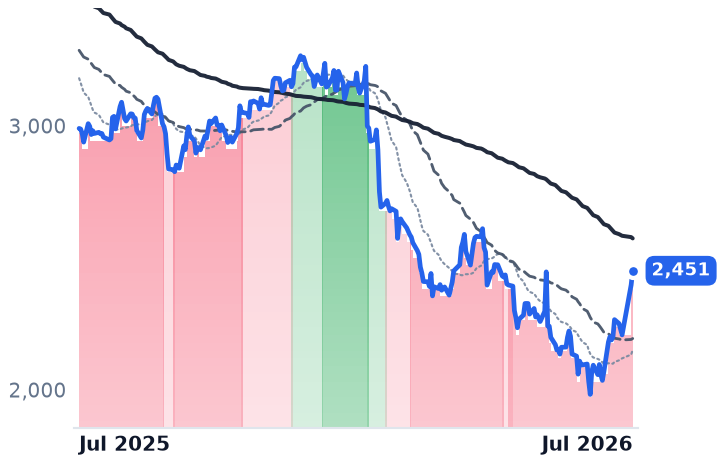
TCS.NS | Tata Consultancy Services | Information Technology Services | 🔴 Cont. Bear | +16.8% | −18.0% |
INFY | Infosys | Consulting & Professional Services | 🔴 Cont. Bear | +17.8% | −25.7% |
ACN | Accenture | Consulting & Professional Services | 🔴 Cont. Bear | +40.5% | −36.6% |
CTSH | Cognizant Technology Solutions | Consulting & Professional Services | 🔴 Cont. Bear | +44.5% | −24.2% |
INOD | Innodata | Research & Analytics Services | 🟢 Cont. Bull | −27.3% | +18.0% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MPSLTD.BO | $31.1B | 17.9x | 16.3x | 4.2x | 3.4x | 5.2x | 4.2x | 12.9x | 3.2% |
ECLERX.NS | — | — | — | — | — | — | — | — | — |
FSL.NS | — | — | — | — | — | — | — | — | — |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TATAELXSI.NS | — | — | — | — | — | — | — | — | — |
TASK | $833.4M | 8.0x | 6.8x | 0.7x | 0.7x | 2.1x | 2.0x | 5.6x | 12.1% |
IBEX | $660.8M | 13.5x | 13.4x | 1.0x | 0.9x | 4.6x | 4.3x | 9.2x | 4.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TCS.NS | $9.1T | 17.5x | 16.3x | 3.2x | 3.1x | 9.0x | 8.7x | 12.3x | 5.6% |
INFY | $50.7B | 20.9x | 15.6x | 3.4x | 2.5x | 11.3x | 8.2x | 14.6x | 5.3% |
ACN | $154.0B | 19.1x | 17.7x | 2.1x | 2.0x | 6.5x | 6.2x | 11.6x | 7.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CTSH | $28.9B | 11.8x | 11.2x | 1.3x | 1.3x | 4.1x | 4.1x | 7.2x | 8.2% |
INOD | $2.1B | 44.7x | 59.1x | 6.6x | 5.8x | 15.4x | 13.7x | 27.4x | 10.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | FY2029E | |
|---|---|---|---|---|---|
MPSLTD.BO | Revenue | +5.5% | +17.7% | +14.1% | — |
| EPS | +14.0% | +16.8% | +18.4% | — | |
TASK | Revenue | +6.2% | +6.2% | +7.9% | — |
| EPS | −15.0% | +11.2% | +9.3% | — | |
IBEX | Revenue | +17.6% | +11.3% | +6.8% | — |
| EPS | +36.4% | +5.1% | +10.4% | — | |
TCS.NS | Revenue | +4.0% | +10.1% | +4.6% | — |
| EPS | +4.0% | +9.0% | +4.0% | — | |
INFY | Revenue | +1.6% | +5.4% | +3.2% | — |
| EPS | +2.4% | +5.3% | +4.5% | — | |
ACN | Revenue | +6.0% | +5.3% | +5.1% | — |
| EPS | +7.6% | +5.9% | +8.7% | — | |
CTSH | Revenue | +4.8% | +3.8% | +4.3% | — |
| EPS | +11.2% | +8.6% | +7.9% | — | |
INOD | Revenue | +43.5% | +28.4% | — | −64.1% |
| EPS | +23.0% | +60.1% | — | −53.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The cohort doesn't hold together
The test for an early sub-sector uptrend is breadth: three or more names moving to better trend bands and sitting above their 200-day averages. It fails on inspection. Tata Elxsi hit a 52-week low on 15 July and is down 44% over twelve months, after a Q1 FY27 in which revenue crossed ₹1,000 crore for the first time but EBITDA margin fell 340bps QoQ to 21.2%. TaskUs traded at $5.31 against a $18.39 52-week high. Firstsource sat at ₹253.6, down 25.9% over twelve months, with Q1 not due until 6 August — no catalyst inside the window at all.
Only eClerx moved with MPS, rallying over 27% in July while still ~29% below its own 52-week high — and it has the most substantive AI leg of the group: FY26 revenue +22%, a first large-scale Agentic AI win, and an Automation & Analytics segment near US$90 million. IBEX confirms the AI-BPO demand but dates to May, not July: record $164.4m revenue, raised guidance, a Sierra.ai partnership.
The rotation leg is contradicted outright
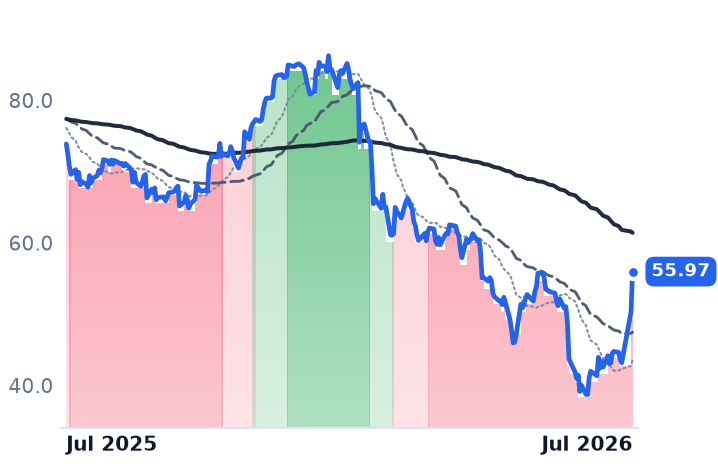
Legacy Indian IT did not stay down. Nifty IT gained 12.2% in July, its best month in two years, with HCL Tech and Tech Mahindra up 20% from 52-week lows, and the proximate catalyst was not AI but a foreign brokerage upgrade to Neutral from Underweight that drove a ~7% three-session rally. On 27 July OFSS +3.9%, Infosys +3.6%, TCS +2.2% led the tape, while Tech Mahindra's Q1 showed $1,078 million of total contract value. The currency tailwind is real but shared by every dollar-revenue exporter: USD/INR peaked at 96.84 in May before easing to ~94.35. Our own price table agrees — over the trailing month TCS +3.8%, ACN +12.2%, CTSH +3.2%, INFY +1.5%, even as all four remain in strongly bearish bands over 90 days (INFY -22.3%, ACN -28.0%, CTSH -28.6%).
Where the AI data money actually landed
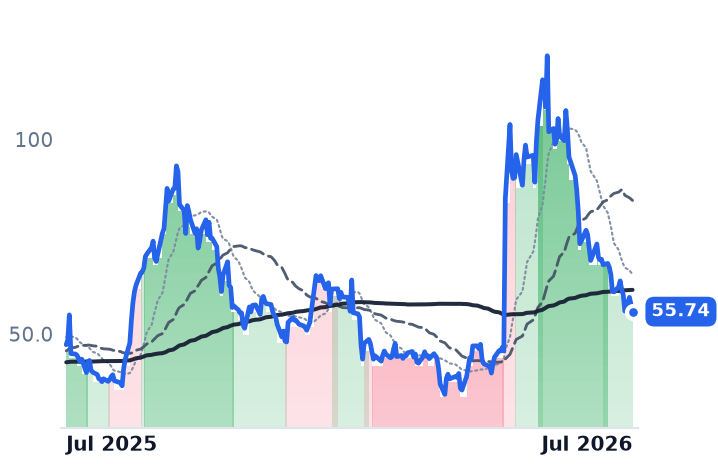
MPS itself: 24.7 of ~42 points came in two sessions, locked at a 20% upper circuit on Q1 revenue +20.4% and net profit +43%, on 96,087 shares against a 1,205-share average. It has since traded to ₹2,683 on 27 July, roughly 19–29% above the sell-side targets that sparked the move, on ~$25,000 of daily turnover. Management framed AI as a margin lever inside existing work; the licensing pool sits upstream, where Wiley booked $49 million of AI licensing revenue. The $3bn annotation market is shifting toward expert and regulated-domain work rather than offshore labour arbitrage, and content licensing stays concentrated at publishers — Meta with seven, News Corp ~$50m/yr, Reddit ~$130m/yr, only 4 in 10 deals with training rights. TaskUs shows the shape of the problem: AI Services +36.1% YoY but only ~18% of revenue. The listed vehicle capturing the theme is Innodata, +66.6% YTD with Q1 revenue +54% and $68m of pre-training data wins, reporting Q2 on 30 July.