

Memory's synchronized top: CXMT's debut adds a supply shock to the unwind
Prompt v1.0
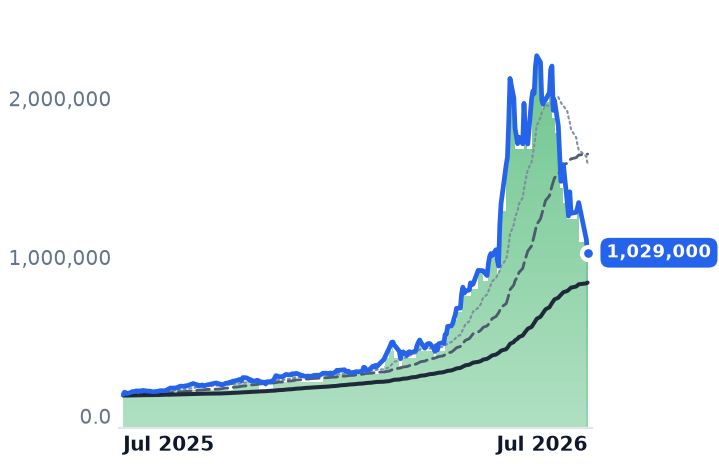
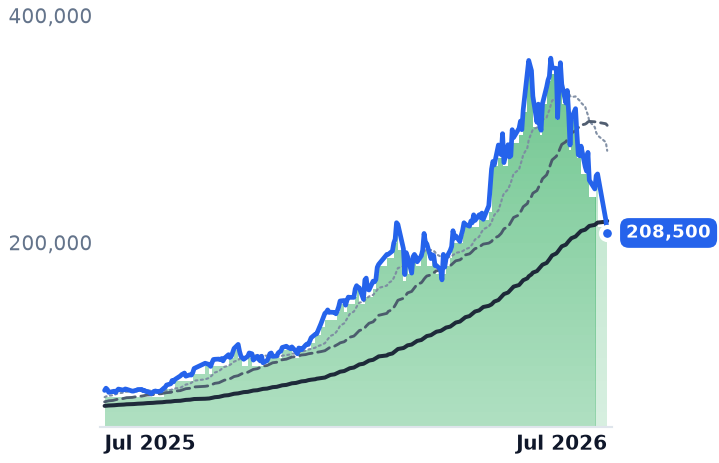
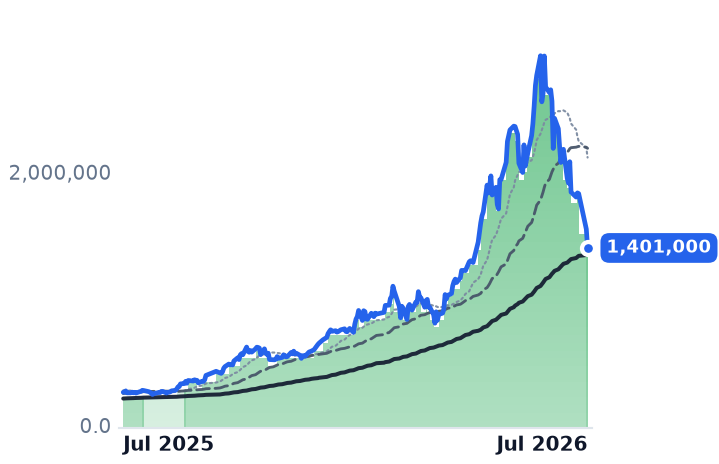
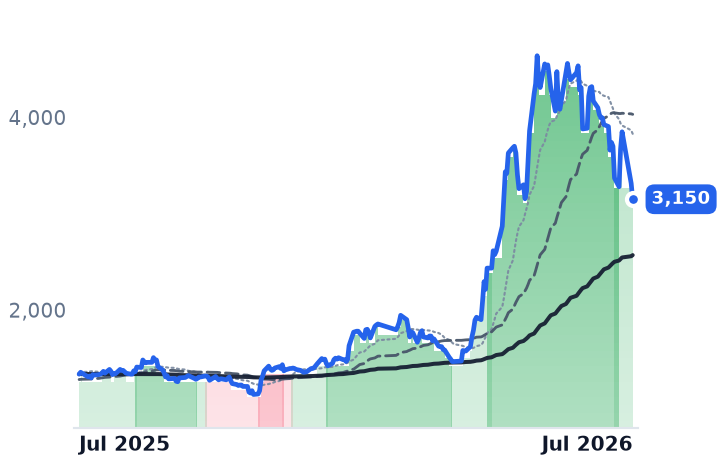
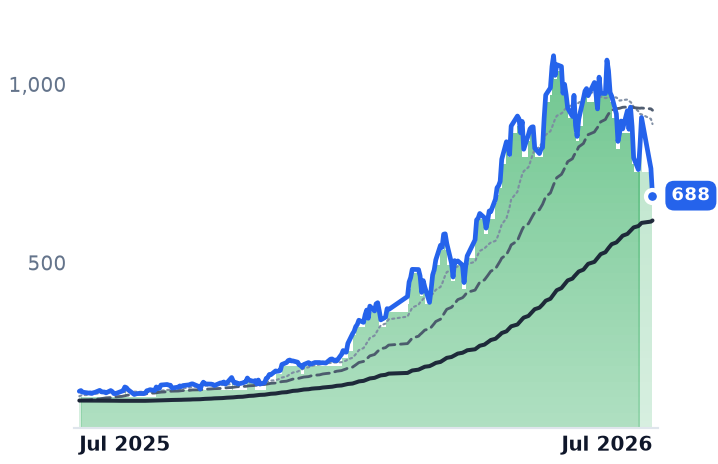
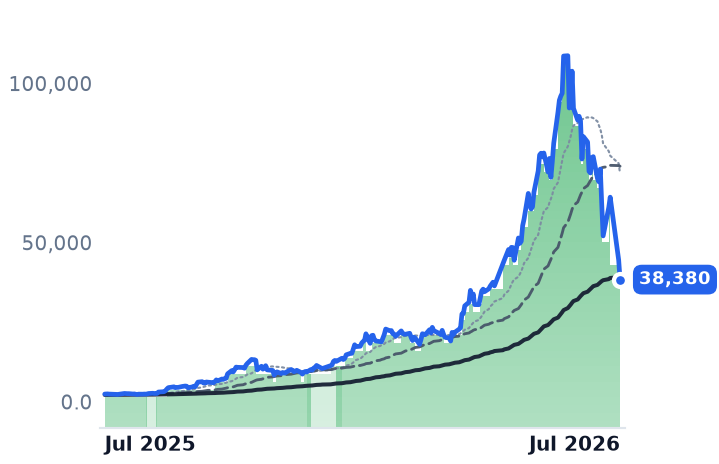
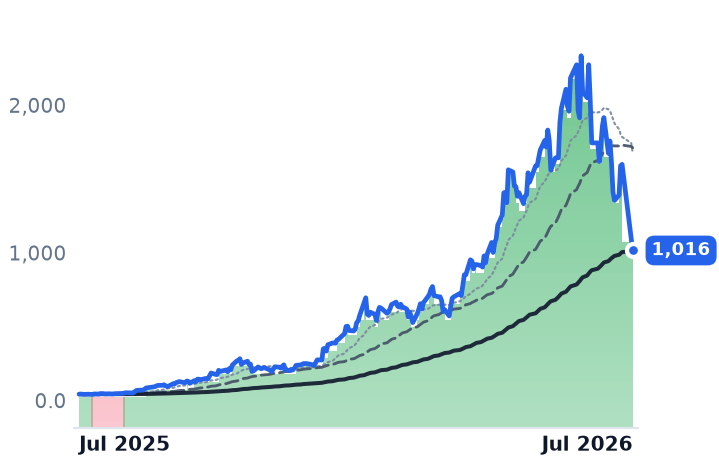
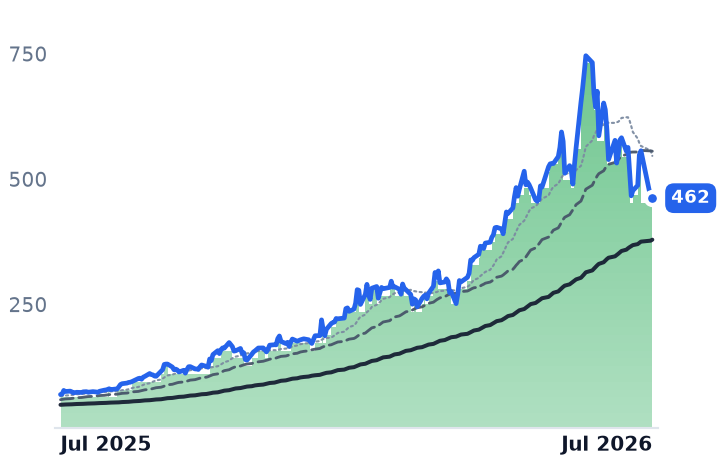
Nine Asia- and US-listed memory/AI-component names all topped between 27 May and 25 June 2026 and fell together — 009150.KS is down 40.7% from its high but still +900% over twelve months and 98% above its 200-day average. The de-rating is a multiple unwind on record fundamentals, with China's CXMT IPO now adding a genuine supply-side worry on top.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
009150.KS | Samsung Electro-Mechanics | Hardware, Equipment & Parts | 🟢 Cont. Bull | −49.5% | +655.8% |
005930.KS | Samsung Electronics | Consumer Electronics | 🟢 Cont. Bull | −35.4% | +198.7% |
000660.KS | SK hynix | Semiconductors | 🟢 Cont. Bull | −46.7% | +435.9% |
2454.TW | MediaTek | Semiconductors | 🟢 Cont. Bull | −19.0% | +136.1% |
3037.TW | Unimicron Technology | Hardware, Equipment & Parts | 🟢 Cont. Bull | −29.4% | +391.4% |
285A.T | Kioxia | Hardware, Equipment & Parts | 🟢 Cont. Bull | −56.6% | +1480.7% |
5801.T | Furukawa Electric | Electrical Equipment & Parts | 🟢 Cont. Bull | −37.3% | −65.8% |
MU | Micron Technology | Memory & Storage | 🟢 Cont. Bull | −35.5% | +561.0% |
SNDK | Sandisk | Consumer Hardware | 🟢 Cont. Bull | −50.5% | +2266.4% |
WDC | Western Digital | Enterprise Storage | 🟢 Cont. Bull | −29.1% | +556.0% |
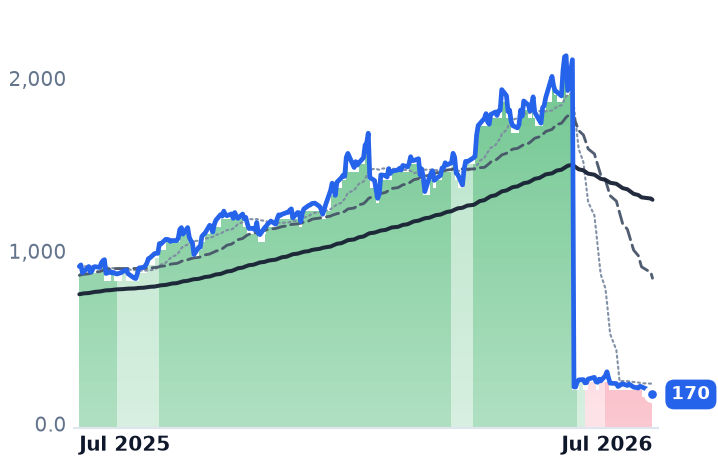
KLAC | KLA | Fabrication Equipment & Materials | ⚠️ Emerging Bear | −38.9% | −81.3% |
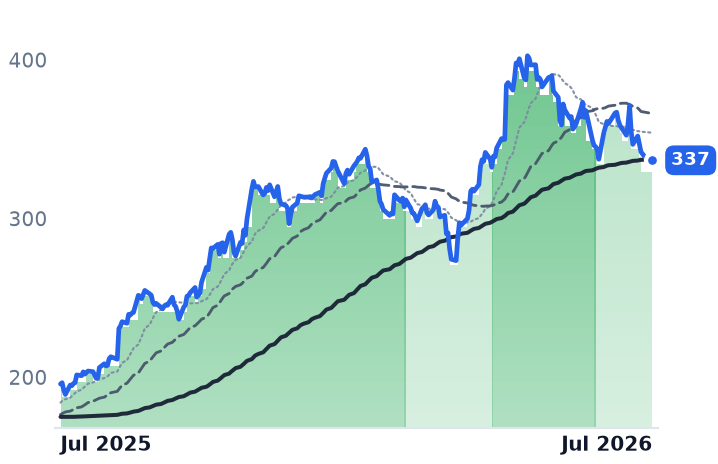
GOOGL | Alphabet | Search & Advertising | 🟢 Cont. Bull | −4.8% | +72.0% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
009150.KS | $100.8T | 104.9x | 68.5x | 8.1x | 7.1x | 40.0x | 34.9x | 46.4x | 0.4% |
005930.KS | $1800.1T | 22.0x | 7.0x | 4.6x | 2.8x | 17.8x | 10.8x | 13.9x | 2.0% |
000660.KS | $1135.3T | 15.5x | 6.1x | 8.6x | 3.6x | 12.6x | 5.3x | 11.8x | 3.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
2454.TW | $5.5T | 54.8x | 52.1x | 9.2x | 8.4x | 20.0x | 18.3x | 42.1x | 2.0% |
3037.TW | $1.8T | 73.0x | 57.6x | 12.0x | 9.6x | 65.3x | 52.3x | 47.2x | -0.3% |
285A.T | $23.7T | 140.8x | 8.3x | 14.1x | 3.9x | 54.5x | 15.2x | 39.1x | 0.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
5801.T | $2.0T | 22.3x | 17.2x | 1.4x | 1.3x | 8.1x | 7.2x | 13.2x | 0.0% |
MU | $1.0T | 19.9x | 12.2x | 11.2x | 7.8x | 15.4x | 10.7x | 14.5x | 2.6% |
SNDK | $232.3B | 20.2x | 7.5x | 11.5x | 4.8x | 16.1x | 6.7x | 17.4x | 4.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WDC | $125.5B | 13.4x | 17.7x | 9.7x | 6.5x | 19.9x | 13.4x | 14.4x | 2.6% |
KLAC | $180.4B | 34.4x | 24.0x | 12.4x | 9.6x | 20.2x | 15.6x | 28.2x | 2.2% |
GOOGL | $4.0T | 16.6x | 15.8x | 8.4x | 7.9x | 13.7x | 13.0x | 12.6x | 0.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
009150.KS | Revenue | +26.8% | +32.3% | +30.0% |
| EPS | +127.8% | +107.2% | +54.8% | |
005930.KS | Revenue | +93.0% | +19.5% | +7.5% |
| EPS | +521.0% | +25.1% | +5.2% | |
000660.KS | Revenue | +225.0% | +34.1% | +9.7% |
| EPS | +373.8% | +29.8% | +6.7% | |
2454.TW | Revenue | +9.0% | +48.5% | +41.9% |
| EPS | −1.4% | +78.4% | +59.9% | |
3037.TW | Revenue | +41.6% | +48.7% | +34.8% |
| EPS | +453.6% | +93.3% | +69.4% | |
285A.T | Revenue | +33.2% | +168.7% | +20.3% |
| EPS | +96.3% | +452.8% | +24.1% | |
5801.T | Revenue | +8.8% | +19.6% | +13.1% |
| EPS | +84.6% | +119.9% | +28.7% | |
MU | Revenue | +248.0% | +92.8% | +11.4% |
| EPS | +804.9% | +111.2% | +7.9% | |
SNDK | Revenue | +174.4% | +143.0% | +18.2% |
| EPS | +2369.0% | +214.5% | +22.1% | |
WDC | Revenue | +37.0% | +49.5% | +38.4% |
| EPS | +106.6% | +105.3% | +60.4% | |
KLAC | Revenue | +12.2% | +39.5% | +20.1% |
| EPS | +14.5% | +55.5% | +23.1% | |
GOOGL | Revenue | +24.7% | +25.2% | +21.5% |
| EPS | +93.6% | −25.5% | +19.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
One top, nine names
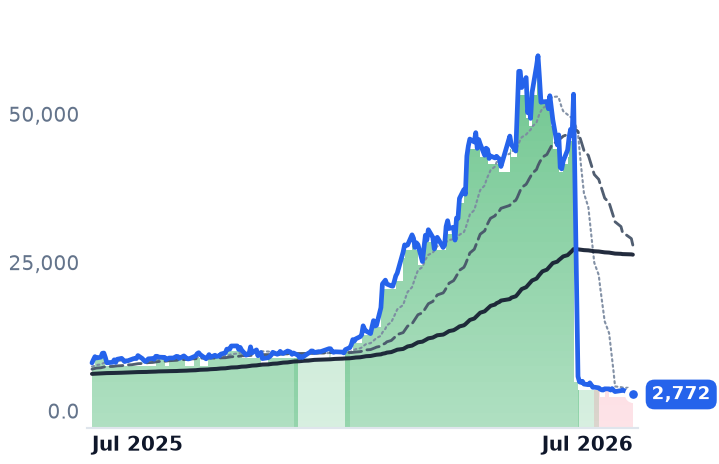
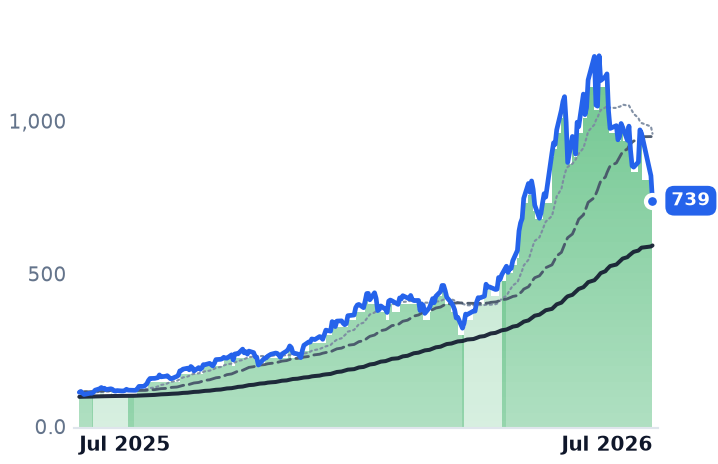
This is not an idiosyncratic Samsung Electro-Mechanics story. Every live name in the cohort peaked inside a four-week window: 2454.TW and 3037.TW on 27 May; 005930.KS and WDC on 18 June; 009150.KS on 19 June; 000660.KS and Kioxia (285A.T) on 22 June; MU and SNDK on 25 June. Drawdowns from those highs as of the 22 July close ran 285A.T -40.9%, 009150.KS -40.7%, 000660.KS -37.3%, SNDK -31.5%, 005930.KS -28.1%, WDC -25.4%, MU -20.9%, with the Taiwan pair down 16-17%.
The shape is violent, not gradual. 009150.KS printed seven sessions of 8%+ declines between 23 June and 22 July, including -14.9% on 13 July — interspersed with a +12.1% rebound. The dated Asia trigger was 2 July, when a Wall Street chip rout forced a rare KOSPI trading halt as SK Hynix fell ~14.6%. By 7 July the group had crossed into technical bear-market territory, with roughly $1.5 trillion of semiconductor market value erased since 25 June.
The demand legs didn't crack
Every fundamental input the bear case needed went the other way. TrendForce's 3 July update still has 3Q26 DRAM and NAND contract prices rising, NAND +10-15% QoQ, merely decelerating. HBM4 pricing is set to roughly double next year, mid-$500s per stack versus mid-$300s for HBM3E. Alphabet raised 2026 capex to $195-205bn on 22 July — the 7% stock drop was about spending more, not less — and Amazon, Meta and Microsoft face the same scrutiny this week. SK Hynix's 29 July print is expected to be a record on both revenue and operating profit. 009150.KS itself, up 756% in 1H26 and guided to 93% YoY Q2 operating profit growth, won a ₩295.1bn AI-server MLCC contract on 23 July.
What is genuinely new
On 27 July China's ChangXin Memory debuted on the STAR Market up ~470% after an $8.6bn raise, the mainland's largest listing since 2010. That is a supply-side event, and it landed: SanDisk fell 12%, Micron 5% and SK Hynix ADRs 6% on 28 July on fears of Chinese commodity-DRAM capacity. Kioxia is now over 60% below its June record and reports 31 July.
Two cautions on the tape. Furukawa (5801.T, -91%) and KLA (-88%) are 10-for-1 split artifacts, not crashes. And band data through 22 July still shows 009150.KS, 000660.KS, 285A.T, MU, SNDK and WDC in unbroken strongly bullish, every cohort name 39-105% above its 200-day average — readings the post-cutoff selling has likely already stale-dated. Morgan Stanley's Joseph Moore called the decline a "compelling entry point" on 20 July; the Desk's own May notes flagged that a capex-digestion signal could trigger a 30-50% de-rate across the AI hardware complex. Neither has been settled.