

Consumer Finance Cohort's Bull Run Is Broad, But Not Uniform
Hypothesis Opus 5 · Research Sonnet 5 · Writing Sonnet 5 · Prompt v1.0
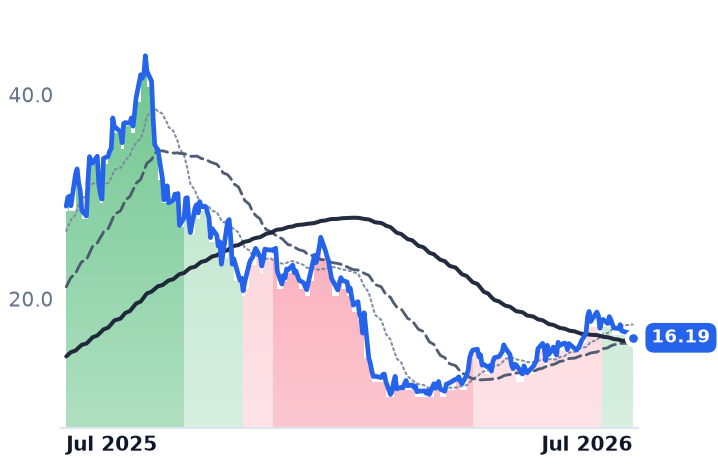
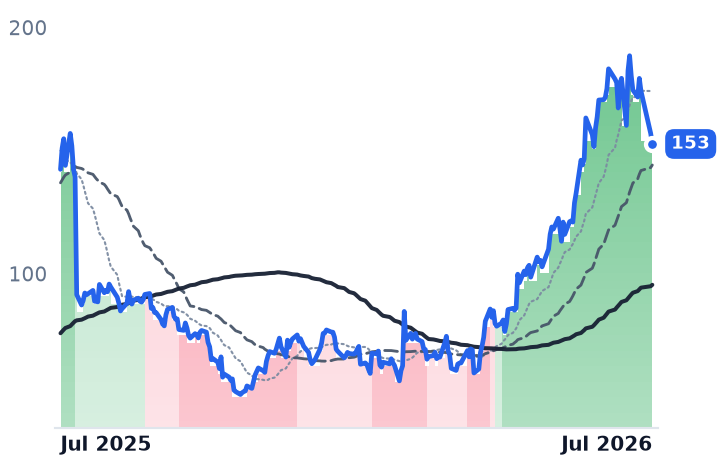
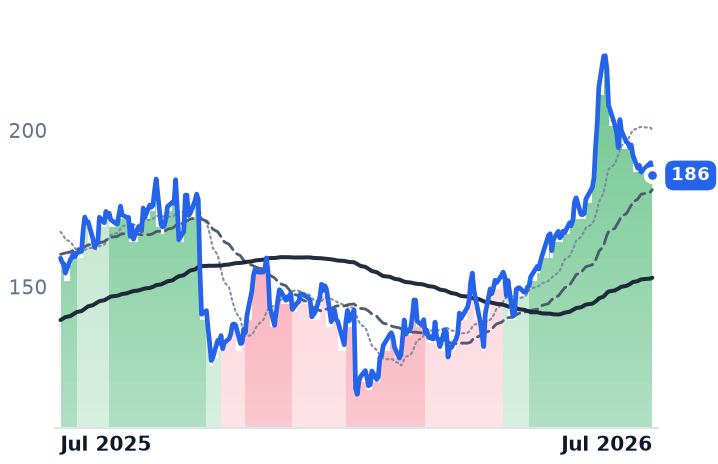
Five of the seven names in Ram Ahluwalia's consumer finance bucket (BFH, DAVE, ENVA, SEZL, WRLD) have held strongly bullish trend bands for 60+ straight trading days, backed by genuinely improving charge-off and delinquency data across the group — but the cohort's 42% one-year average masks huge dispersion, with PGY still down over the year and SYF only just confirming a bull band in July.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
DAVE | Dave | Fintech & Digital Finance | 🟢 Cont. Bull | +2.0% | +72.1% |
ENVA | Enova International | Other | 🟢 Cont. Bull | +3.8% | +135.6% |
SYF | Synchrony Financial | Consumer Credit & Cards | ⚠️ Emerging Bear | −4.3% | +6.9% |
BFH | Bread Financial | Consumer Credit & Cards | 🟢 Cont. Bull | −1.6% | +72.2% |
PGY | Pagaya Technologies | Fintech Data & AI | 🔴 Cont. Bear | −2.6% | −44.3% |
SEZL | Sezzle | Digital Payments & Fintech Platforms | 🌱 Emerging Bull | −10.5% | +7.2% |
WRLD | World Acceptance | Alternative Credit & Lending | 🌱 Emerging Bull | −17.1% | +16.6% |
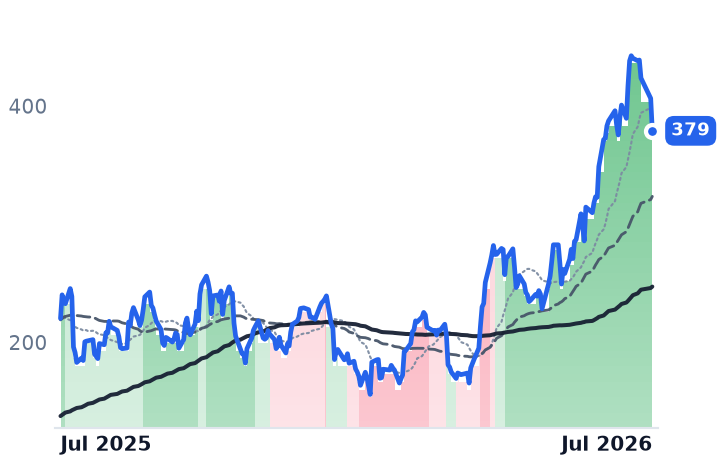
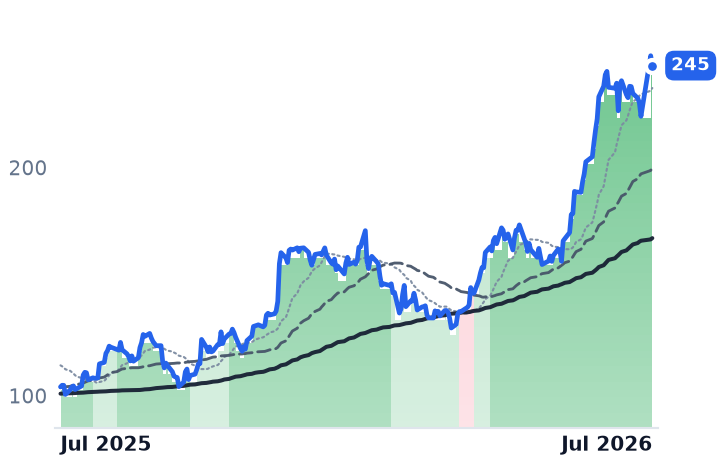
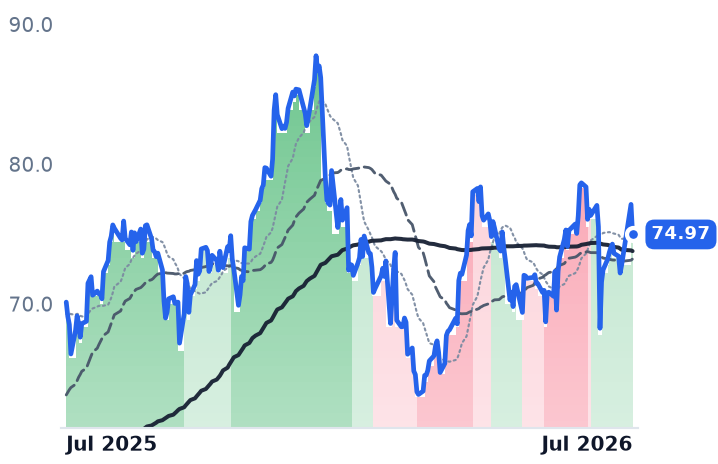
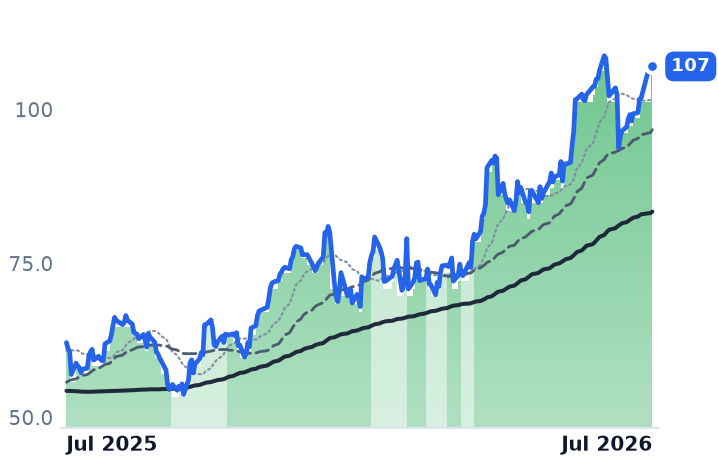
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DAVE | $3.2B | 14.1x | 15.5x | 5.6x | 4.5x | 7.2x | 5.7x | 16.0x | 10.3% |
ENVA | $4.1B | 12.5x | 10.0x | 1.2x | 1.1x | 1.9x | 1.7x | 13.7x | 45.5% |
SYF | $24.1B | 6.8x | 7.7x | 1.2x | 1.6x | 2.0x | 2.6x | 4.0x | 40.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BFH | $3.5B | 6.6x | 7.8x | 0.7x | 0.9x | 1.2x | 1.4x | 5.2x | 62.1% |
PGY | $1.1B | 12.2x | 9.9x | 0.9x | 0.8x | 2.1x | 1.8x | 9.4x | 20.9% |
SEZL | $3.3B | 22.5x | 19.4x | 6.9x | 5.6x | 7.8x | 6.3x | 17.3x | 7.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WRLD | $756.2M | 20.8x | 13.9x | 1.3x | 1.2x | 1.8x | 1.7x | 22.4x | 33.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DAVE | Revenue | +28.8% | +18.2% | −22.2% |
| EPS | +22.2% | +17.0% | −61.8% | |
ENVA | Revenue | +19.9% | +17.3% | +25.1% |
| EPS | +28.4% | +21.5% | +32.5% | |
SYF | Revenue | +2.0% | +5.5% | +3.9% |
| EPS | −0.3% | +13.2% | +11.1% | |
BFH | Revenue | +3.5% | +4.0% | +3.1% |
| EPS | +8.8% | +13.9% | +13.5% | |
PGY | Revenue | +11.8% | +13.4% | +11.9% |
| EPS | +53.5% | +38.6% | +48.1% | |
SEZL | Revenue | +32.4% | +27.0% | — |
| EPS | +51.5% | +27.4% | — | |
WRLD | Revenue | +7.1% | +9.6% | +6.0% |
| EPS | −49.5% | +55.4% | +28.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
A genuine cohort move, not a SEZL illusion
The trend-band data supports the core thesis: BFH, DAVE, ENVA, SEZL, and WRLD have all sat in a continuous strongly bullish moving-average trend signal band for 60-plus trading days through July 28, with WRLD upgraded from mildly bullish to strongly bullish back on May 14 and holding since. That is five of seven names confirming together, which argues this is a cohort-level re-rating rather than a two-name fintech story. The laggards, however, are not who the hypothesis flagged — it is SYF, not BFH, that spent all of June in a strongly bearish band before flipping to mildly bullish only on July 2, and PGY that sat in mildly bearish through July 8 before confirming bullish just three weeks ago.
Credit is actually improving
The fundamental case has real support. Synchrony's Q2 net charge-off rate improved 27bps year-over-year to 5.43%, with record purchase volume and raised full-year EPS guidance. Bread Financial cut its full-year net loss-rate guide to 7.0–7.1% with reserve rates improving 66bps year-over-year. Enova's consolidated charge-off ratio hit its lowest level since Q2 2023, and World Acceptance's annualized charge-offs improved to 18.2% from 19.2% even as its customer base shrank on tighter underwriting. This isn't isolated either — aggregate US credit-card charge-offs eased for a seventh straight quarter. Regulatory tailwinds are real too: the CFPB's late-fee rule was vacated, preserving fee income for card issuers, and the agency has offered relief for small-dollar lenders.
But the magnitudes are wildly uneven
The cohort's ~42% one-year average return is real, but it's an artifact of averaging three big winners (ENVA +140%, DAVE +85%, BFH +72%) against PGY, which is down 42.9% over the year despite recently raising FY26 guidance and diversifying ABS funding. The trailing 30 days similarly hides a split: DAVE and ENVA are still climbing while WRLD is down 15% and SEZL down 8%, even after Sezzle's own guidance raise — with analysts now flagging its valuation as stretched amid a growing state-level BNPL regulatory patchwork. Dave's own re-rating is tied partly to a funding-structure shift with Coastal Community Bank unlocking balance-sheet liquidity. Meanwhile, Fed rate cuts have already been largely priced through 2025, suggesting the funding-cost tailwind is more realized than fresh from here.