

EMS Sector Cools in Sync, But Diversified Names — Not AI Leader — Lead Declines
Hypothesis Opus 5 · Research Sonnet 5 · Writing Sonnet 5 · Prompt v1.0
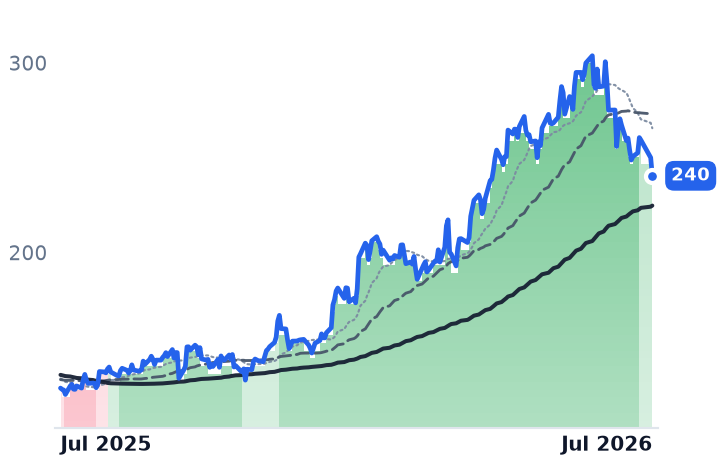
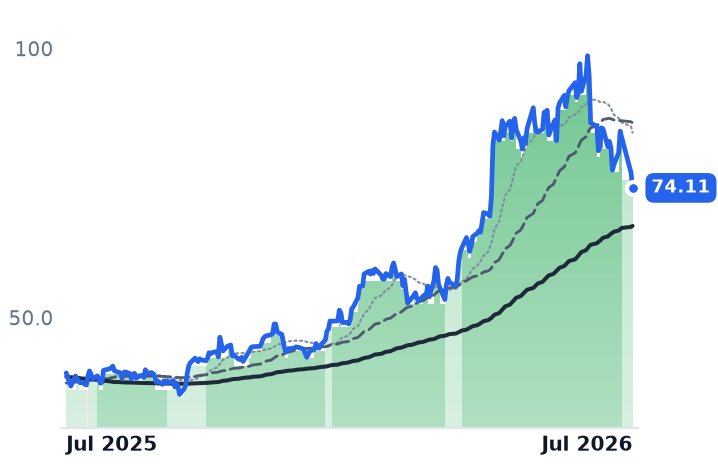
All six starred Electronic Manufacturing Services names (CLS, FLEX, JBL, SANM, PLXS, BHE) softened from strongly bullish to mildly bullish within the same ~3.5-week window in late June/July, but the sell-off was led by diversified names like SANM and FLEX, not AI-levered Celestica — and it coincided with raised, not cut, hyperscaler capex and EMS guidance.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
CLS | Celestica | Electronic Manufacturing Services | 🟢 Cont. Bull | −4.3% | +62.6% |
FLEX | Flex | Electronic Manufacturing Services | 🟢 Cont. Bull | −35.4% | +98.9% |
JBL | Jabil | Electronic Manufacturing Services | 🟢 Cont. Bull | −23.1% | +24.8% |
SANM | Sanmina | Electronic Manufacturing Services | 🟢 Cont. Bull | −31.8% | +35.7% |
PLXS | Plexus | Electronic Manufacturing Services | 🟢 Cont. Bull | −16.4% | +87.1% |
BHE | Benchmark Electronics | Electronic Manufacturing Services | 🟢 Cont. Bull | −22.0% | +86.5% |
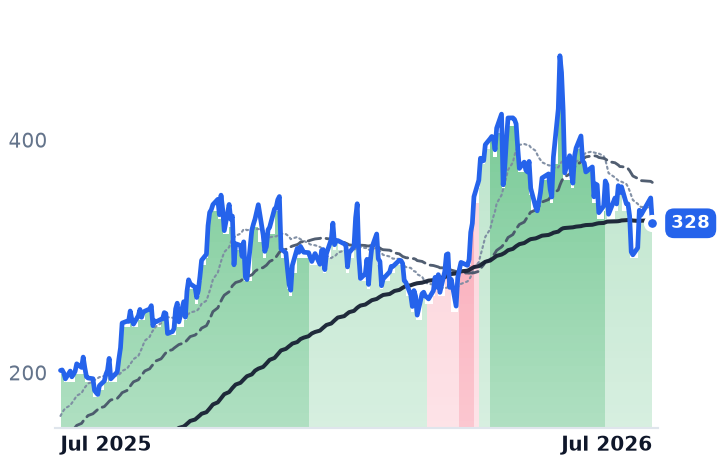
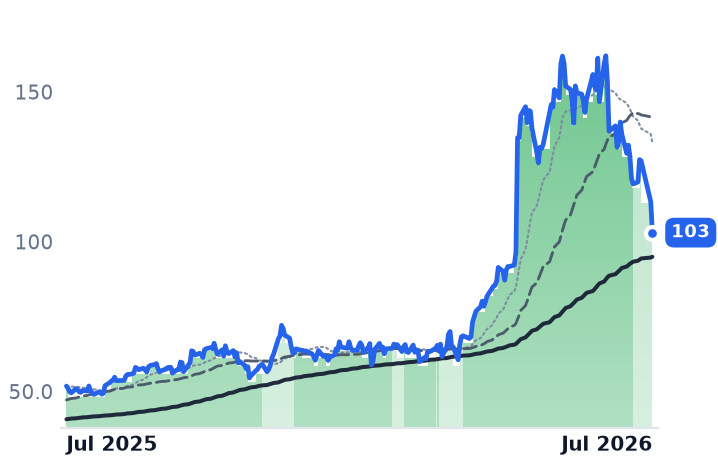
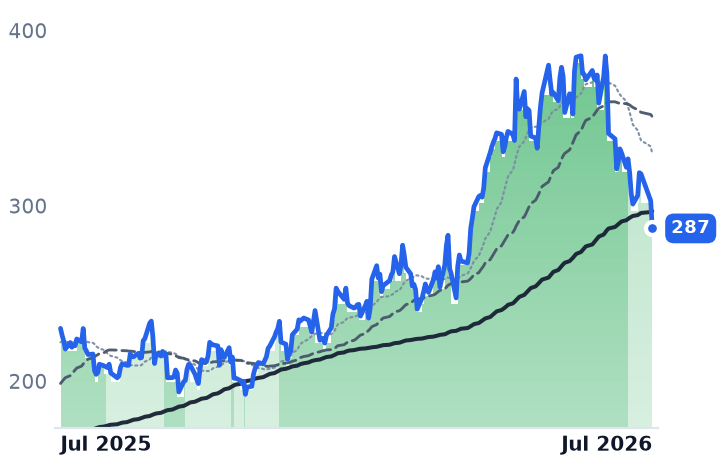
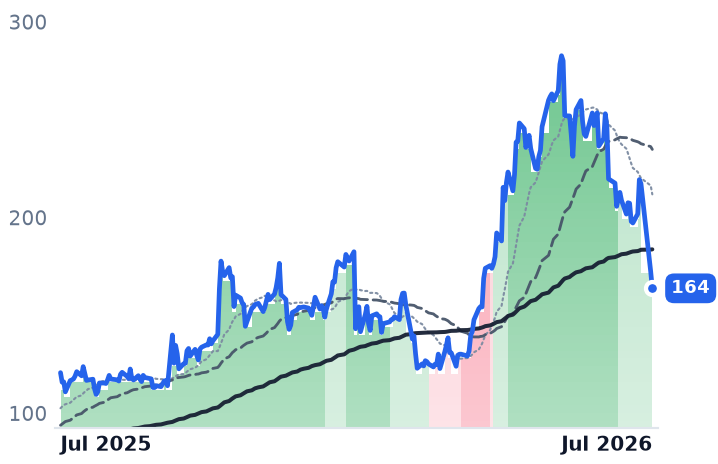
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CLS | $39.1B | 35.0x | 29.9x | 2.5x | 1.9x | 21.6x | 16.4x | 26.2x | 1.3% |
FLEX | $48.0B | 50.2x | 27.7x | 1.6x | 1.4x | 17.3x | 14.6x | 26.9x | 2.2% |
JBL | $38.8B | 45.7x | 29.0x | 1.2x | 1.1x | 12.5x | 12.0x | 19.4x | 3.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SANM | $11.6B | 38.1x | 17.9x | 0.9x | 0.8x | 10.1x | 9.1x | 18.3x | 5.1% |
PLXS | $7.3B | 39.6x | 31.9x | 1.6x | 1.5x | 15.9x | 15.0x | 29.4x | 0.8% |
BHE | $3.0B | 56.9x | 28.5x | 1.1x | 1.0x | 10.5x | 9.8x | 20.9x | 4.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CLS | Revenue | +67.0% | +69.3% | +32.3% |
| EPS | +90.2% | +74.7% | +34.3% | |
FLEX | Revenue | +6.8% | +26.3% | +30.0% |
| EPS | +24.2% | +44.7% | +51.5% | |
JBL | Revenue | +20.2% | +21.2% | +12.1% |
| EPS | +35.9% | +31.0% | +20.3% | |
SANM | Revenue | +74.9% | +15.8% | +11.8% |
| EPS | +103.4% | +15.2% | +12.7% | |
PLXS | Revenue | +20.8% | +13.8% | +9.0% |
| EPS | +19.5% | +15.6% | +12.0% | |
BHE | Revenue | +13.3% | +7.8% | — |
| EPS | +26.7% | +13.0% | — |
Forward fiscal years only. Blank means no analyst coverage for that year.
A synchronized cooling, not a bull-regime break
The trend-band data shows a genuine cross-stock cluster: CLS, SANM, JBL, FLEX, PLXS and BHE all downgraded from strongly bullish to mildly bullish between June 30 and July 22, a common ~3.5-week window across all six names. That's the kind of category-wide signal that matters — but critically, none of the six broke further into neutral or bear territory. This looks like momentum cooling inside an intact bull structure, not a regime change.
The AI leader held up best — the diversified names cratered
The more surprising finding inverts the working thesis. Over the trailing 30 days, Celestica — the name most levered to AI-server contract manufacturing — fell just 4%, the smallest decline in the cohort. Meanwhile Sanmina dropped 32%, Flex fell 30%, BHE fell 22%, Jabil fell 21%, and Plexus fell 17%. If this were a hyperscaler-demand digestion story concentrated in AI racks, CLS should have led the decline. Instead the diversified members sold off hardest.
Fundamentals argue against a demand break
Earnings released inside this same window undercut the digestion thesis further. Celestica beat Q2 estimates and raised FY2026 revenue guidance to $20.5B from $19.0B, with Q3 guidance well above consensus. Jabil raised its AI-related revenue guidance to $13.6B, up 50% year-over-year and lifted its Intelligent Infrastructure segment outlook to $17.0B. Sanmina posted 69.7% revenue growth with AI/cloud infrastructure at 62% of total revenue, and Plexus posted record revenue and raised its full-year growth and margin outlook alongside record program wins.
The real catalyst looks macro, not sector-specific
The proximate trigger appears to be Alphabet's July 22-23 report, which raised 2026 capex guidance to roughly $195-205B and turned free cash flow negative, sparking a broad repricing of AI-capex ROI and FCF-compression risk across Big Tech and its supply chain — even as aggregate 2026 hyperscaler capex guidance sits near $725B, up 77% year-over-year. A same-day sector move hit Flex, Jabil, Sanmina and adjacent electronics names together, consistent with synchronized sector selling rather than company-specific news. Flex now trades well below its average sell-side price target, per pre-earnings coverage, reinforcing that this reads more as a multiple reset than a fundamentals-driven de-rating. One real risk still building in the background: DRAM and NAND contract prices have spiked 70-95% quarter-over-quarter, a cost pressure EMS providers are absorbing via inventory buffers rather than full pass-through — a margin risk to watch, though it has not yet appeared in any guidance cut.