

Sub-Fab Semicap 'Rollover' Traces to a KLA Split Artifact and One Bad Day
Hypothesis Opus 5 · Research Sonnet 5 · Writing Sonnet 5 · Prompt v1.0
The reported 37% monthly collapse in the sub-fab/advanced-packaging-test cohort (ICHR, ACLS, VECO, FORM, COHU, MKSI, GLW, KLAC) is largely an illusion: KLA's -89% figure is a stock-split data artifact, and most of the real move came from a single synchronized selloff on 2026-07-28. Trend bands, bookings, and guidance across the cohort still point to an intact bull cycle, not a fundamentals-driven rollover.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
ICHR | Ichor | Other | 🌱 Emerging Bull | −41.0% | +196.6% |
ACLS | Axcelis Technologies | Semiconduct Equipment | 🟢 Cont. Bull | −36.4% | +53.1% |
VECO | Veeco Instruments | Semiconduct Equipment | 🟢 Cont. Bull | −38.1% | +98.6% |
FORM | FormFactor | Process Control & Metrology | 🟢 Cont. Bull | −42.1% | +140.5% |
COHU | Cohu | Semiconduct Equipment | 🟢 Cont. Bull | −42.2% | +104.2% |
MKSI | MKS | Instrumentation & Test Equipment | 🟢 Cont. Bull | −38.1% | +154.6% |
GLW | Corning | Display & Optical Materials | 🟢 Cont. Bull | −51.5% | +102.0% |
| Compared against · context, not the story | |||||
KLAC | KLA | Semiconduct Equipment | ⚠️ Emerging Bear | −38.9% | −81.3% |
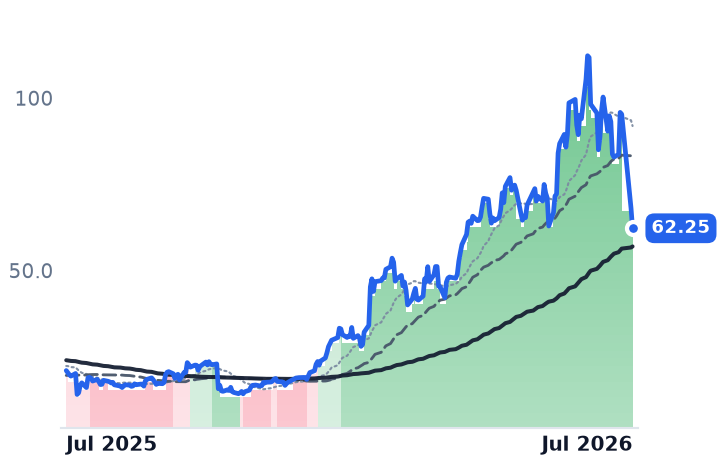
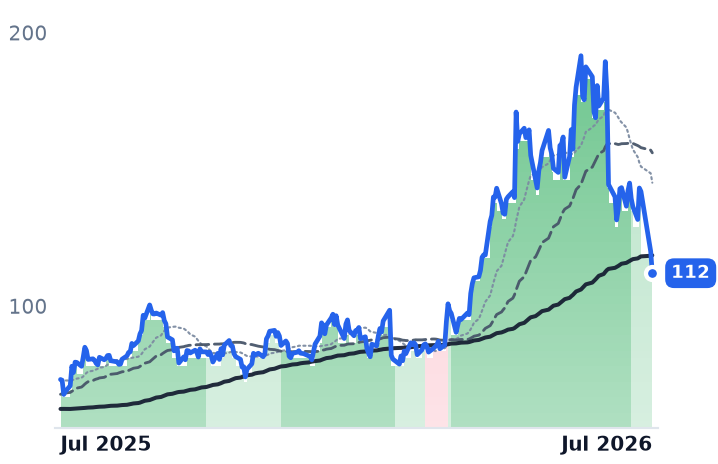
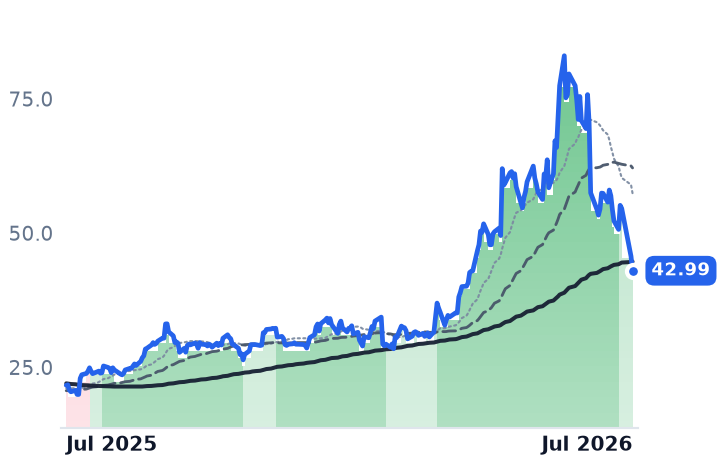
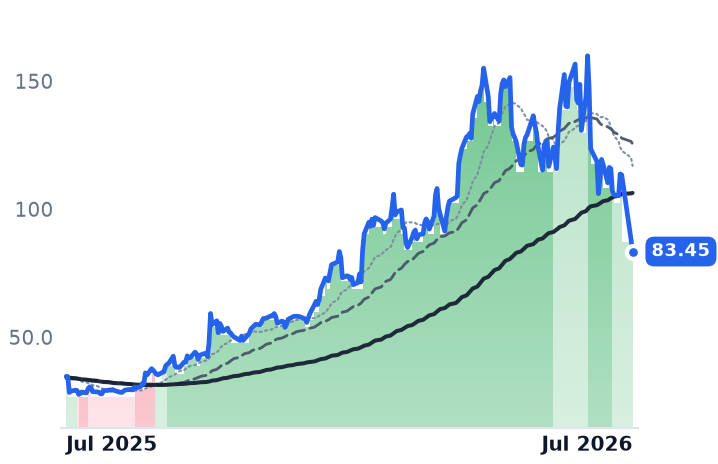
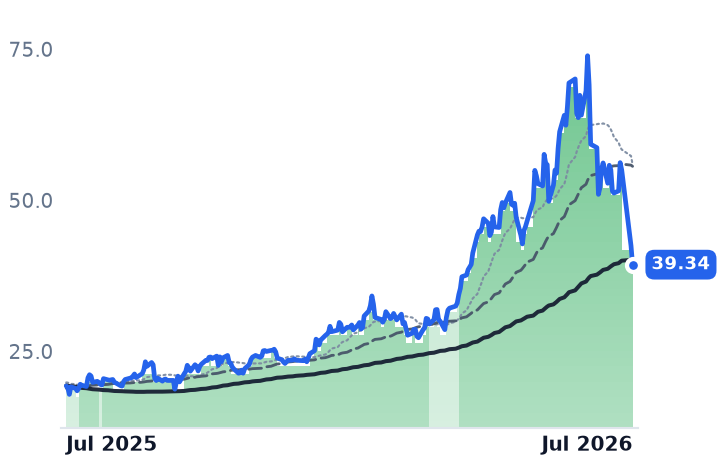
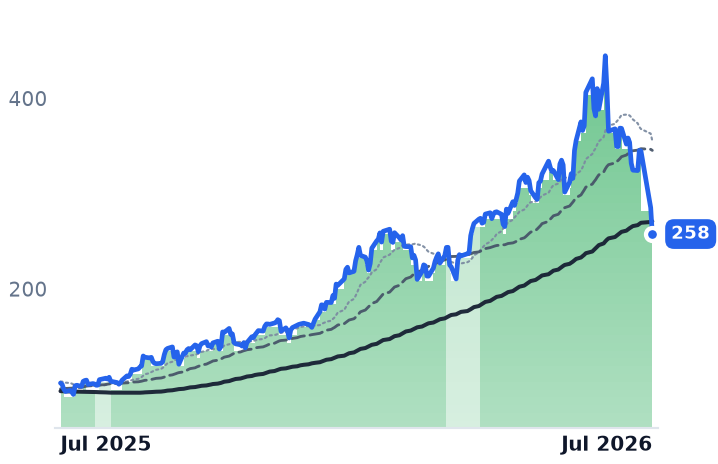
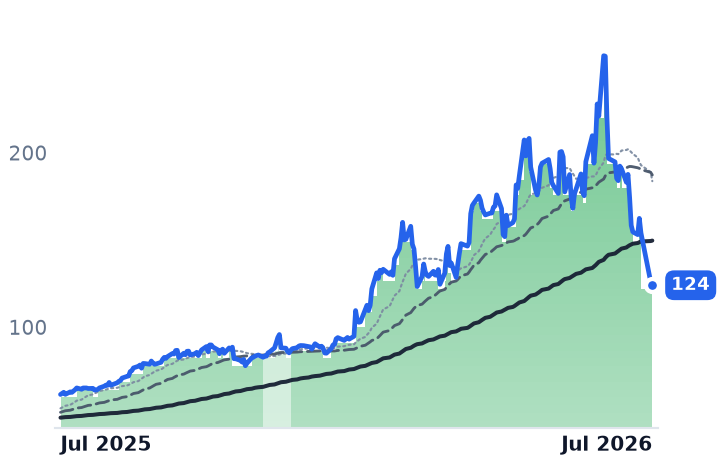
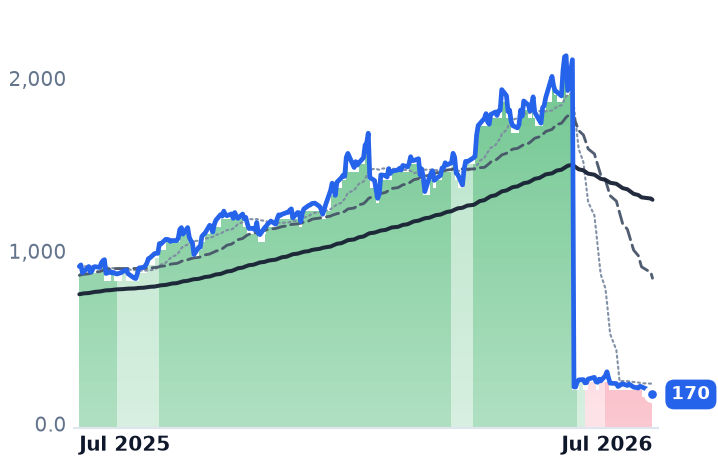
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ICHR | $2.5B | n/m | 53.1x | 2.7x | 2.1x | 28.6x | 22.9x | n/m | -0.7% |
ACLS | $4.4B | 48.0x | 37.6x | 5.1x | 5.2x | 11.9x | 12.2x | 33.8x | 1.5% |
VECO | $3.3B | 142.0x | 34.9x | 4.9x | 4.2x | 12.9x | 11.1x | 62.8x | 2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FORM | $9.8B | 143.8x | 51.5x | 11.7x | 10.2x | 27.8x | 24.3x | 64.2x | 0.4% |
COHU | $3.0B | n/m | 65.9x | 5.7x | 4.8x | 14.4x | 12.3x | 134.7x | 1.2% |
MKSI | $20.5B | 62.5x | 26.0x | 5.0x | 4.3x | 11.5x | 9.8x | 23.3x | 2.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GLW | $137.7B | 72.4x | 48.9x | 8.1x | 7.2x | 22.4x | 19.7x | 37.1x | 1.7% |
KLAC | $268.8B | 55.9x | 37.5x | 19.8x | 14.8x | 32.3x | 24.2x | 47.4x | 1.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ICHR | Revenue | +26.7% | +20.3% | +0.5% |
| EPS | +709.3% | +95.8% | −60.0% | |
ACLS | Revenue | +3.5% | +9.6% | +20.0% |
| EPS | −14.8% | +26.4% | +41.7% | |
VECO | Revenue | +18.6% | +35.6% | — |
| EPS | +17.4% | +101.8% | — | |
FORM | Revenue | +23.5% | +15.3% | −0.4% |
| EPS | +117.3% | +24.7% | −5.6% | |
COHU | Revenue | +35.3% | +25.7% | +15.3% |
| EPS | +131844.4% | +94.3% | +38.4% | |
MKSI | Revenue | +22.3% | +14.0% | +8.9% |
| EPS | +48.1% | +26.2% | +13.2% | |
GLW | Revenue | +17.5% | +18.7% | +21.0% |
| EPS | +29.6% | +31.7% | +36.5% | |
KLAC | Revenue | +12.2% | +33.9% | +19.0% |
| EPS | +14.5% | +47.8% | +21.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The bands never actually broke
Across the seven-plus-KLAC sub-fab and advanced-packaging-test cohort, trend-band history tells a very different story than the headline drawdown suggests. Ichor Holdings held a strongly bullish band continuously straight through the 2026-07-28 crash session, even after a roughly 29% single-day drop in its shares that day. MKS Instruments has held strongly bullish without a single break since January 2, 2026. Cohu and Corning also stayed in strongly bullish bands through the crash date. Axcelis, FormFactor and Veeco only softened to mildly bullish in mid-to-late July — none crossed into neutral or bear territory. The one genuine bull-to-bear band break in the group is KLA, which flipped to strongly bearish on June 29 and has stayed there.
KLA's -89% is a data artifact, not a decline
That KLA break is misleading. KLA's board approved a ten-for-one forward stock split announced May 7, 2026, with shares trading split-adjusted from June 12 — the same announcement included a 21% dividend increase. The raw price series shows a mechanical ~90% drop from roughly $2,108 to $214 on the split date, which corrupted an SMA-crossover trend signal into a false "strongly bearish" read. Split-adjusted, KLA's actual decline into July 28 is roughly in line with cohort peers, not the reported -89%.
What really moved the cohort
The dominant driver of the 30-day drawdown is a single synchronized session: all eight names fell together on 2026-07-28, with declines ranging from roughly -11% (KLAC) to -29% (ICHR). That selloff traces to reports that a Chinese state-backed firm has begun mass-producing immersion DUV lithography tools competing with ASML, layered on top of mounting AI-infrastructure-debt anxiety tied to Nvidia's roughly $750 billion in AI deals — pressure that pulled the Philly Semiconductor Index down as much as 6.5% intraday. The move was broad and sector-wide, hitting SK Hynix, Samsung and Softbank alongside the semicap names. Corning's own ~18-19% drop that day was separately earnings-driven: a Q2 beat paired with soft Q3 guidance tied to memory-price headwinds.
Fundamentals show no crack
Underlying demand signals remain unchanged. SEMI still projects record 2026 WFE spending near $135 billion, up roughly 9% year over year. MKS guided semiconductor revenue up more than 25% year over year on strong bookings. FormFactor's HBM probe-card business grew over 50% year over year on HBM4 ramp. Ichor's Q1 beat carried a Q2 guide of $290-310M, implying continued sequential growth, with its next print due August 3, 2026. Prior internal analysis in May had already flagged ICHR and FORM as valuation-extended on momentum, not fundamentally deteriorating — a framing this evidence pack still supports.