

The wafer layer already re-rated — GlobalWafers is late-cycle, not early
Prompt v1.0
GlobalWafers is up 117% in 90 days and 272% in a year, and the whole wafer/substrate cohort moved with it — but the stock now trades ~33% above its entire 2020-25 cycle high and ~21% above the 13-analyst consensus target, while 1H26 revenue is still down 7.6% YoY. The ASP-hike story is real; the equity has already priced several years of it.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
6488.TWO | GlobalWafers | Semiconductors | 🟢 Cont. Bull | +4.8% | +175.3% |
3436.T | Sumco | Semiconductors | 🟢 Cont. Bull | −18.2% | +154.9% |
4063.T | Shin-Etsu Chemical | Chemicals | 🟢 Cont. Bull | −15.4% | +33.7% |
WAF.DE | Siltronic | Semiconductors | 🟢 Cont. Bull | −10.4% | +63.4% |
3037.TW | Unimicron Technology | Hardware, Equipment & Parts | 🟢 Cont. Bull | −21.6% | +474.4% |
8046.TW | Nan Ya Printed Circuit Board | Hardware, Equipment & Parts | 🟢 Cont. Bull | −9.6% | +429.0% |
3189.TW | Kinsus Interconnect Technology | Semiconductors | 🟢 Cont. Bull | −21.0% | +539.0% |
AXTI | AXT | Fabrication Equipment & Materials | 🟢 Cont. Bull | −40.2% | +1652.5% |
MU | Micron Technology | Memory & Storage | 🟢 Cont. Bull | −28.3% | +638.6% |
TSM | Taiwan Semiconductor Manufacturing | Foundries | 🟢 Cont. Bull | −13.8% | +63.0% |
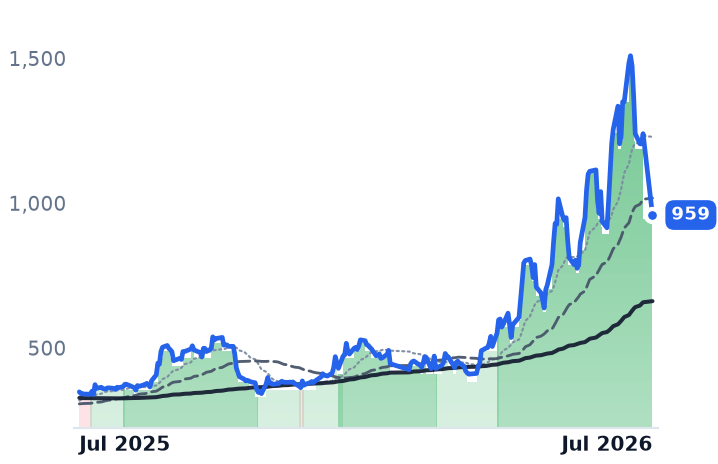
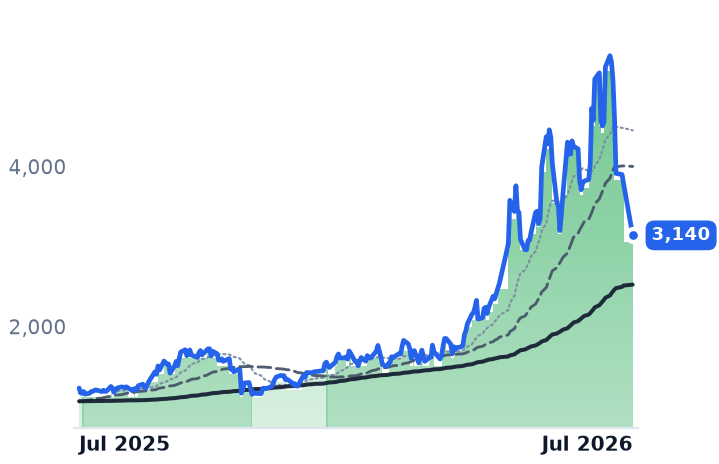
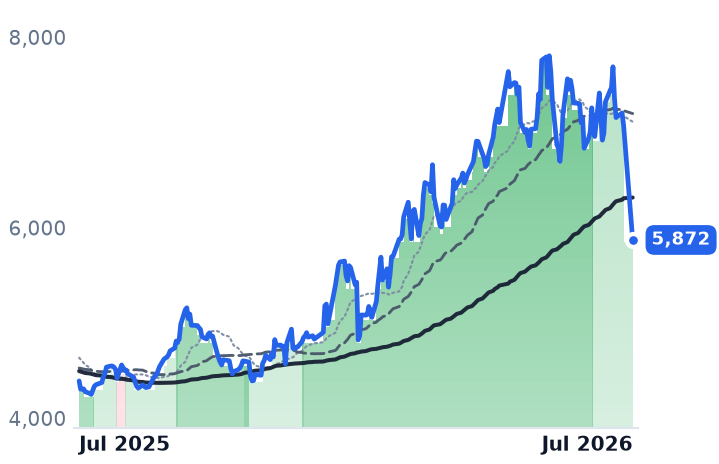
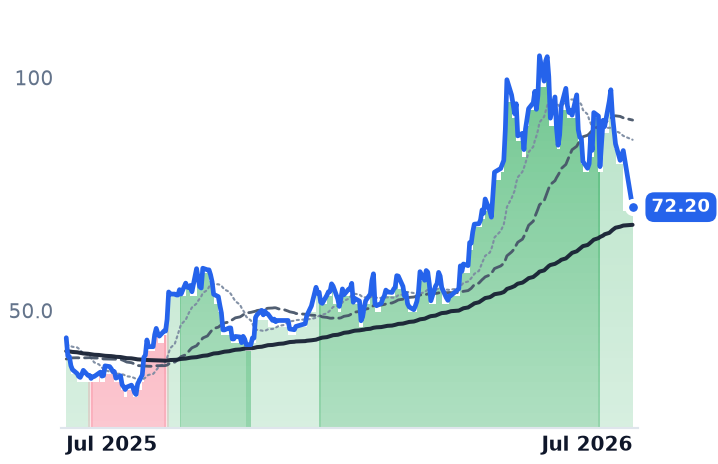
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
6488.TWO | $379.1B | 48.9x | 38.7x | 6.4x | 5.9x | 28.4x | 25.9x | 26.4x | -5.5% |
3436.T | $1.2T | n/m | — | 2.8x | 2.8x | 21.3x | 20.8x | 15.7x | 0.0% |
4063.T | $13.9T | 29.3x | 25.1x | 5.4x | 5.0x | 15.8x | 14.7x | 13.2x | 2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WAF.DE | $2.7B | n/m | — | 2.0x | 2.1x | 88.0x | 89.1x | 13.5x | -5.9% |
3037.TW | $1.8T | 73.0x | 57.6x | 12.0x | 9.6x | 65.3x | 52.3x | 47.2x | -0.3% |
8046.TW | $762.5B | 138.7x | 76.0x | 16.3x | 13.1x | 100.8x | 81.1x | 55.6x | 0.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
3189.TW | $447.4B | 144.9x | 79.8x | 10.0x | 8.3x | 45.0x | 37.4x | 35.7x | 0.8% |
AXTI | $3.6B | — | 82.6x | 28.6x | 16.5x | 88.9x | 51.2x | 223.3x | -0.5% |
MU | $1.0T | 19.9x | 12.2x | 11.2x | 7.8x | 15.4x | 10.7x | 14.5x | 2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TSM | $2.2T | 27.9x | — | 14.1x | — | 21.9x | — | 18.5x | 1.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
6488.TWO | Revenue | +6.0% | +19.5% | +13.8% |
| EPS | +34.7% | +35.8% | +32.9% | |
3436.T | Revenue | +3.5% | +7.6% | +5.6% |
| EPS | +32.2% | −219.7% | +93.5% | |
4063.T | Revenue | +0.2% | +7.7% | +5.9% |
| EPS | −6.5% | +14.0% | +12.7% | |
WAF.DE | Revenue | −3.3% | +11.3% | +11.3% |
| EPS | +227.5% | −34.2% | −59.6% | |
3037.TW | Revenue | +41.6% | +48.7% | +34.8% |
| EPS | +453.6% | +93.3% | +69.4% | |
8046.TW | Revenue | +45.4% | +61.4% | +50.9% |
| EPS | +486.0% | +158.2% | +88.2% | |
3189.TW | Revenue | +37.0% | +45.9% | +51.2% |
| EPS | +230.3% | +136.2% | +110.5% | |
AXTI | Revenue | +140.9% | +111.3% | +47.0% |
| EPS | −306.1% | +158.9% | +48.5% | |
MU | Revenue | +248.0% | +92.8% | +11.4% |
| EPS | +804.9% | +111.2% | +7.9% | |
TSM | Revenue | +42.0% | +34.4% | +26.0% |
| EPS | +65.5% | +30.7% | +26.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The premise is stale
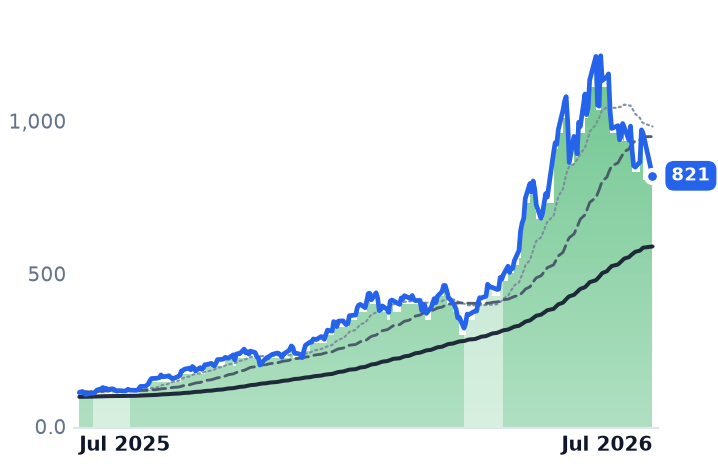
GlobalWafers (6488.TWO) is not in a quiet month-long grind higher. It peaked at TWD 1,515 on 14 July and fell 18.2% in the six sessions to 22 July on heavy volume (6.7m–12.6m shares), closing at TWD 1,240. That leaves it +11% over 30 days but +117% over 90 days, +135% over 180 days and +272% over twelve months. The move happened; it happened in the spring, not the last four weeks.
Breadth exists — pointing the other way
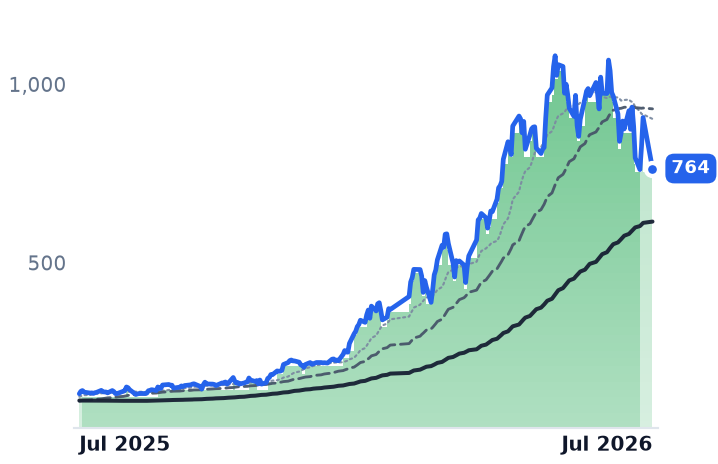
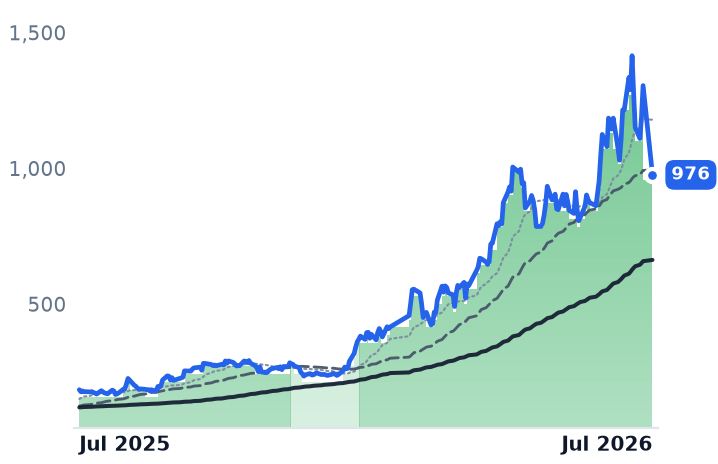
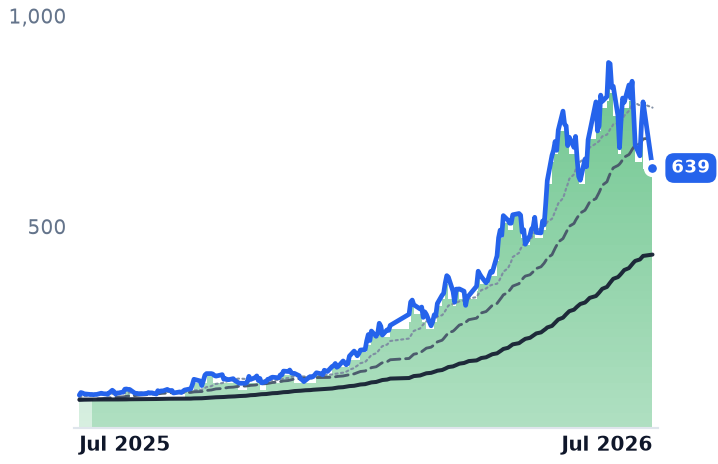
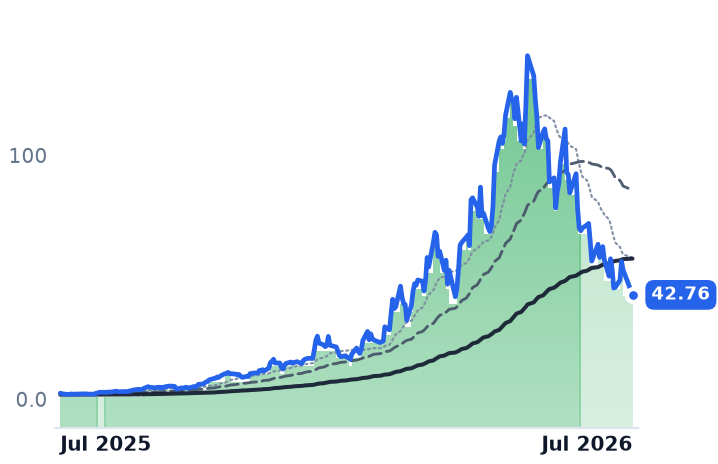
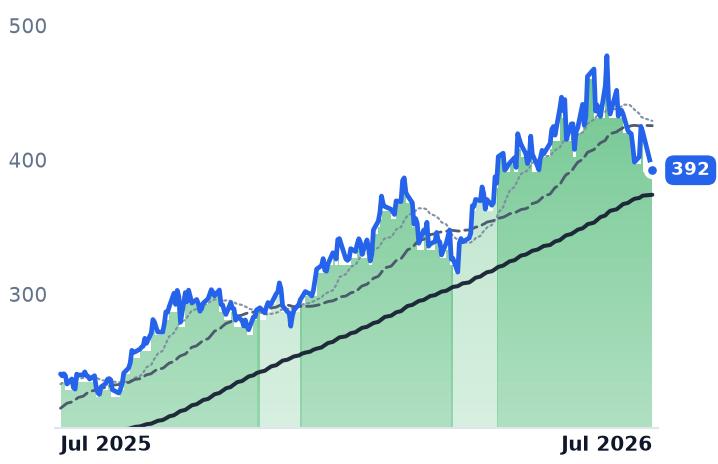
The cohort re-rated in unison over 90 days: SUMCO +75%, Kinsus +66%, Nan Ya PCB +64%, Unimicron +25%, Siltronic +19%, Shin-Etsu +6%. It is now correcting in unison — every name sits in a drawdown from a Q2/Q3-2026 peak (AXT −62%, SUMCO −30%, Micron −21%, Siltronic −19%). Trend bands show extension, not exit-from-bear: 6488.TWO, SUMCO, Nan Ya PCB, Micron and TSMC all read strongly bullish, while Unimicron, Shin-Etsu and AXT have already been downgraded to mildly bullish. The July leg is sector-wide — Taiwan stocks fell into a technical correction after TSMC's results stoked spending and margin worries, with the SOX closing more than 20% below its late-June high.
Cycle position inverts the thesis
The hypothesis wants names still below prior-cycle highs. GlobalWafers' best close across 2020-2025 was TWD 935 — it now trades ~33% above that. SUMCO is +33% above, Nan Ya PCB +108%, Unimicron +257%. Only Siltronic remains ~5% below. The 13-analyst consensus target of TWD 1,021 implies roughly 18% downside, with 3 sells against 8 buys.
The fundamentals are real but lag badly
All three Taiwanese suppliers have signalled further H2-2026 price increases, building on TrendForce's January call that 8-inch prices would rise 20%. GlobalWafers says 12-inch lines are fully loaded with Asia capacity booked, though chairwoman Doris Hsu framed the push as cost-driven, not demand-driven. Memory capex is genuinely routing upstream: Micron committed up to $500m plus a 10-year supply agreement to the Sherman, Texas fab, inside a plan to lift US spending to $250bn. SEMI logged Q1 wafer shipments +13.1% YoY but −4.7% QoQ and called the recovery "not uniform."
The P&L agrees. Q1 2026 revenue fell 10.3% YoY at a 20.8% gross margin with operating income −43%; Q2 revenue was −4.96% YoY and 1H26 −7.6%. Annual operating margin has slid from 29.3% (2022) to 14.3% (2025). Siltronic still guides FY2026 sales below 2025, and SUMCO missed Q1 and guides a ~2% operating margin with long-term contract prices merely maintained. At TWD 1,240 that is ~76x trailing and ~60x FY26 consensus EPS.