

Rare-earth equities de-rate while NdPr prices hit 2026 highs
Prompt v1.0
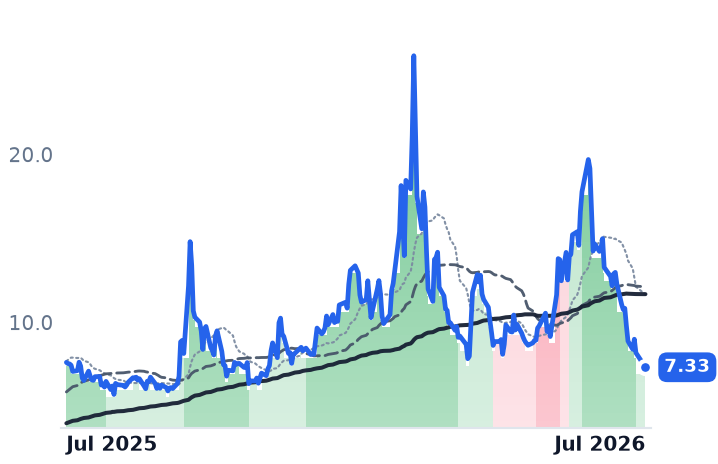
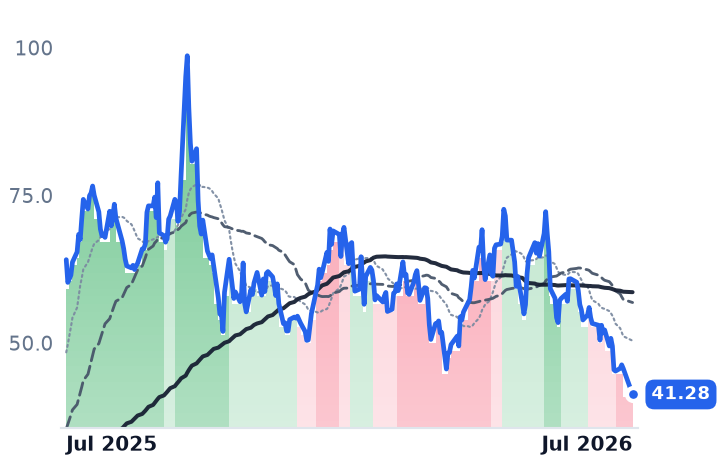
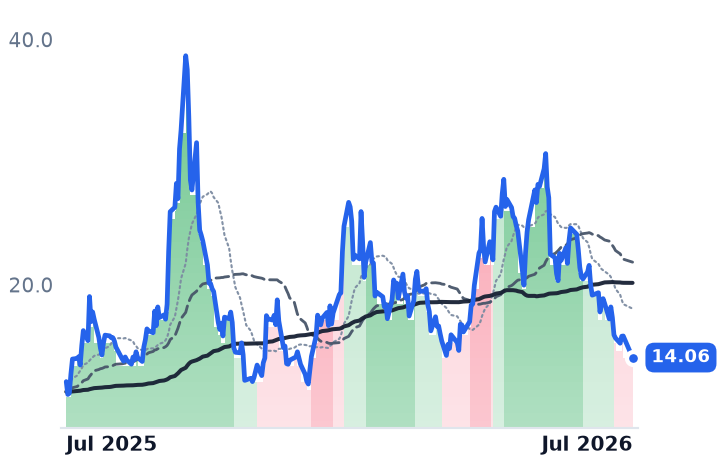
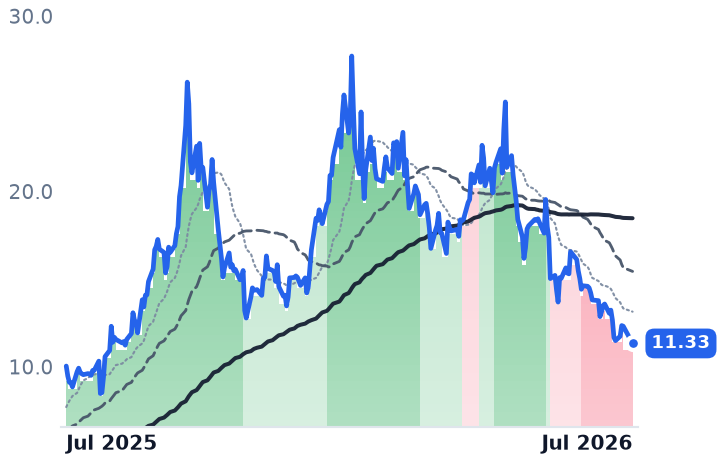
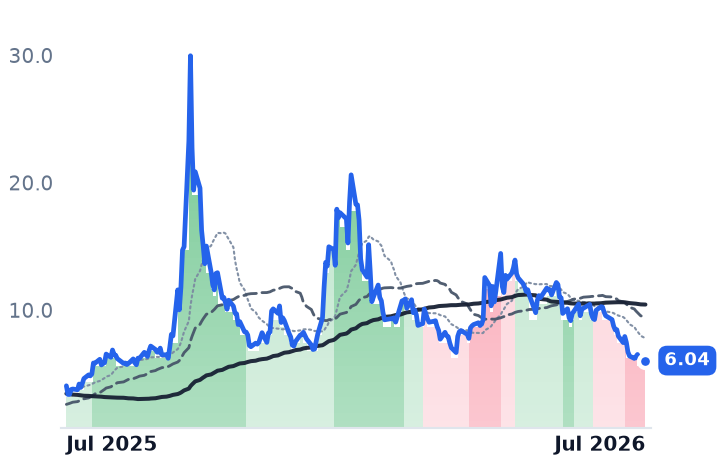
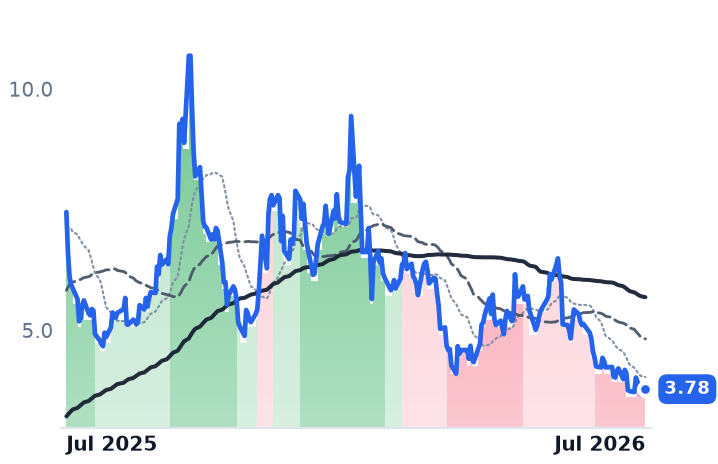
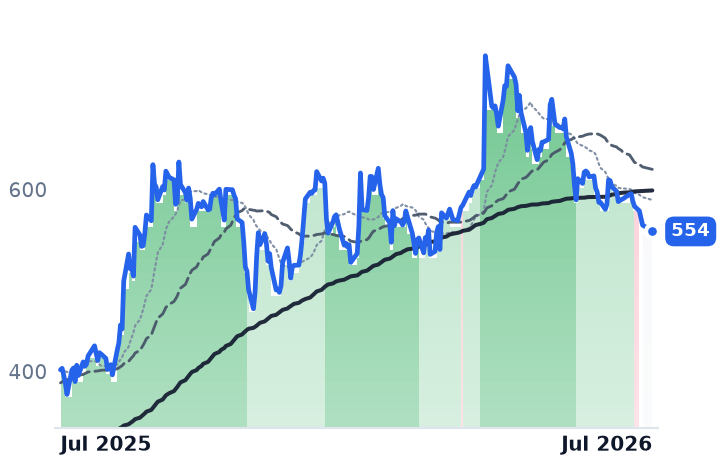
MP, USAR, UUUU and micro-cap REalloys (ALOY) have all rolled out of bull bands into bear territory over the past 30 days, with the cohort now 54-68% below 52-week highs. The unusual part: rare-earth prices are at 2026 highs, so this is multiple compression dated to China's 22 June export-control blacklist, not a deflating scarcity premium.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
ALOY | REalloys | Rare Earth Elements | ⚠️ Emerging Bear | −48.5% | −3.8% |
MP | MP Materials | Rare Earth & Magnets | ⚠️ Emerging Bear | −24.6% | −35.6% |
USAR | USA Rare Earth | Rare Earth & Magnets | 🟢 Cont. Bull | −33.2% | +16.2% |
UUUU | Energy Fuels | Uranium | ⚠️ Emerging Bear | −22.3% | +12.8% |
CRML | Critical Metals | Battery & Energy Transition Materials | ⚠️ Emerging Bear | — | — |
TMC | TMC the metals | Deep-Sea & Alternative Sources | ⚠️ Emerging Bear | — | — |
GMDCLTD.BO | Gujarat Mineral Development | Coal | 🟢 Cont. Bull | −4.2% | +37.8% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ALOY | $945.3M | n/m | — | 333.4x | 269.2x | 575.0x | 464.3x | n/m | -2.9% |
MP | $10.5B | n/m | 522.6x | 34.2x | 23.4x | — | — | 177.5x | -4.8% |
USAR | $2.6B | n/m | — | 194.4x | 32.3x | — | — | n/m | -9.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
UUUU | $3.7B | n/m | — | 35.0x | 25.0x | 80.8x | 57.9x | n/m | -3.0% |
CRML | $1.0B | n/m | — | — | — | — | — | n/m | -1.3% |
TMC | $2.3B | n/m | — | n/m | 6.9x | — | — | n/m | -1.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GMDCLTD.BO | $211.1B | 21.3x | 29.0x | 8.0x | 5.9x | 21.8x | 16.1x | 15.1x | 0.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ALOY | Revenue | +133.2% | +822.1% | +213.4% |
| EPS | −13.2% | −90.4% | −144.2% | |
MP | Revenue | +90.7% | +75.5% | +24.3% |
| EPS | −129.5% | +723.3% | +57.6% | |
USAR | Revenue | +980.4% | +592.8% | +163.6% |
| EPS | −75.2% | −59.4% | −249.2% | |
UUUU | Revenue | +152.8% | +63.3% | +59.0% |
| EPS | −52.3% | −188.4% | +252.4% | |
CRML | Revenue | +26.4% | +511.3% | +2684.6% |
| EPS | +806.7% | −62.5% | −217.6% | |
TMC | Revenue | −67.5% | −61.6% | +348.3% |
| EPS | −71.5% | −25.4% | −305.1% | |
GMDCLTD.BO | Revenue | −6.7% | +32.1% | +20.4% |
| EPS | +1.4% | +9.0% | +22.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
A cohort-wide band flip, not a single-name story
As of 22 July 2026 the rare-earth and magnet complex has rolled over together. MP Materials closed at $45.68, down 24.2% over 30 days and 27.9% over 90, sitting 53.7% below its $98.65 52-week high and 24.4% under its 200-day average — its trend band has gone from mildly bullish to strongly bearish in a month. USA Rare Earth is at $15.82, -34.4% over 30 days, 59.1% off its high, flipping from strongly bullish to mildly bearish. Energy Fuels is at $12.31, -23.6% over 30 days and -43.8% over 90, now strongly bearish after a strongly bullish reading 60 days ago. Even Gujarat Mineral Development, the mildest decliner at -8.8%, has faded to neutral. Local coverage for CRML and TMC stops at 19 May, so those two can't confirm the current leg.
ALOY — REalloys, the Hoidas Lake and Euclid, Ohio heavy-rare-earth metallization micro-cap this desk only recently established is not a content-licensing name — is the amplified version: -58.4% in a month, across 46 gapless daily closes from $19.70 with no reverse-split discontinuity. That rules out a corporate-action artifact. Its idiosyncratic overhang is a $50m offering of 2.7m shares priced at $18.50 on 6 March, now roughly 58% underwater, and a 7 July non-binding LOI with JS Link on an integrated North American magnet platform that failed to arrest the slide.
The commodity is going the other way
The intuitive explanation — the geopolitical scarcity premium deflating — is contradicted. NdPr rallied above the $110/kg Pentagon price floor granted to MP, and by 1 July the alloy benchmark reached roughly $133/kg, a new 2026 high with terbium oxide up about 30%. Beijing's general-licence regime begun in December 2025 supplements rather than replaces the April 2025 controls.
The dated catalyst is instead 22 June, when China blacklisted MP Materials and USA Rare Earth on its dual-use export-control list — part of curbs on dozens of US firms retaliating for the Pentagon 1260H list — the exact date the slides began. Estimates followed: Roth cut USAR's target from $40 to $30, Needham from $39 to $33, and FY26 consensus revenue from $89.2m to $72.8m, with USAR below all major EMAs alongside a 20 July CEO transition and an SVRE merger vote. MP's decline was compounded by over 1.2m shares of insider selling.
Why it matters
This is equity multiple compression against a rising commodity, not a demand signal. USAR still carries roughly 682x sales on a $5.0B market cap and ALOY about 597x on $899m, versus GMDCLTD at 7.0x sales. Western capital keeps arriving into the de-rate — a $725m DoD loan commitment to Energy Fuels, plus Commerce's $1.6bn letter of intent with USAR — while the truce suspending China's metals export controls runs only to 27 November 2026, leaving a dated re-escalation risk inside four months. The desk's own May notes rated UUUU a medium-conviction buy on a strongly bullish flip and USAR a watch-list name on extreme P/S and dilution; the July band readings have inverted the first and vindicated the caution in the second.