

Crude names aren't de-rating — they're bleeding out a war premium
Prompt v1.0
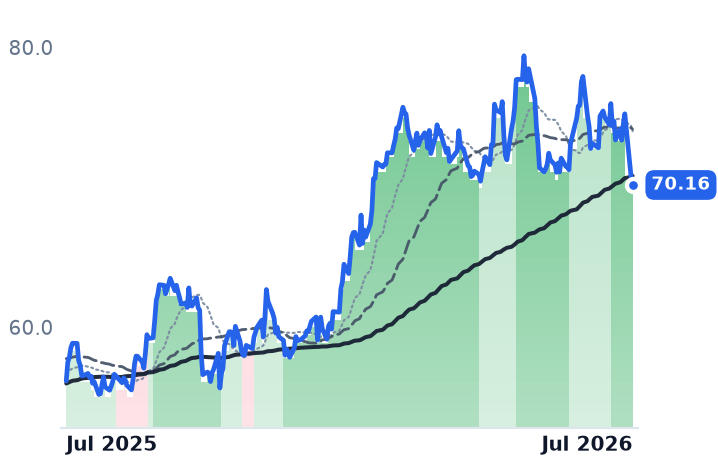
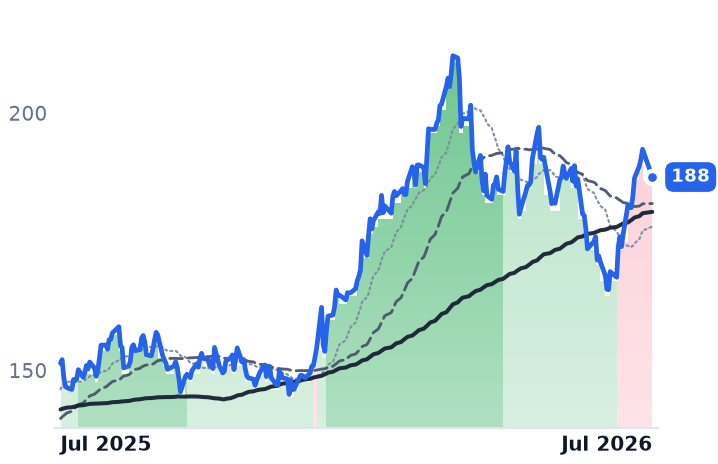
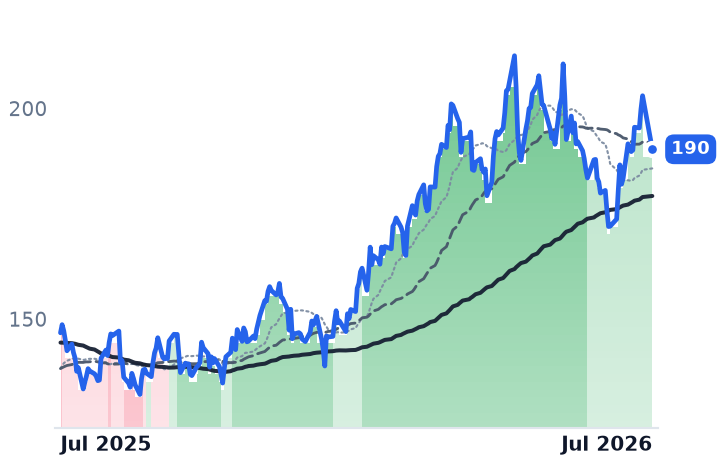
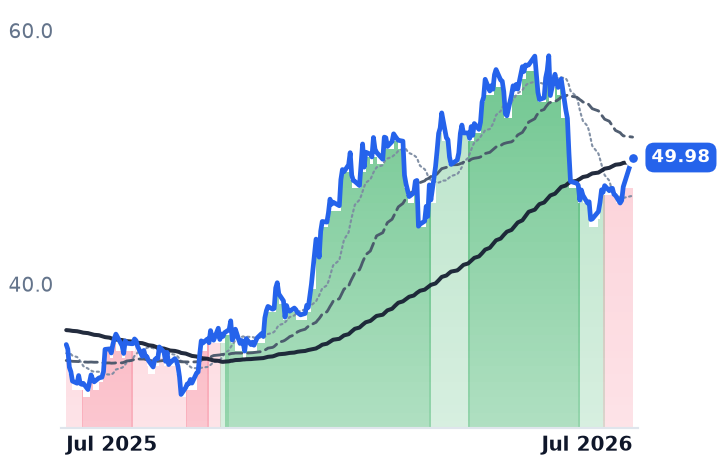
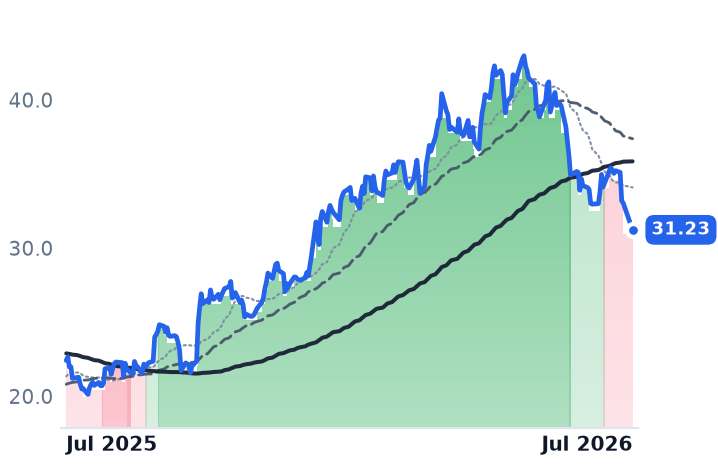
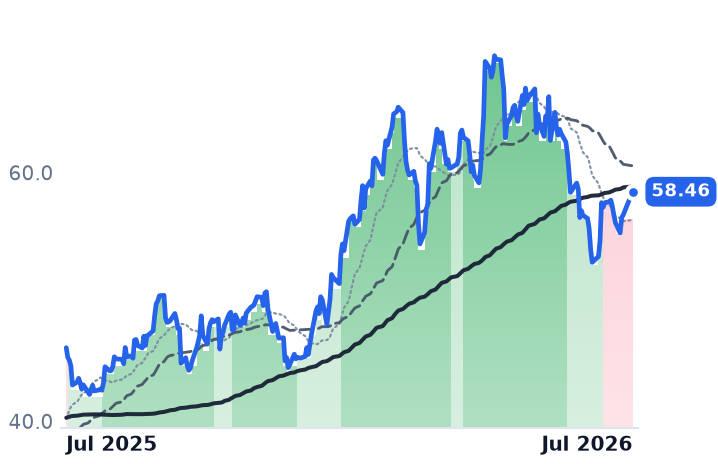
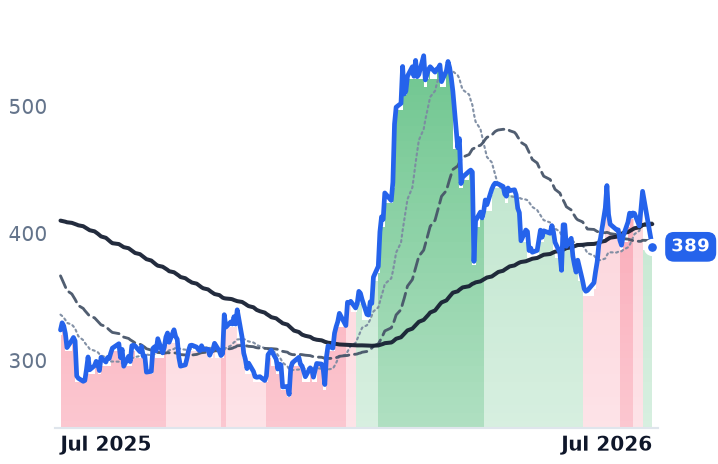
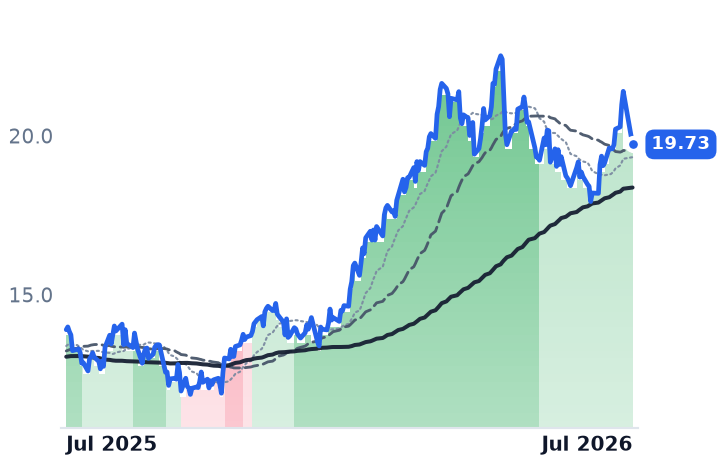
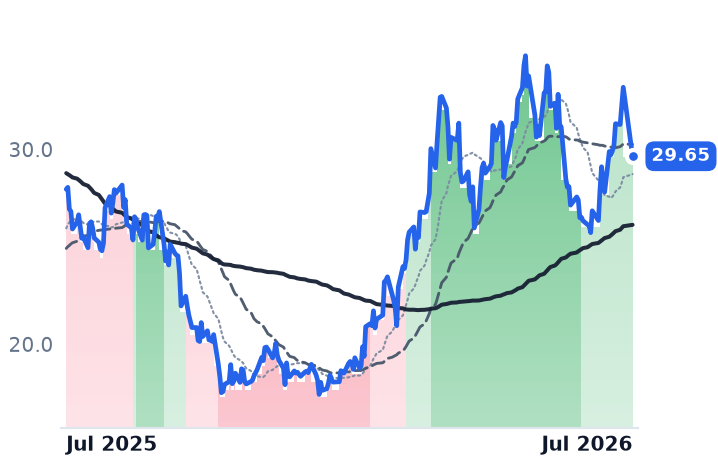
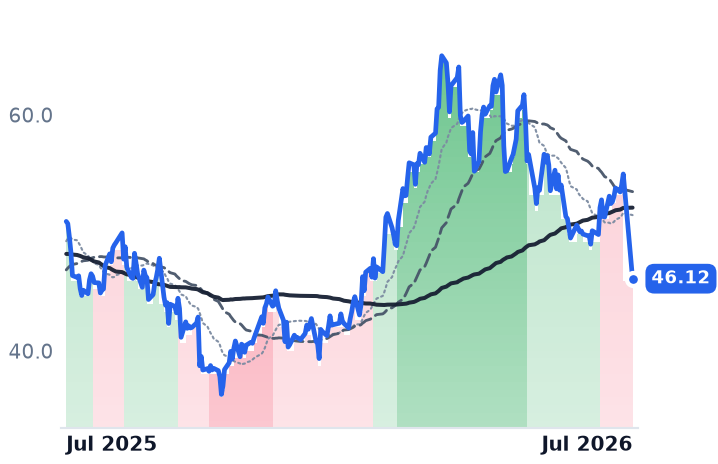
The oil-levered cohort didn't roll over: SHEL, CVX, FANG, ARX.TO and the Permian names are all up double digits or holding bull bands over 30 days, and the "five-session weakness" is one session — 27 July, when Brent fell 8.7% on US-Iran talks. The confirmed 90-day breakdown sits in oilfield services and Appalachian gas, while the forecast surplus that would actually de-rate crude producers is still ahead of them.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
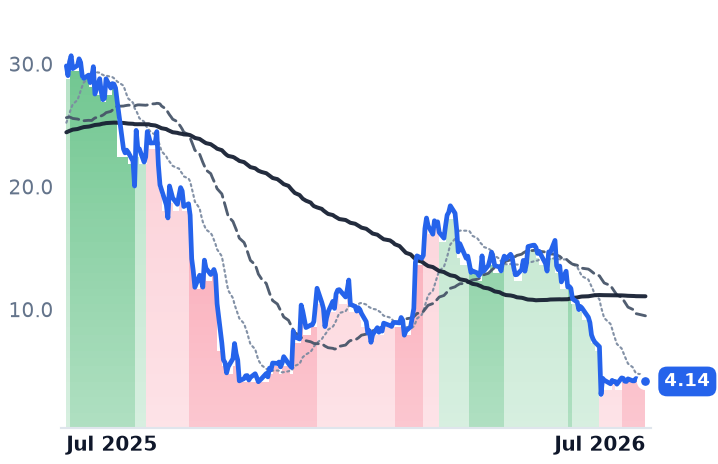
SOC | Sable Offshore | E&P Operator | 🔴 Cont. Bear | −40.6% | −86.1% |
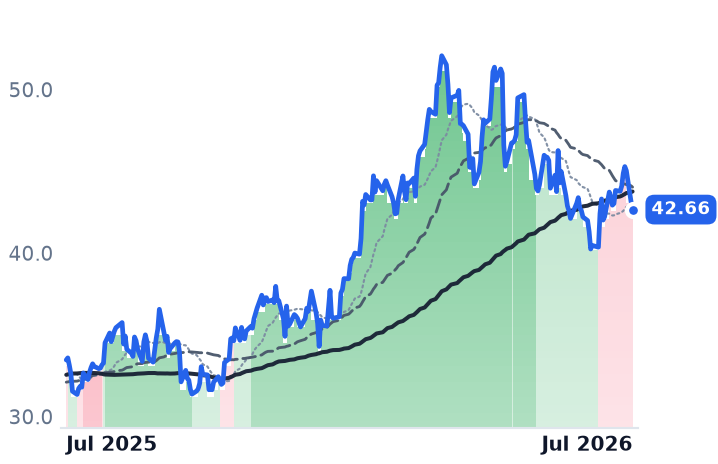
DVN | Devon Energy | Large Integrated Producers | 🟢 Cont. Bull | +1.6% | +27.5% |
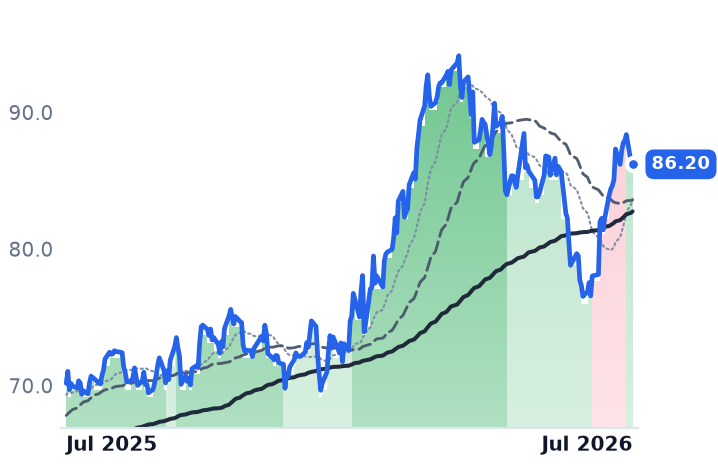
SHEL | Shell | Low Carbon Integrated | 🟢 Cont. Bull | +12.1% | +22.8% |
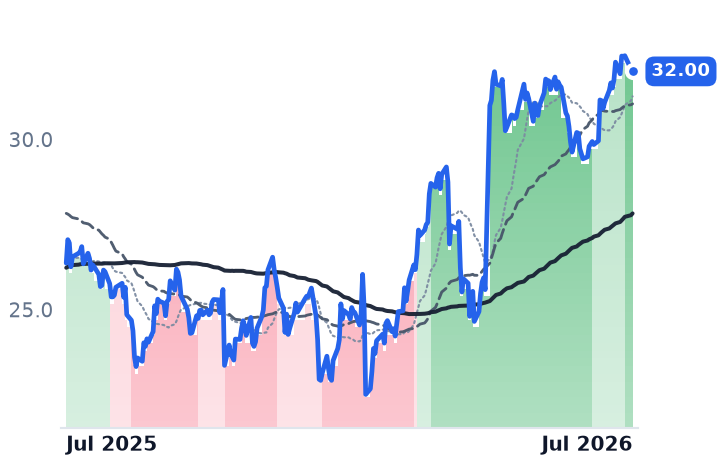
ARX.TO | ARX.TO | — | 🟢 Cont. Bull | +8.5% | +21.4% |
WMB | The Williams Companies | Diversified Midstream | 🟢 Cont. Bull | −6.5% | +24.9% |
CVX | Chevron | Conventional Majors | 🟢 Cont. Bull | +11.3% | +23.9% |
FANG | Diamondback Energy | Permian Basin | 🟢 Cont. Bull | +5.4% | +29.7% |
SLB | Slb | Integrated Oilfield Services | 🟢 Cont. Bull | +7.8% | +41.9% |
HAL | Halliburton | Integrated Oilfield Services | 🟢 Cont. Bull | −8.4% | +39.3% |
BKR | Baker Hughes | Integrated Oilfield Services | 🟢 Cont. Bull | +3.8% | +27.3% |
TPL | Texas Pacific Land | Mineral & Royalty Interests | 🌱 Emerging Bull | −7.3% | +20.2% |
PR | Permian Resources | Permian Basin | 🟢 Cont. Bull | +6.8% | +42.0% |
SM | SM Energy | Permian Basin | 🟢 Cont. Bull | +13.4% | +6.1% |
MTDR | Matador Resources | Permian Basin | 🌱 Emerging Bull | −7.3% | −9.5% |
EQT | EQT | Appalachian Shale | ⚠️ Emerging Bear | −0.7% | +0.4% |
AR | Antero Resources | Appalachian Shale | 🔴 Cont. Bear | −1.6% | +3.8% |
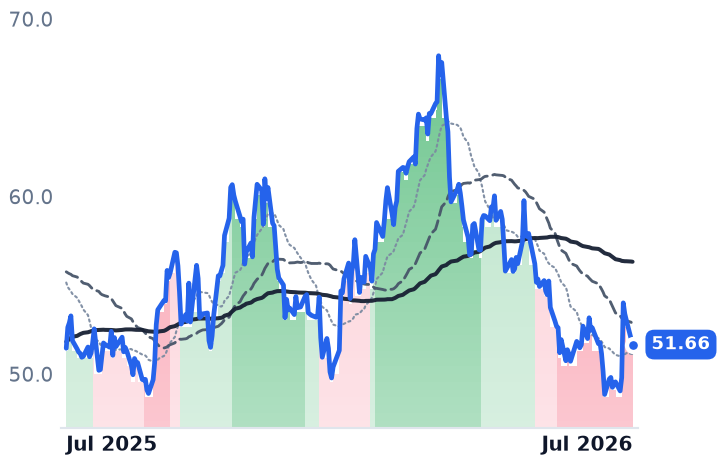
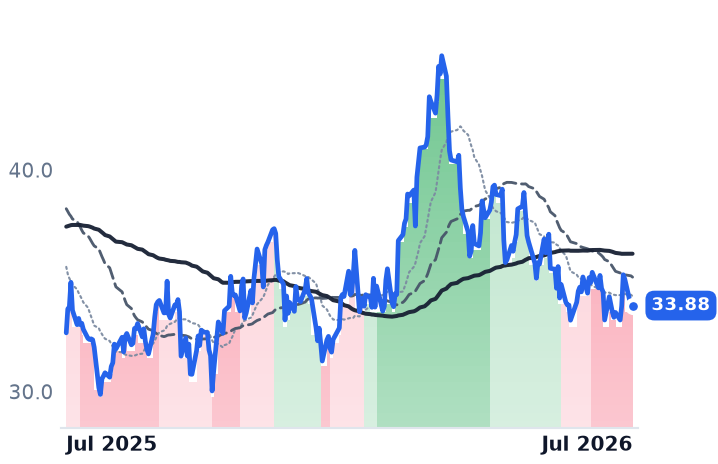
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SOC | $644.7M | n/m | — | 4.7x | 1.2x | — | — | n/m | -86.7% |
DVN | $54.9B | 11.8x | 9.4x | 2.8x | 2.2x | 8.2x | 6.4x | 7.4x | 3.0% |
SHEL | $288.8B | 11.3x | 8.5x | 1.0x | 0.8x | 5.4x | 4.7x | 4.9x | 10.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ARX.TO | — | — | — | — | — | — | — | — | — |
WMB | $88.9B | 28.8x | 29.6x | 7.3x | 7.2x | 9.9x | 9.8x | 15.5x | -0.2% |
CVX | $438.9B | 21.2x | 13.2x | 2.1x | 1.8x | 6.8x | 5.8x | 8.4x | 6.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FANG | $55.3B | 38.6x | 9.2x | 3.2x | 2.9x | 7.3x | 6.6x | 9.5x | 11.7% |
SLB | $75.9B | 24.6x | 20.6x | 2.1x | 2.1x | 12.6x | 12.4x | 12.0x | 6.0% |
HAL | $27.3B | 17.1x | 14.0x | 1.2x | 1.2x | 8.1x | 8.1x | 8.1x | 6.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BKR | $62.0B | 19.9x | 23.7x | 2.2x | 2.2x | 9.5x | 9.4x | 13.2x | 5.0% |
TPL | $24.5B | 45.2x | 38.1x | 27.2x | 24.2x | 31.8x | 28.2x | 31.5x | 2.2% |
PR | $20.1B | 15.6x | 10.5x | 3.5x | 3.0x | 7.0x | 5.9x | 6.2x | 8.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SM | $9.1B | 9.9x | 4.9x | 1.7x | 1.2x | 2.7x | 1.9x | 4.4x | -0.4% |
MTDR | $6.8B | 9.5x | 6.8x | 1.8x | 1.6x | 3.3x | 3.0x | 4.2x | 9.2% |
EQT | $31.4B | 11.0x | 12.4x | 3.4x | 3.4x | 4.9x | 5.0x | 6.0x | 12.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AR | $10.4B | 9.6x | 7.9x | 1.8x | 1.5x | 7.1x | 5.9x | 6.3x | 13.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SOC | Revenue | +5738.2% | +69.1% | −0.3% |
| EPS | −63.6% | −159.8% | +9.5% | |
DVN | Revenue | +54.3% | −1.1% | −2.1% |
| EPS | +33.1% | −4.2% | +5.5% | |
SHEL | Revenue | +27.1% | −6.9% | −3.6% |
| EPS | +91.1% | −15.5% | −7.5% | |
WMB | Revenue | +8.4% | +14.4% | +15.5% |
| EPS | +15.8% | +6.3% | +16.8% | |
CVX | Revenue | +29.6% | −8.2% | −2.9% |
| EPS | +135.1% | −14.0% | −12.5% | |
FANG | Revenue | +25.9% | −7.4% | +0.5% |
| EPS | +71.1% | −10.2% | +1.3% | |
SLB | Revenue | +4.1% | +7.8% | +6.7% |
| EPS | −13.9% | +28.6% | +15.5% | |
HAL | Revenue | +2.0% | +5.4% | +4.6% |
| EPS | +3.0% | +23.2% | +16.9% | |
BKR | Revenue | +2.3% | +10.9% | +7.5% |
| EPS | +6.7% | +14.6% | +20.0% | |
TPL | Revenue | +27.2% | +12.0% | +8.4% |
| EPS | +33.3% | +11.0% | −100.0% | |
PR | Revenue | +29.9% | +1.9% | −2.2% |
| EPS | +97.8% | +1.5% | −8.6% | |
SM | Revenue | +135.5% | +0.5% | −3.0% |
| EPS | +43.1% | +4.0% | −1.6% | |
MTDR | Revenue | +19.1% | +12.7% | +0.7% |
| EPS | +43.9% | +14.5% | −8.4% | |
EQT | Revenue | +9.9% | −0.8% | +11.9% |
| EPS | +37.2% | −5.4% | +40.3% | |
AR | Revenue | +31.0% | −0.1% | +8.3% |
| EPS | +135.1% | +3.9% | +26.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The cohort went up, not down
The premise of a quiet cross-cohort de-rating doesn't survive the tape. Over the trailing 30 days almost every crude-weighted name rose: SHEL +12.9%, CVX +10.2%, ARX.TO +8.2%, FANG +8.1%, PR +12.6%, SM +20.4%, TPL +19.9%, DVN +2.3%. Band states agree — FANG, PR, SHEL, SM and TPL are mildly bullish, ARX.TO and WMB strongly bullish, and all of DVN, SHEL, CVX, FANG, ARX.TO and WMB sit above their 200-day averages.
The "five-session weakness" is essentially a single session. On 27 July WMB fell 5.9%, DVN 4.2%, AR 3.5% and SHEL 2.3%; sessions from 13–24 July were flat-to-up for all of them. That day Brent dropped about 8.7%, its biggest one-day fall in more than three months, after President Trump said the US and Iran were in talks to end the war and both sides paused strikes. The 52-week highs for DVN, CVX, MTDR, AR, EQT and SHEL cluster on 30–31 March — the peak of the war premium. The 90-day "declines" are that premium draining, not a glut being priced.
Where the breakdown actually is
Oilfield services: HAL -16.7%, SLB -12.9%, BKR -12.2% over 90 days, all three flipping to mildly bearish on 6–9 July after five to seven months in bull bands. That break is not accompanied by guidance deterioration — Halliburton's Q2 revenue rose to $5.7bn from $5.4bn on stronger North American stimulation, and SLB reported stable North America with an unconventionals rebound. The other confirmed strongly bearish names are EQT (-12.5%) and AR (-12.2%), the gas side this desk covered on 28 July.
SOC is disqualified as a proxy. Its -53% month traces to a 30 June raise of up to $450m in stock and convertibles to repay an ExxonMobil senior secured term loan, layered on a Santa Ynez restart story that is permitting-and-execution driven, not curve-driven.
The risk points forward
The macro leg is real but unspent. EIA's July STEO cut its 2026 Brent forecast 14% to roughly $82 and 2027 18% to about $65, explicitly attributing the higher production path to the reopening of the Strait of Hormuz. The IEA still models a record 2026 surplus above 4 mb/d against demand growth near 930 kb/d, while OPEC+ has approved a fourth consecutive monthly quota hike for July and another increase for August as Gulf shipments recovered.
Against that, the producers are not behaving defensively: Rystad notes flat 2026 E&P capex plans, a 543 rig count and ~$60 corporate breakevens, Devon guided to 1.380 mmboe/d on ~$4.9bn capex with an $8bn buyback authorisation, and WMB's drop came days after a $5.34bn Blackstone-led power infrastructure investment. The de-rating, if it comes, is a 2027 strip problem the bands haven't registered yet.