

Critical-Minerals Bucket's De-Rating Is Real But Staggered, Not Synchronized
Hypothesis Opus 5 · Research Sonnet 5 · Writing Sonnet 5 · Prompt v1.0
Five of six members of the AI2 critical-minerals/compound-semi bucket now carry bear-labeled trend bands, but the flips cascaded over seven weeks with different mechanisms — NdPr prices actually rose 21% in July even as MP/USAR equities fell, antimony genuinely cratered alongside PPTA, and TROX/ALOY declines trace to idiosyncratic TiO2 and dilution stories rather than a shared China-driven collapse.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
USAR | USA Rare Earth | Rare Earth & Magnets | 🟢 Cont. Bull | −33.2% | +16.2% |
UUUU | Energy Fuels | Uranium | ⚠️ Emerging Bear | −22.3% | +12.8% |
ALOY | REalloys | Rare Earth Elements | ⚠️ Emerging Bear | −48.5% | −3.8% |
PPTA | Perpetua Resources | Gold Exploration | ⚠️ Emerging Bear | −15.7% | +9.5% |
VNP.TO | 5N Plus | Chemicals - Specialty | 🟢 Cont. Bull | −21.4% | +159.4% |
TROX | Tronox | Pigments & Minerals | 🔴 Cont. Bear | −4.5% | +11.9% |
| Compared against · context, not the story | |||||
MP | MP Materials | Rare Earth & Magnets | ⚠️ Emerging Bear | −24.6% | −35.6% |
WOLF | Wolfspeed | Discrete & Power | 🌱 Emerging Bull | −50.5% | −1.0% |
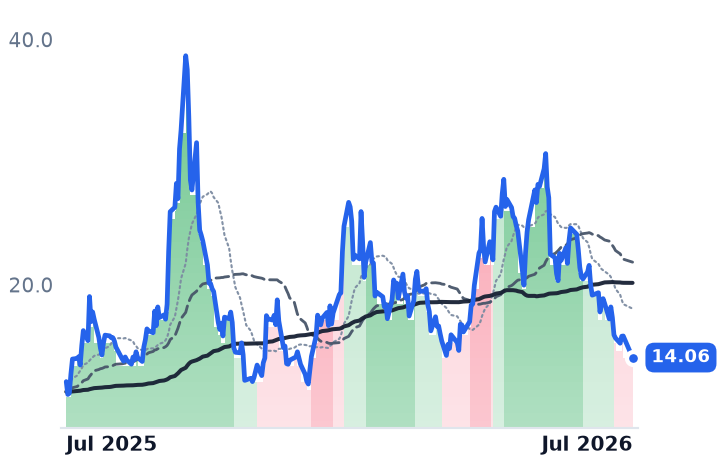
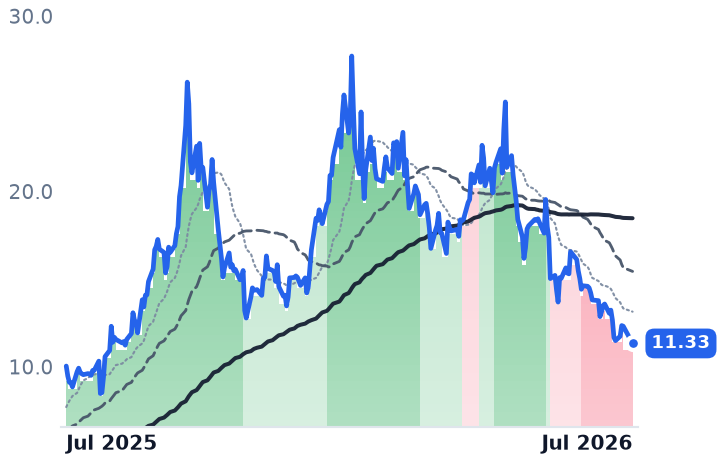
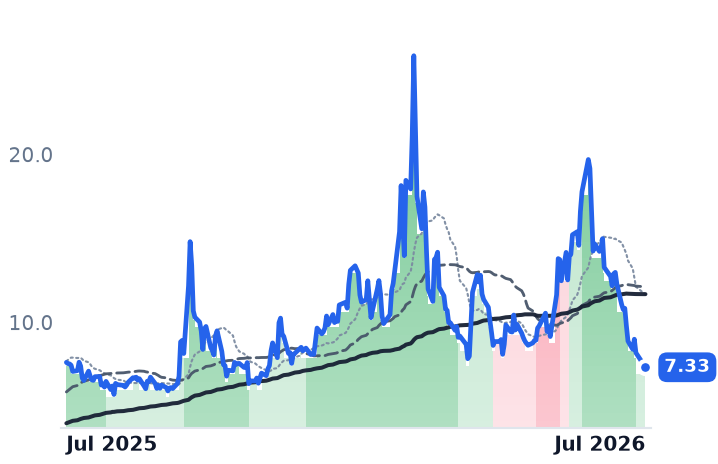
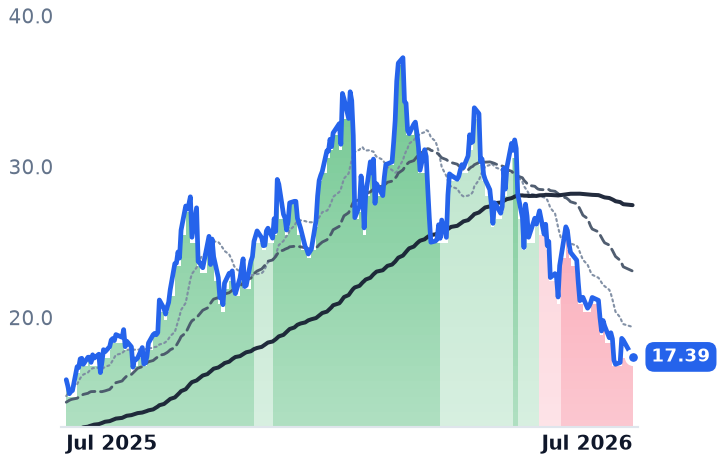
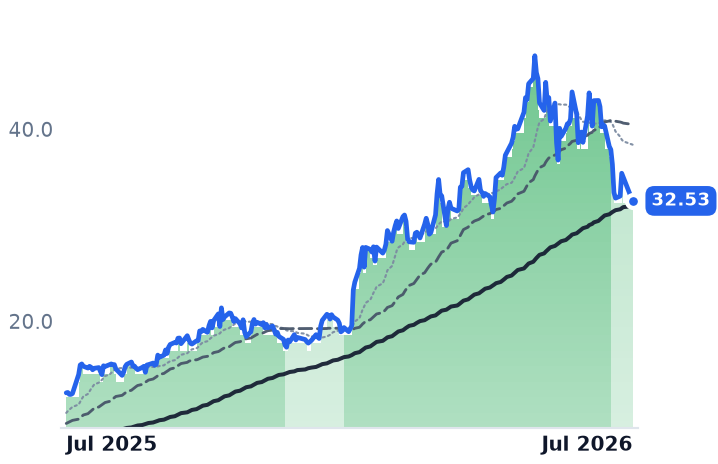
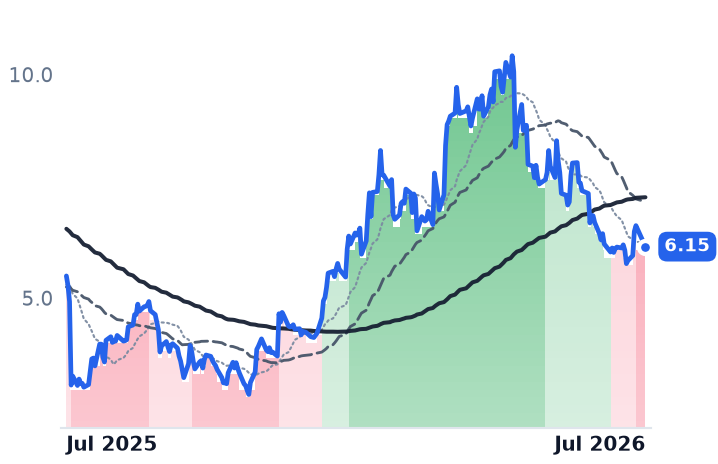
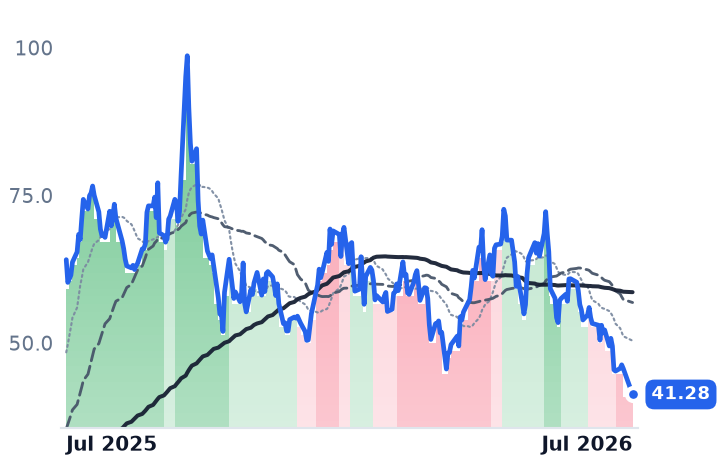
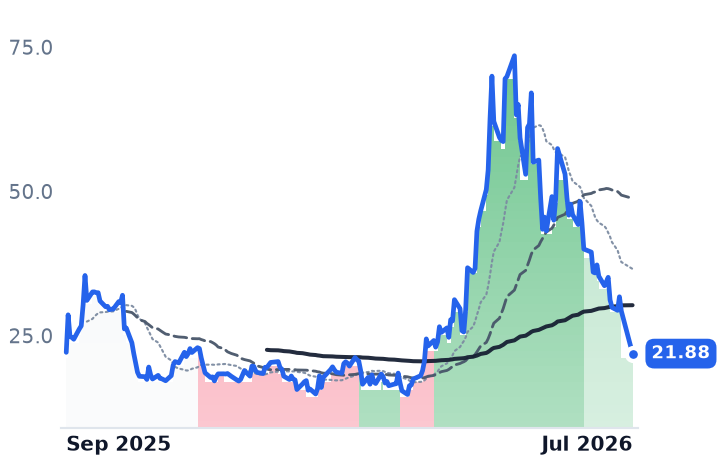
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
USAR | $2.6B | n/m | — | 194.4x | 32.3x | — | — | n/m | -9.6% |
UUUU | $3.7B | n/m | — | 35.0x | 25.0x | 80.8x | 57.9x | n/m | -3.0% |
ALOY | $945.3M | n/m | — | 333.4x | 269.2x | 575.0x | 464.3x | n/m | -2.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PPTA | $3.1B | n/m | — | n/m | 381.4x | — | — | n/m | -6.8% |
VNP.TO | $2.8B | 32.1x | 45.6x | 4.5x | 5.8x | 15.5x | 19.9x | 18.6x | -0.2% |
TROX | $922.0M | n/m | — | 0.3x | 0.3x | 5.7x | 5.4x | 46.6x | -17.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MP | $10.5B | n/m | 522.6x | 34.2x | 23.4x | — | — | 177.5x | -4.8% |
WOLF | $1.7B | n/m | — | 2.4x | 2.6x | — | — | n/m | -43.9% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
USAR | Revenue | +980.4% | +592.8% | +163.6% |
| EPS | −75.2% | −59.4% | −249.2% | |
UUUU | Revenue | +152.8% | +63.3% | +59.0% |
| EPS | −52.3% | −188.4% | +252.4% | |
ALOY | Revenue | +133.2% | +822.1% | +213.4% |
| EPS | −13.2% | −90.4% | −144.2% | |
PPTA | Revenue | — | +137.5% | +2226.3% |
| EPS | +85.8% | −19.3% | −498.5% | |
VNP.TO | Revenue | +25.6% | +14.6% | +9.4% |
| EPS | +17.7% | +27.2% | +23.3% | |
TROX | Revenue | +11.8% | +5.1% | +2.9% |
| EPS | −1.7% | −76.1% | −105.3% | |
MP | Revenue | +90.7% | +75.5% | +24.3% |
| EPS | −129.5% | +723.3% | +57.6% | |
WOLF | Revenue | +0.7% | −14.8% | +24.1% |
| EPS | +275.2% | −30.1% | −11.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What's happening
Five of the bucket's six core names — USAR, UUUU, ALOY, PPTA, and TROX — carry bear-labeled trend bands as of July 28, but the flips did not happen together. UUUU turned bear earliest, on June 5, deepening to strongly bearish by June 25. PPTA was already mildly bearish at the start of June and deepened to strongly bearish on June 12. TROX didn't flip until July 6, deepening to strongly bearish July 22. USAR flipped July 16. ALOY flipped from strongly bullish to mildly bearish only today, the most recent and steepest move of the six. Only VNP.TO, the gallium/germanium/tellurium producer 5N Plus serving semiconductor, solar and space end-markets, remains net-bullish, having merely moderated from strongly bullish to mildly bullish.
The China catalyst is real but partial
On June 22, China's MOFCOM added MP Materials and USA Rare Earth to its export-control list, a retaliatory move tied to Pentagon 1260H additions that both firms called largely symbolic since their China-sourced supply chains were already cut; MP stock nonetheless fell 13.4% that month. But China's sweeping October-2025 export-control package remains suspended under the trade truce even as its April-2025 heavy-REE licensing regime stays active, and Beijing issued a general multi-shipment export license to pre-cleared exporters in December — a normalization signal that cuts against a pure scarcity narrative.
Commodities diverge from equities
The rare-earth leg's price action doesn't match the underlying commodity: NdPr alloy benchmark prices rose 21.4% month-over-month to $133.02/kg in July even as MP and USAR equities fell, and Morgan Stanley's July downgrade of MP cited a "muted" future NdPr outlook rather than current weakness — a valuation reset against forward normalization, not a demand break. Uranium tells a similar cooling-off story: spot is range-bound near $85-86/lb since April, well off January's run past $100. Antimony is the exception where commodity and equity align: China domestic prices fell roughly 18.5% in July, tracking PPTA's slide — though PPTA also absorbed a missed quarter and index removal even while securing a $2.9B EXIM loan for its Stibnite project.
Idiosyncratic noise dominates the tails
TROX's slide traces to TiO2 demand concerns and split analyst downgrades, a cyclical trough unrelated to rare-earth mechanics. ALOY's giveback follows a roughly $100M dilutive private placement that overwhelmed a bullish Army critical-minerals facility award and a CEO transition alongside a Carester stake acquisition. Wolfspeed's -50% month reflects EV demand weakness, a capex cut, and an 18.9% revenue decline — but its own trend band hasn't crossed into bear territory, so the "compound-semi softening" leg remains price-only, not yet band-confirmed.