

MPS ran 41% in a month and past the target that started it
Prompt v1.0
MPS Ltd is +41% in a month and +48% over 90 days, but 24.7 points of that came in two July sessions on Q1 FY27 results, and the stock now trades 23.5% above the sell-side fair value that helped spark the rally. The AI angle is real but it's a margin lever inside existing work — not the publisher licensing-corpus story the setup implies.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
MPSLTD.BO | MPS | Publishing | 🔴 Cont. Bear | +38.0% | +18.2% |
GETY | Getty Images | Internet Content & Information | 🔴 Cont. Bear | −56.6% | −77.8% |
SSTK | Shutterstock | Media & Content Distribution | 🔴 Cont. Bear | −57.7% | −68.2% |
INFY | Infosys | Enterprise Consulting & Systems Integration | 🔴 Cont. Bear | +15.4% | −26.9% |
TCS.NS | Tata Consultancy Services | Information Technology Services | 🔴 Cont. Bear | +14.3% | −20.4% |
NEWGEN.NS | NEWGEN.NS | — | 🔴 Cont. Bear | — | — |
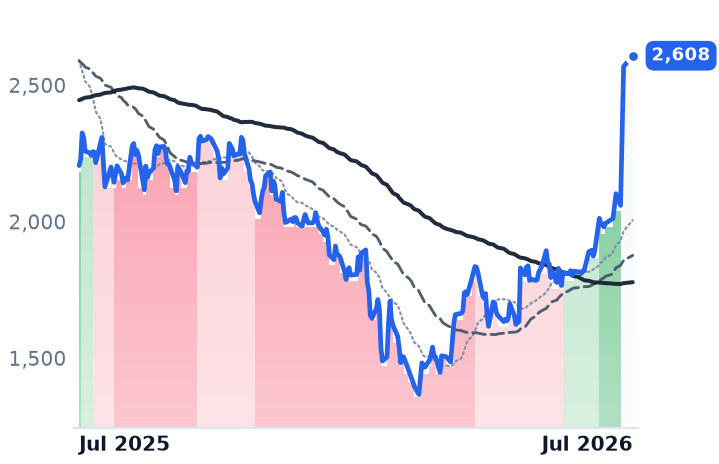
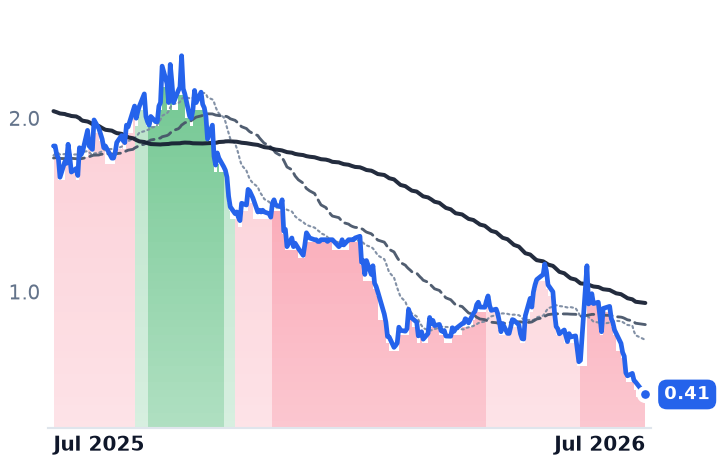
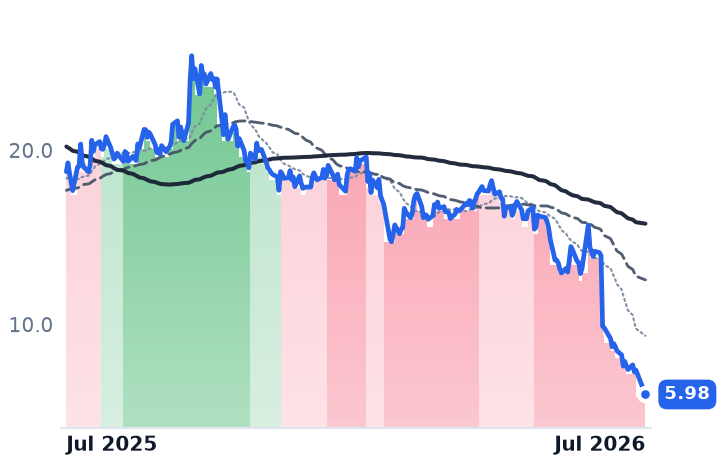
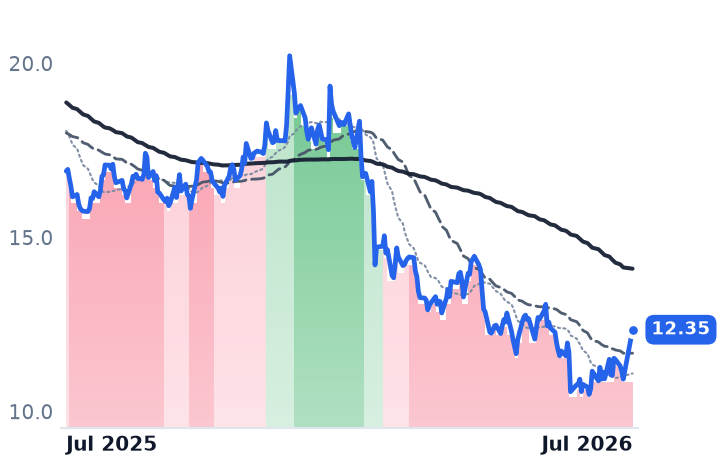
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MPSLTD.BO | $31.1B | 17.9x | 16.3x | 4.2x | 3.4x | 5.2x | 4.2x | 12.9x | 3.2% |
GETY | $128.8M | n/m | 13.4x | 0.1x | 0.1x | 0.2x | 0.2x | 11.7x | -65.1% |
SSTK | $198.8M | n/m | — | 0.2x | 0.3x | 0.4x | 0.4x | n/m | 44.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
INFY | $47.1B | 14.2x | 14.6x | 2.3x | 2.3x | 7.7x | 7.7x | 9.1x | 8.1% |
TCS.NS | $8.6T | 17.2x | 15.4x | 3.1x | 2.9x | 8.2x | 7.8x | 11.8x | 5.8% |
NEWGEN.NS | — | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MPSLTD.BO | Revenue | +5.5% | +17.7% | +14.1% |
| EPS | +14.0% | +16.8% | +18.4% | |
GETY | Revenue | +1.8% | +0.9% | +3.8% |
| EPS | −112.1% | +126.0% | +185.7% | |
SSTK | Revenue | −23.3% | −8.0% | −4.9% |
| EPS | −145.9% | −148.0% | +10.2% | |
INFY | Revenue | +1.6% | +4.0% | +3.7% |
| EPS | +2.3% | +4.3% | +4.6% | |
TCS.NS | Revenue | +4.0% | +8.9% | +3.9% |
| EPS | +4.0% | +9.1% | +4.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The move is real, the shape is not what it looks like
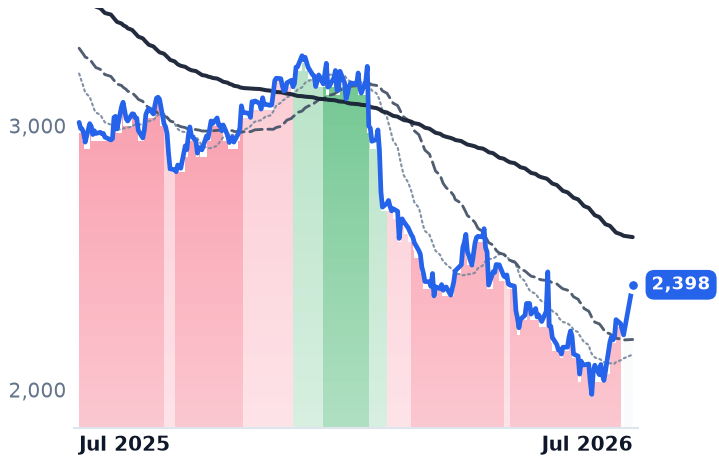
MPSLTD.BO closed at ₹2,568.35 on 22 July against ₹1,816.85 a month earlier — +41.4% — with +47.9% over 90 days and +40.2% over 180. The band history supports a genuine trend exit: 95 sessions of strongly bearish through 13 April, then mildly bearish, then mildly bullish from 12 June and strongly bullish from 6 July. But the price path is not the gradual grind the thesis assumes. Two discrete events carry most of it: a +6.2% jump on 6 July when HDFC Securities named MPS its 'Stock Pick of the Week' with a ₹2,080 base case and ₹2,250 bull case, and a +24.7% two-session move on 21–22 July when the stock hit a 20% upper circuit on Q1 FY27 results alongside board approval for a Singapore subsidiary. Volume on 22 July was 96,087 shares against a typical few hundred to a couple of thousand in prior weeks.
The print itself was strong: revenue of ₹224.24 crore, up 20.4%, EBITDA +53% and PAT +43% with EPS of ₹29.70. It is also a discontinuity — the December 2025 quarter had revenue down 2.1% YoY and net income down 12.8%.
Runway, not direction, is the constraint
HDFC's base case was reached within eight days. At ₹2,568.35 the stock sits 23.5% above that ₹2,080 base case, 14.1% above the ₹2,250 bull case, 36.5% above its 200-session average, at ~25x trailing and ~19x FY28E on a single covering analyst's ₹132.75 estimate — above the 17x the bull case assumed. Notably, MPS is still only +5.1% versus a year ago; this is drawdown recovery.
The AI leg reads differently on the call
On the Q1 call, management framed AI as a margin driver, with over 60% of education growth AI-driven — productivity inside existing work, not a corpus-licensing line. That pool sits upstream anyway: Wiley booked $49 million of AI licensing revenue in fiscal 2026, captured at the publisher. And education segment profit grew 29% against 42% segment revenue growth.
Cohort: rotation, not confirmation
The macro leg holds partially. Nifty IT rose ~10% over ten July sessions with eClerx +27% in the month, and TCS opened the season with ₹13,349 crore net profit and better H2 commentary, helped by offshore mix shift after the $100,000 H-1B petition fee that pushed the rupee to 88.75/$. But INFY.NS was strongly bearish for 89 straight sessions to 20 July and is -33% YoY, TCS.NS -30%, and Newgen fell despite +11% revenue and +26% PAT. The stock-image cousins don't belong in the story at all: GETY -58% and SSTK -53% on the month trace to the terminated $3.7bn merger after the CMA divestiture demand, a corporate-structure break rather than AI erosion.