

AI power cohort: a staggered multiple unwind, not a demand break
Prompt v1.0
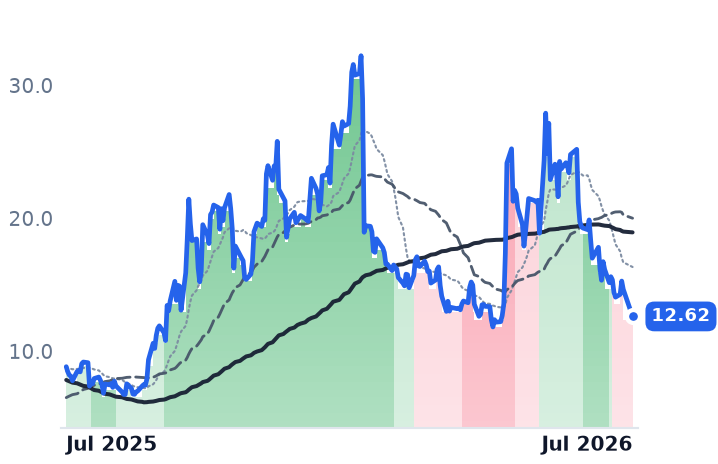
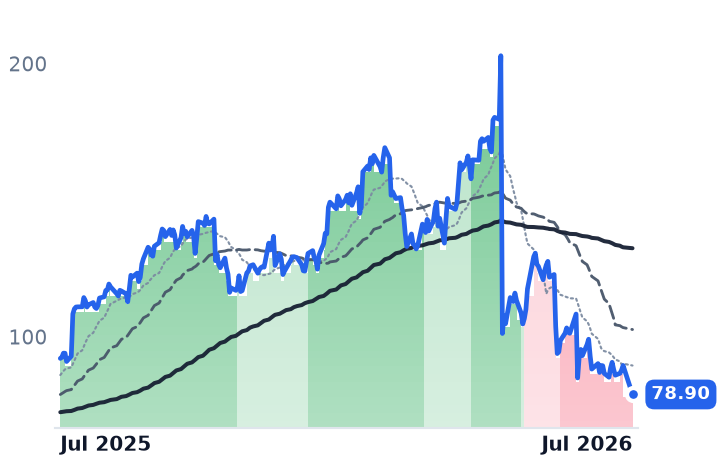
The AI-power buildout cohort has been rolling out of bull bands since mid-May — PRIM, VRT, PWR, MOD, STRL, FLNC, then BE and AGX last — but eight of ten names still sit above their 200-day averages and the order books are accelerating, not shrinking. What's compressing is the multiple, not the backlog.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
AGX | Argan | Energy & Power Project Solutions | 🟢 Cont. Bull | −34.0% | +121.5% |
BE | Bloom Energy | Fuel Cell & Hydrogen | 🟢 Cont. Bull | −39.3% | +379.7% |
GEV | GE Vernova | GE Vernova Integrated | 🟢 Cont. Bull | −14.4% | +45.9% |
PWR | Quanta Services | Electrical & Power Infrastructure | 🟢 Cont. Bull | −17.6% | +42.9% |
STRL | Sterling Infrastructure | Infrastructure & Civil Construction | 🟢 Cont. Bull | −33.9% | +104.1% |
VRT | Vertiv | Data Center Power & Thermal | 🟢 Cont. Bull | −12.2% | +89.3% |
ETN | Eaton | Power & Propulsion Systems | 🟢 Cont. Bull | −5.4% | −0.8% |
MOD | Modine Manufacturing | Thermal & Powertrain Components | 🟢 Cont. Bull | −18.8% | +97.2% |
FLNC | Fluence Energy | Energy Storage Systems | 🟢 Cont. Bull | −34.1% | +42.8% |
PRIM | Primoris Services | Energy & Power Project Solutions | ⚠️ Emerging Bear | −18.8% | −14.3% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AGX | $8.0B | 49.0x | 47.2x | 7.7x | 6.2x | 36.7x | 29.8x | 40.7x | 6.1% |
BE | $67.7B | 275.0x | 87.8x | 21.7x | 16.7x | 69.6x | 53.5x | 194.0x | 0.9% |
GEV | $268.1B | 28.6x | 32.8x | 6.5x | 5.8x | 32.1x | 28.8x | 29.9x | 4.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PWR | $100.3B | 75.5x | 42.9x | 3.1x | 2.7x | 21.2x | 18.5x | 35.1x | 2.4% |
STRL | $18.3B | 52.7x | 31.6x | 6.3x | 4.9x | 27.3x | 21.0x | 30.8x | 2.4% |
VRT | $142.5B | 91.1x | 57.7x | 13.1x | 10.3x | 36.3x | 28.5x | 61.1x | 1.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ETN | $178.2B | 46.6x | 34.1x | 5.9x | 5.5x | 16.5x | 15.3x | 32.9x | 2.5% |
MOD | $14.3B | 146.4x | 34.3x | 5.0x | 3.7x | 20.9x | 15.7x | 57.0x | 0.1% |
FLNC | $3.8B | n/m | — | 1.5x | 1.1x | 12.9x | 9.9x | n/m | -7.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PRIM | $6.1B | 24.7x | 23.4x | 0.8x | 0.8x | 7.9x | 7.7x | 14.4x | 2.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AGX | Revenue | +12.1% | +36.2% | +25.4% |
| EPS | +65.8% | +44.2% | +29.3% | |
BE | Revenue | +112.4% | +65.1% | +46.0% |
| EPS | +374.5% | +83.5% | +60.7% | |
GEV | Revenue | +23.4% | +14.6% | +15.3% |
| EPS | +322.4% | −19.0% | +40.3% | |
PWR | Revenue | +34.0% | +15.2% | +13.1% |
| EPS | +46.4% | +16.9% | +17.3% | |
STRL | Revenue | +58.0% | +18.5% | +26.4% |
| EPS | +82.4% | +27.3% | +20.2% | |
VRT | Revenue | +35.2% | +25.8% | +19.4% |
| EPS | +55.6% | +33.8% | +25.8% | |
ETN | Revenue | +18.5% | +10.9% | +8.9% |
| EPS | +11.6% | +18.3% | +16.9% | |
MOD | Revenue | +22.6% | +21.8% | +19.1% |
| EPS | +33.4% | +52.5% | +31.7% | |
FLNC | Revenue | +29.7% | +23.6% | +18.1% |
| EPS | −61.9% | −292.6% | +127.2% | |
PRIM | Revenue | +2.8% | +11.4% | +7.6% |
| EPS | −12.3% | +24.1% | +10.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The cascade started in May, not last week
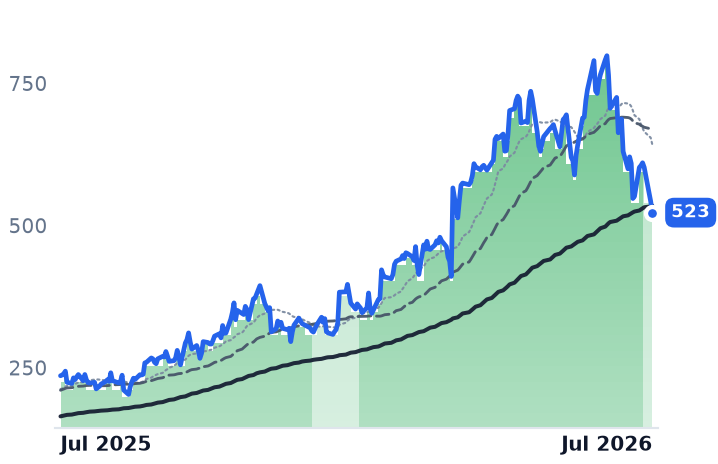
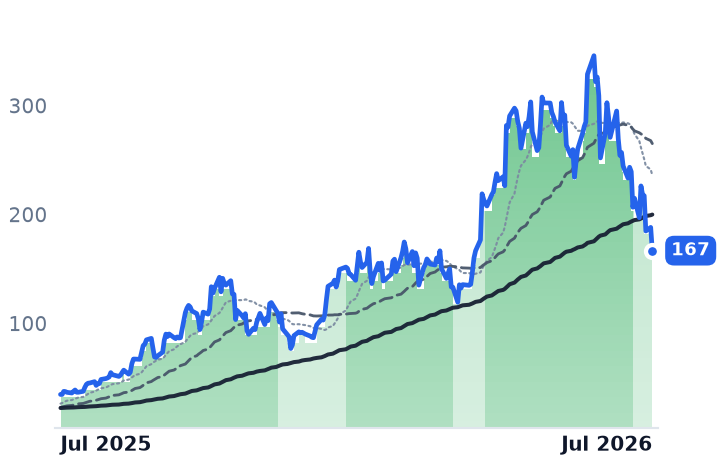
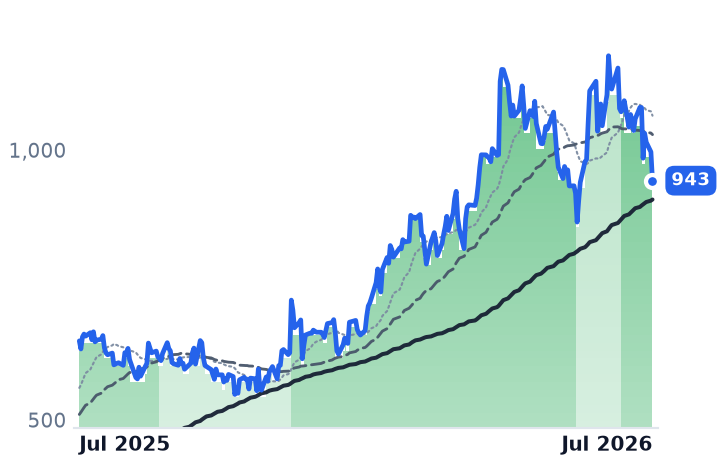
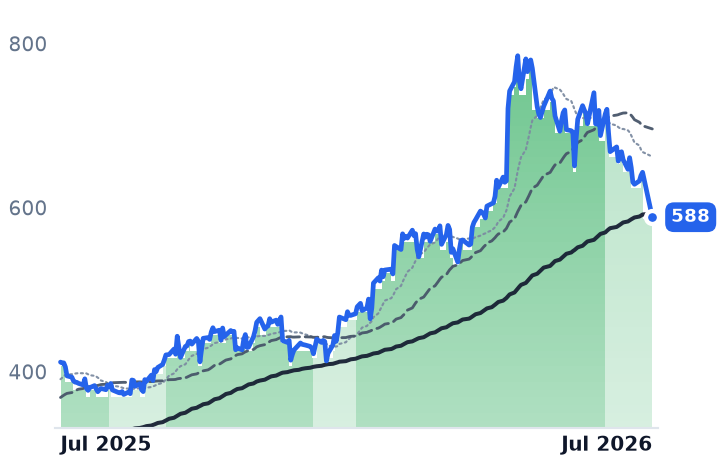
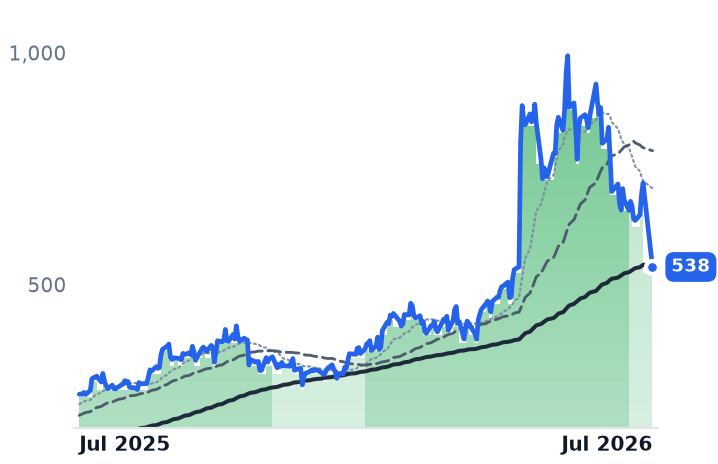
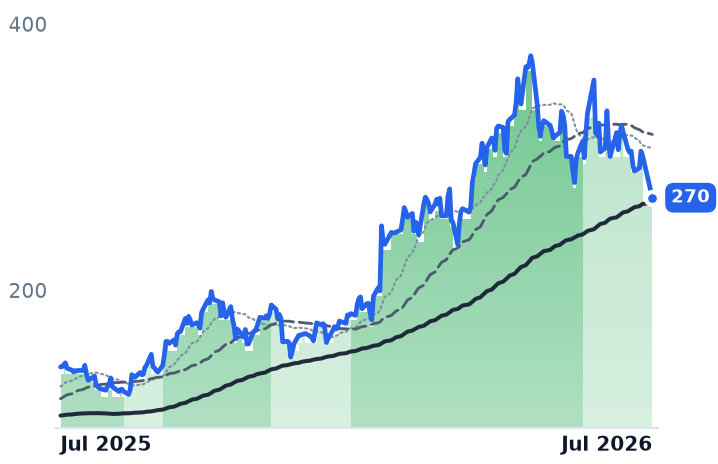
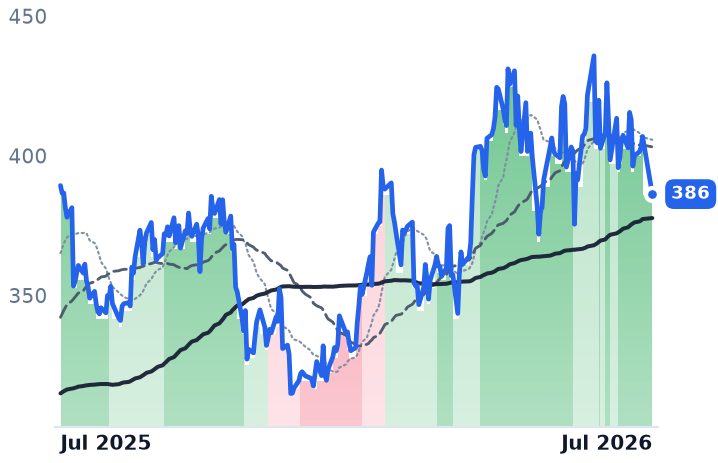
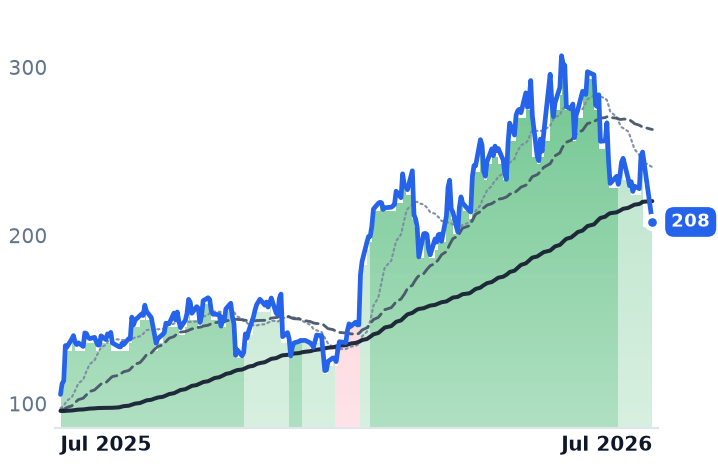
Band history dates the de-rating well before the five-session drop that prompted this look. PRIM left strongly bullish on 5/18 and reached strongly bearish on 6/12; VRT exited 6/15; PWR 6/29; MOD 7/7; STRL and FLNC 7/13; BE 7/16; AGX 7/22. The two names framed as leaders were the last to roll. Meanwhile GEV re-entered strongly bullish on 7/8 and ETN on 7/7, and both remain there.
Positioning is far from broken. Only FLNC ($14.66 vs a $18.95 200-day) and PRIM ($89.52 vs $132.40) trade below trend. AGX at $542.52 is 32.1% under its 6/30 high of $798.55 yet still 12.9% above its 200-day; BE at $188.18 is 45.6% off its 6/22 high but 6.3% above its own. Two members moved the other way entirely: STRL and MOD each rose 7.6% over their trailing five sessions, and STRL is +45.1% over three months and +104.7% over six.
The order book didn't break — the multiple did
GE Vernova's Q2 print showed orders of $24.2bn, up 88% organically, backlog of $176bn and gas equipment backlog plus slot reservations rising from 100 GW to 116 GW, with FY26 guidance raised. Management said on the call it expects to be "mostly sold out through 2030," with new orders pricing 10–20 points above existing backlog. Shares still fell ~6.4% on an EPS miss and a wider Wind loss, even as Morgan Stanley lifted its target to $1,350. The demand leg of the hypothesis fails outright: Alphabet raised 2026 capex toward $205bn, with the big four planning ~$725bn, up ~77% YoY — and then slid 7% on the news, with Amazon, Meta and Microsoft facing the same scrutiny this week. Supply, not demand, is the binding constraint: large-frame turbines are sold out through 2028, pushing developers to reciprocating engines.
Single-name events, not cohort read-through
BE's slide traces to Hunterbrook's 7/8 report on scandium sourcing and the gap between a ~$20bn stated backlog and ~$492m of audited obligations, which Bloom rejected the same day ahead of 7/28 results. AGX's decline is tied to ~$119.4m of insider selling and a backlog dip to $2.8bn from $2.9bn. PRIM's crash was a renewables revenue shock plus a COO departure, and FLNC fell 15.8% on 6/23 on rotation despite a record $5.6bn backlog.
What would make it structural
The bear case in the desk's notes is fuel, not demand: Chronometer's Matthew Smith named AGX and BE "clear losers" on 6/22, arguing gas plant orders slow near 2028 as LNG export growth collides with limited supply, while ranking GEV combined-cycle at the top of the efficiency stack — which cuts against treating GEV and BE as one cohort. Rate math adds pressure: markets price ~82% odds of a September hike with the FOMC meeting 7/28–29. One caveat: prices for ETN, FLNC, MOD, PRIM, PWR, STRL and VRT stop 7/22 while AGX, BE and GEV run to 7/27, so five-session comparisons are not same-dated.