

AI-hardware names cratered 45-51% in a month, but trend bands still call it bullish
Hypothesis Opus 5 · Research Sonnet 5 · Writing Sonnet 5 · Prompt v1.0
Corning, Wolfspeed, Vicor, SanDisk and MaxLinear each lost 46-51% of their value over the past 30 days amid a cascade of distinct earnings and China-competition shocks, yet none of them — nor Western Digital, Micron, Lumentum, Aehr or AOI — have actually broken into bear-trend territory, and the hyperscaler capex data needed to confirm a genuine cohort de-rating hasn't even been reported yet.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
GLW | Corning | Display & Optical Materials | 🟢 Cont. Bull | −50.7% | +129.5% |
WOLF | Wolfspeed | Discrete & Power | 🌱 Emerging Bull | −50.5% | −1.0% |
VICR | Vicor | Other | 🟢 Cont. Bull | −47.6% | +317.9% |
SNDK | Sandisk | Specialty Manufacturing & Components | 🟢 Cont. Bull | −46.5% | +2516.6% |
MXL | MaxLinear | RF & Wireless | 🟢 Cont. Bull | −45.7% | +252.1% |
WDC | Western Digital | Data Storage Devices | 🟢 Cont. Bull | −28.9% | +573.5% |
MU | Micron Technology | Memory (DRAM/NAND) | 🟢 Cont. Bull | −28.3% | +638.6% |
LITE | Lumentum | Optical Transport & Switching | 🟢 Cont. Bull | −23.4% | +508.3% |
AEHR | Aehr Test Systems | Semiconduct Equipment | 🟢 Cont. Bull | −26.1% | +234.8% |
AAOI | Applied Optoelectronics | RF & Wireless | 🟢 Cont. Bull | −41.3% | +249.5% |
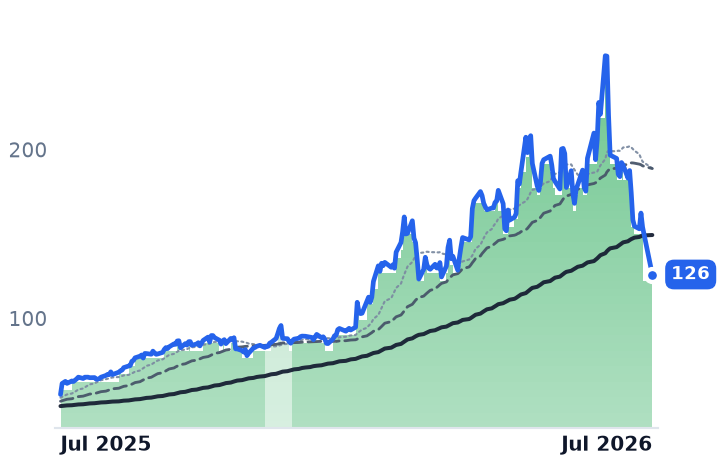
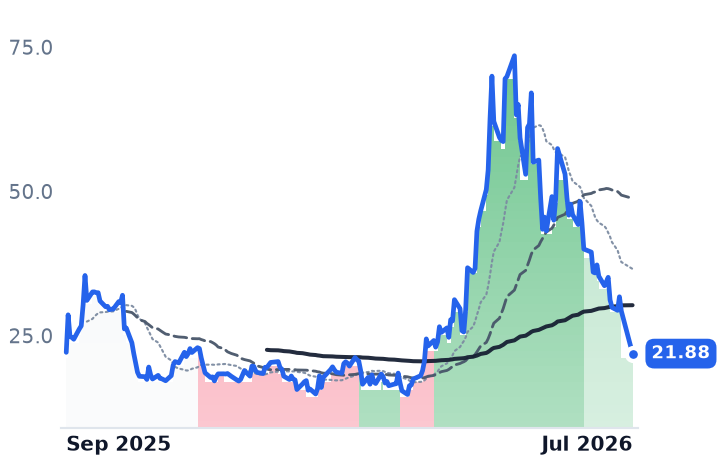
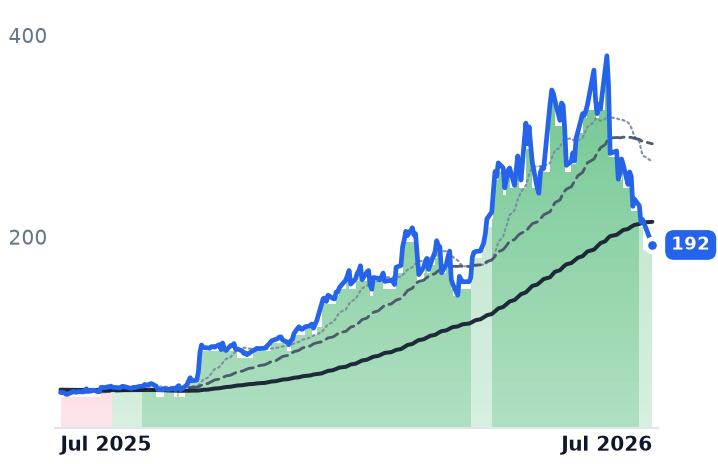
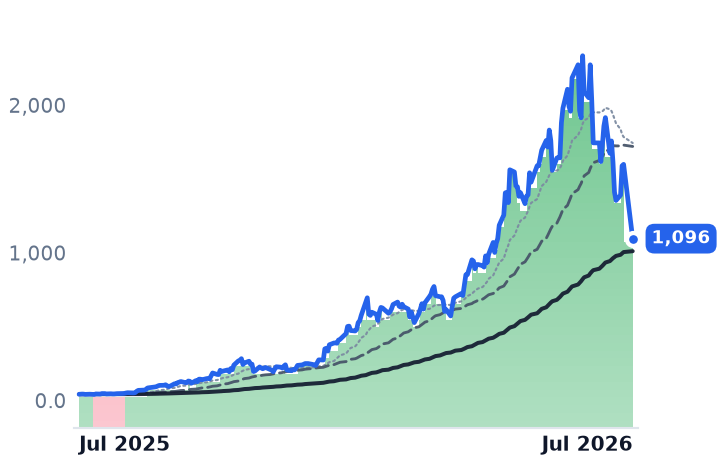
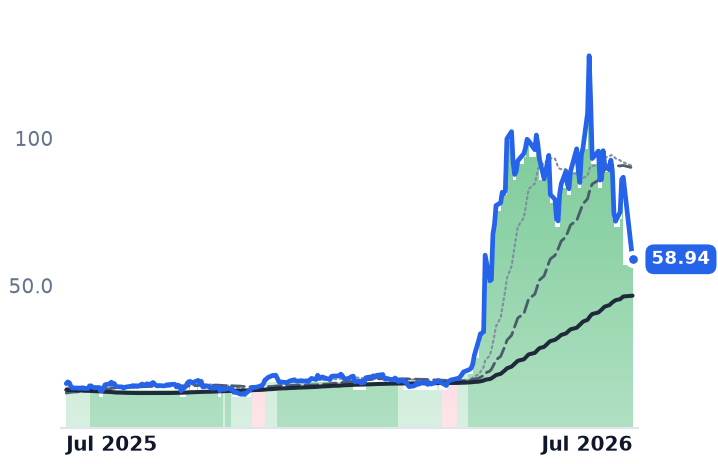
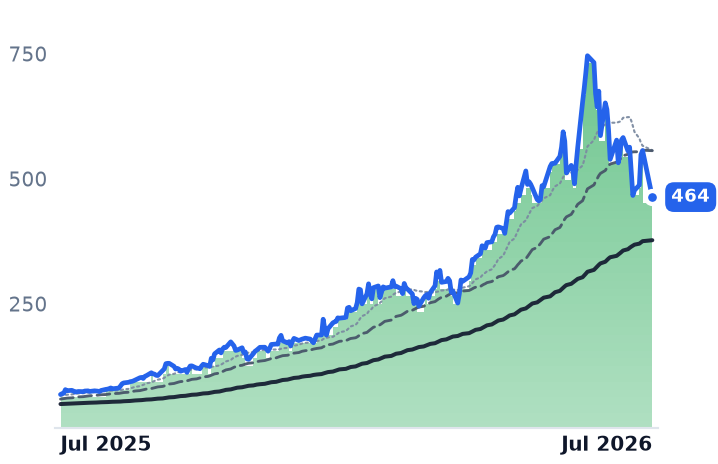
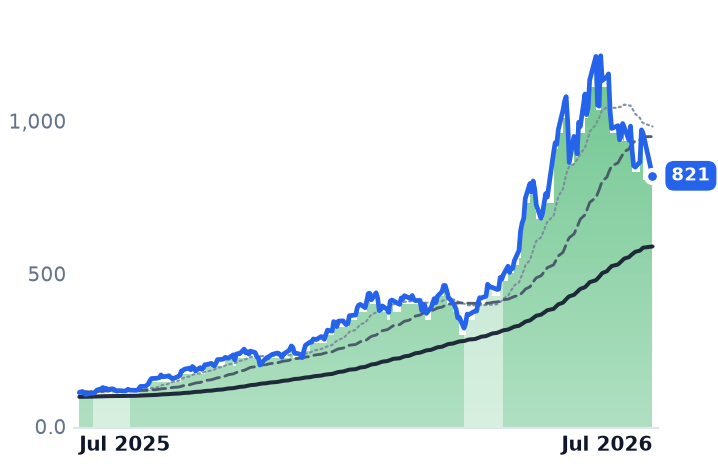
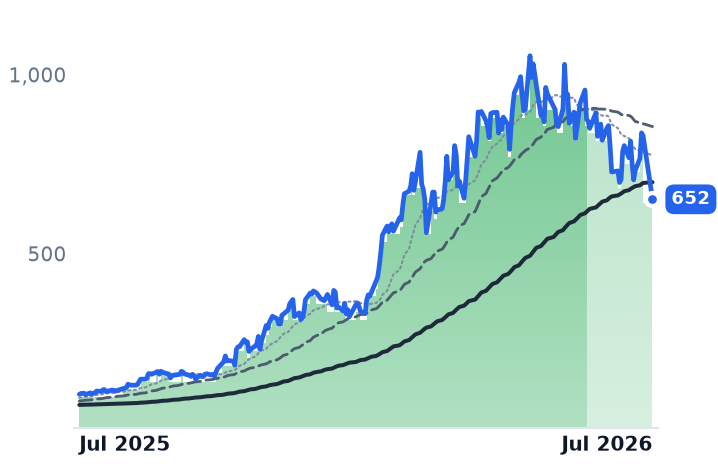
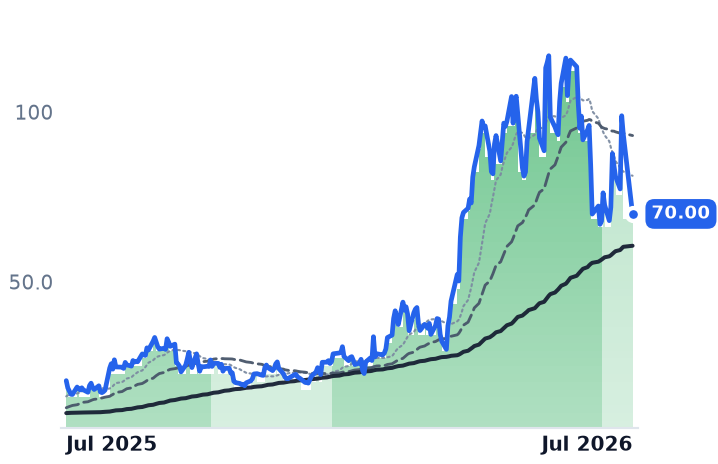
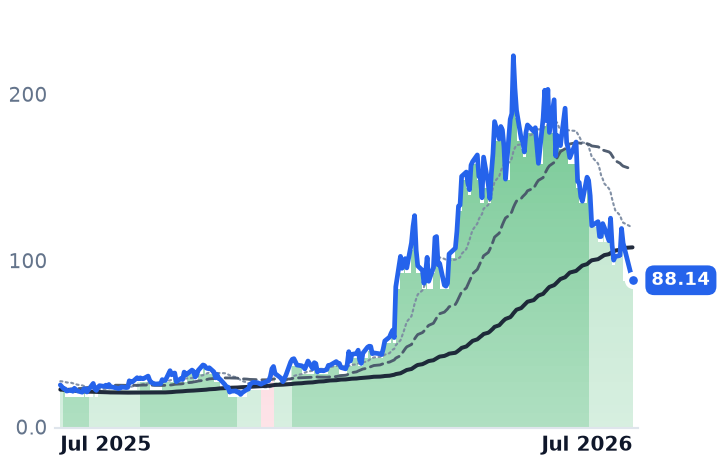
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GLW | $137.7B | 72.4x | 48.9x | 8.1x | 7.2x | 22.4x | 19.7x | 37.1x | 1.7% |
WOLF | $1.7B | n/m | — | 2.4x | 2.6x | — | — | n/m | -43.9% |
VICR | $11.5B | 79.7x | 74.0x | 24.3x | 19.1x | 42.9x | 33.7x | 86.8x | 0.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SNDK | $208.5B | 46.2x | 21.8x | 15.8x | 10.6x | 28.2x | 19.0x | 37.1x | 2.1% |
MXL | $7.7B | n/m | 50.6x | 13.5x | 10.6x | 23.5x | 18.5x | n/m | 0.0% |
WDC | $166.1B | 25.6x | 48.3x | 14.1x | 12.9x | 31.1x | 28.4x | 31.1x | 1.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MU | $1.0T | 19.9x | 12.2x | 11.2x | 7.8x | 15.4x | 10.7x | 14.5x | 2.6% |
LITE | $75.4B | n/m | 52.1x | 25.0x | 13.3x | 60.0x | 31.9x | n/m | 0.7% |
AEHR | $4.7B | n/m | 231.1x | 93.3x | 37.7x | 269.1x | 108.8x | n/m | -0.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AAOI | $12.4B | n/m | 149.9x | 20.9x | 11.9x | 72.1x | 41.3x | n/m | -3.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
GLW | Revenue | +17.5% | +18.7% | +21.0% |
| EPS | +29.6% | +31.7% | +36.5% | |
WOLF | Revenue | +0.7% | −14.8% | +24.1% |
| EPS | +275.2% | −30.1% | −11.8% | |
VICR | Revenue | +33.1% | +55.6% | +22.2% |
| EPS | +58.9% | +73.2% | +33.0% | |
SNDK | Revenue | +169.2% | +113.5% | +7.0% |
| EPS | +2283.0% | +167.8% | +5.6% | |
MXL | Revenue | +55.6% | +29.7% | +18.5% |
| EPS | +479.6% | +54.2% | +19.7% | |
WDC | Revenue | +36.9% | +37.2% | +26.5% |
| EPS | +106.2% | +72.8% | +48.0% | |
MU | Revenue | +248.0% | +92.8% | +11.4% |
| EPS | +804.9% | +111.2% | +7.9% | |
LITE | Revenue | +83.9% | +89.0% | +54.6% |
| EPS | +314.0% | +125.9% | +58.9% | |
AEHR | Revenue | −17.7% | +152.5% | +67.8% |
| EPS | −211.4% | −570.1% | +119.6% | |
AAOI | Revenue | +129.8% | +169.3% | +48.7% |
| EPS | −417.3% | +454.2% | +102.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
A brutal month, but not a clean trend break
Corning (GLW), Wolfspeed (WOLF), Vicor (VICR), SanDisk (SNDK) and MaxLinear (MXL) have each dropped 46% to 51% over the past 30 days, with the damage spilling into Western Digital, Micron, Lumentum, Aehr and AOI. The size of the move looks like the start of a cohort-wide AI-hardware de-rating. But the underlying trend-band data doesn't back that up: GLW, SNDK, MXL, WDC and MU are still tagged strongly bullish, while WOLF, VICR, Lumentum, Aehr and AOI have only softened from strongly bullish to mildly bullish — still bullish, not bear. That's mechanically explainable: these stocks ran so hard over the prior year (SanDisk is still up roughly 2,517% year over year even after halving) that moving averages remain far below spot price, keeping the mechanical trend signal lagging reality.
The decline is a cascade of distinct shocks, not one story
Rather than a single macro catalyst, the month has been a chain of separate triggers. Corning's Q2 print on July 28 brought soft Q3 guidance and decelerating optical growth, and the reaction was described as Corning tumbling and dragging Lumentum, AXT, Coherent and Marvell down in sympathy, a move Schaeffer's attributed to a 'guidance whiff' compounded by an 'AI infrastructure rotation' narrative. SanDisk's crash traces to fears revived by ChangXin Memory Technologies' blockbuster Shanghai IPO reviving China NAND-competition worries, layered on top of a broader memory-sector selloff tied to Samsung and SK Hynix earnings read-throughs that pushed the group into what's being called a bear market even as YTD gains remain enormous. Vicor's slide combined heavy insider selling with a 'sell the beat' reaction even after a strong Q2 earnings report, and MaxLinear fell nearly 18% immediately after beating Q2 estimates — classic sell-the-news dynamics on extended, richly priced stocks.
The macro validator hasn't landed yet
The hypothesis's core macro test — late-July hyperscaler capex guidance — is still pending: Microsoft, Meta, Amazon and Alphabet report after this data cutoff, and pre-print combined 2026 guidance stood at roughly $725 billion, up about 77% year over year, i.e. guided up, not down. Memory contract prices tell a similar story: TrendForce still projects DRAM and NAND contract prices rising in Q3, just at a decelerating pace versus the blistering first-half increases — a digestion signal, not a rollover. Even Wolfspeed's SiC weakness is mixed rather than a clean end-demand collapse, with datacenter-linked SiC revenue reportedly still growing even as EV-linked demand softens.
Downside room varies sharply by name
GLW, MXL and SNDK remain far above pre-2025-run levels even after the crash, while Vicor's post-crash price has already fallen inside the analyst target range flagged back in May, suggesting its de-rating may be closer to done than early.