

The 'Non-AI Rotation' Selloff Story Falls Apart: Four Names, Four Idiosyncratic Crises
Prompt v1.0
A narrative of capital rotating out of cash-generative niche compounders into AI/datacenter names — citing CCOI, IDCC, CLB, and CMTL — is largely falsified by the data. Each stock's decline traces to a distinct, event-driven catalyst: a dividend slash, a guidance step-down, a geopolitical supply shock, and speculative volatility in a micro-cap turnaround. Peer benchmarks in every relevant sector are either flat or sharply higher, ruling out broad rotation.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
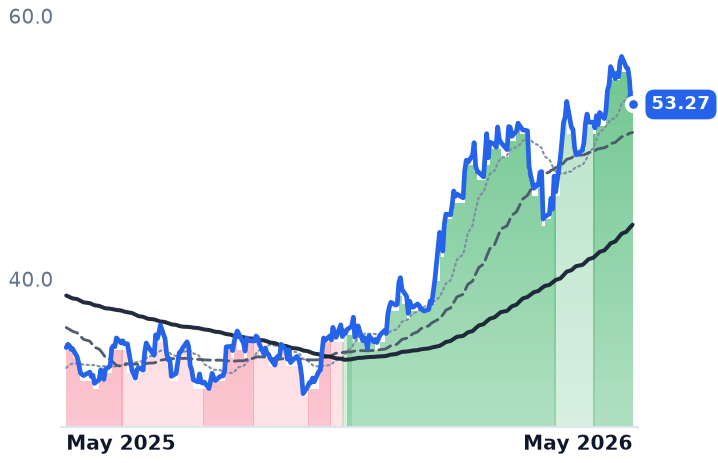
IDCC | InterDigital | Security, Compliance & Emerging Tech | ⚠️ Emerging Bear | −20.6% | +29.7% |
CCOI | Cogent Communications | Technology & Services | 🔴 Cont. Bear | −18.0% | −65.3% |
CLB | Core Laboratories | Oilfield Equipment & Tools | 🔴 Cont. Bear | −20.5% | +9.1% |
CMTL | Comtech Telecommunications | Communication Equipment | ⚠️ Emerging Bear | +6.5% | +158.6% |
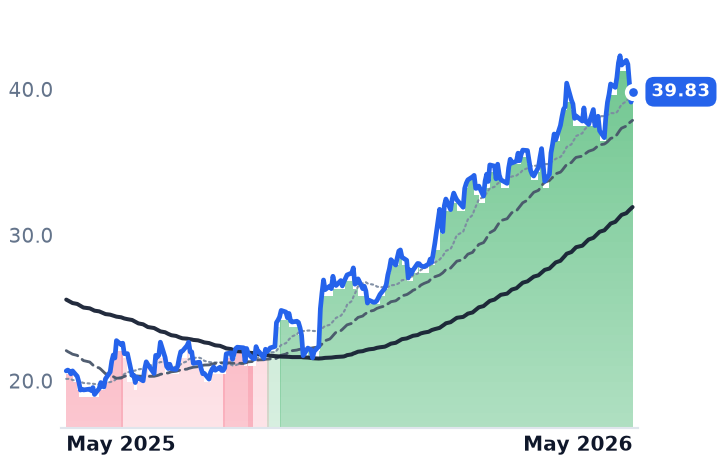
SLB | Slb | Integrated Oilfield Services | 🟢 Cont. Bull | +2.6% | +53.1% |
HAL | Halliburton | Integrated Oilfield Services | 🟢 Cont. Bull | +6.0% | +92.6% |
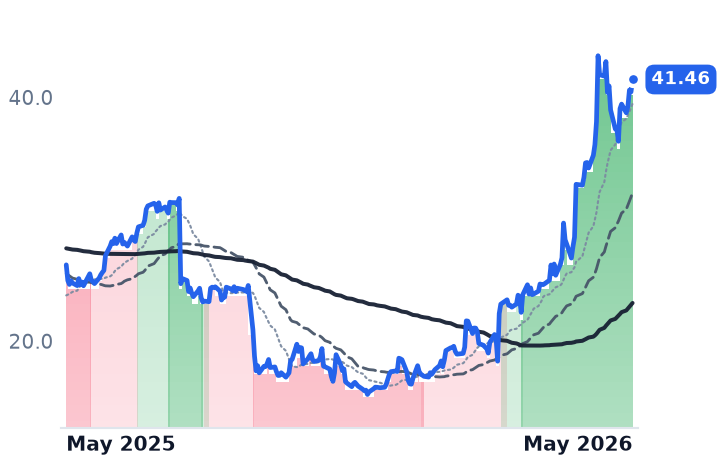
IRDM | Iridium Communications | Satellite Communications | 🌱 Emerging Bull | +21.2% | +57.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IDCC | $7.3B | 23.3x | 31.4x | 9.0x | 9.0x | 11.2x | 11.2x | 14.8x | 4.2% |
CCOI | $519.1M | n/m | — | 0.4x | 0.5x | 1.0x | 1.3x | 7.8x | -27.5% |
CLB | $468.3M | 18.1x | 21.1x | 0.9x | 0.9x | 5.0x | 5.1x | 9.7x | 2.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CMTL | $116.3M | 9.5x | — | 0.2x | 0.3x | 0.8x | 0.9x | n/m | 12.5% |
SLB | $75.9B | 24.6x | 20.6x | 2.1x | 2.1x | 12.6x | 12.4x | 12.0x | 6.0% |
HAL | $27.3B | 17.1x | 14.0x | 1.2x | 1.2x | 8.1x | 8.1x | 8.1x | 6.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IRDM | $4.8B | 29.4x | 36.0x | 5.3x | 5.1x | 6.9x | 6.8x | 13.7x | 5.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
IDCC | Revenue | −1.2% | −13.0% | +7.8% |
| EPS | −28.2% | −10.7% | +3.5% | |
CCOI | Revenue | −1.6% | +4.5% | +6.4% |
| EPS | −11.7% | −21.4% | −23.5% | |
CLB | Revenue | −1.8% | +2.8% | +6.0% |
| EPS | −34.9% | +50.9% | +33.2% | |
CMTL | Revenue | −8.8% | +4.6% | — |
| EPS | −67.3% | −16.7% | — | |
SLB | Revenue | +4.1% | +7.8% | +6.7% |
| EPS | −13.9% | +28.6% | +15.5% | |
HAL | Revenue | +2.0% | +5.4% | +4.6% |
| EPS | +3.0% | +23.2% | +16.9% | |
IRDM | Revenue | +5.5% | +4.7% | +2.9% |
| EPS | +16.3% | −18.9% | −6.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What the evidence actually shows
The four names cited in the rotation hypothesis — Cogent Communications (CCOI), InterDigital (IDCC), Core Laboratories (CLB), and Comtech Telecommunications (CMTL) — superficially resemble a cluster of mid/small-cap compounders being abandoned in favor of AI-adjacent trades. Dig into the price action and earnings records, and that narrative collapses entirely.
CCOI: A Dividend Aristocrat Thesis Reset
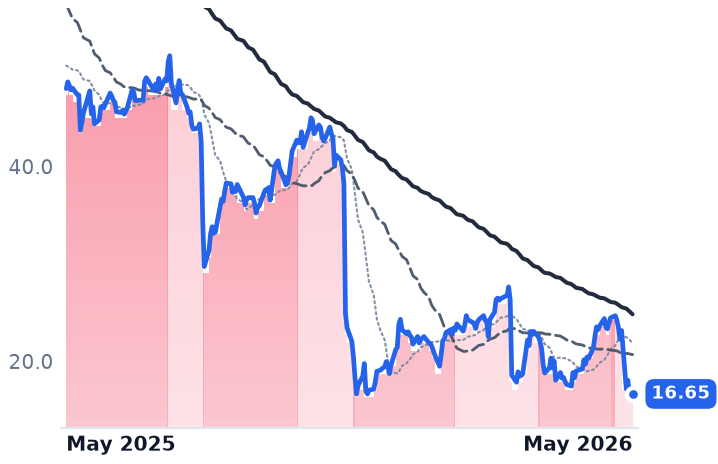
CCOI's 12-month collapse of roughly 67% (from ~$50.54 to ~$16.65) is dominated by a single session: November 6, 2025, when the stock fell ~35% in one day after Cogent slashed its quarterly dividend by 98% — from $0.985 to $0.02 per share. According to Kavout's analysis, the cut was precipitated by capital structure stress from the Sprint wireline acquisition, with gross debt/EBITDA at 7.4x and $750M of unsecured notes maturing in June 2027. The same source notes that CCOI had previously delivered 50+ consecutive quarters of dividend increases — this is a fundamental investment thesis reset from income vehicle to high-leverage infrastructure turnaround, not capital rotation. Underneath the Sprint legacy churn, the Cogent Classic business grew ~28% since acquisition closing, and Q1 2026 wavelength revenues surged 90.8% year-over-year — the operating business is improving even as the balance sheet creates overhang.
IDCC: A Guidance Step-Down, Not a Structural Crack
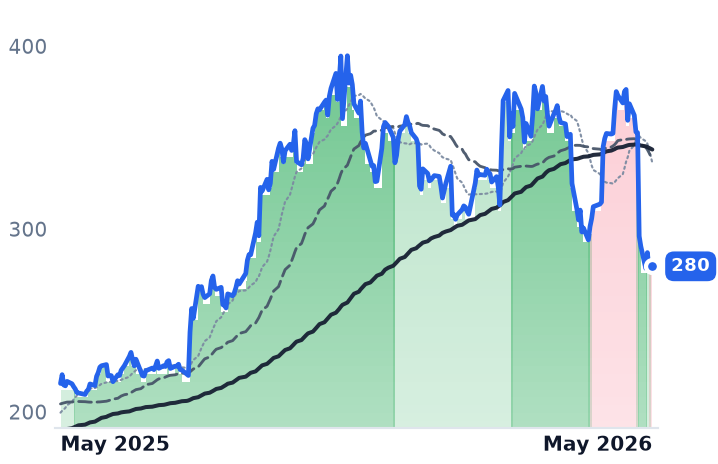
IDCC is actually UP 28.5% over 12 months — the recent ~26% pullback from a late-2025 peak reflects a specific 2026 revenue guide of $675M–$775M versus a near-record $834M in 2025, plus rising IP enforcement costs. InterDigital's Q1 2026 10-Q shows operating expenses rising 57% year-over-year, driven by $27.5M in revenue-share costs and $17.5M in IP enforcement spend tied to active litigation against Disney, Amazon, TCL, and Hisense. Short interest has risen 38.8% over 12 months to 10.7% of float, indicating the market is positioned around the guidance step-down. Yet ARR hit a record $567M (+13% YoY) in Q1 2026, the company holds $1B+ in cash, and top-3 smartphone licensees (Apple, Samsung, Xiaomi) are contracted through end of decade — the franchise is intact and the revenue dip reflects timing of catch-up payments, not structural deterioration.
CLB: A Geopolitical Supply Shock, Fully Idiosyncratic
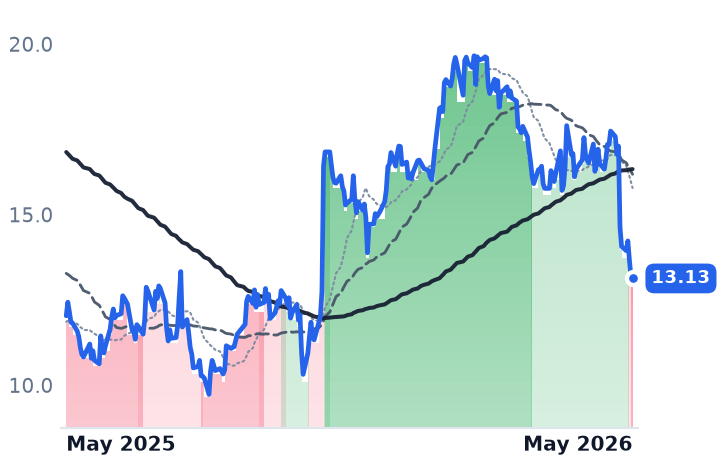
Core Laboratories is the clearest counterexample to any sector-rotation thesis. Stocktitan reported Core Lab explicitly cut Q1 2026 guidance to $119–$123M from $124–$130M after the Middle East conflict closed client offices and disrupted hydrocarbon transportation through the Strait of Hormuz. A Yahoo Finance deep-dive on Q1 results shows EPS missed consensus by 45.5% and operating margin collapsed to 1.5% from 6.3% a year prior. Meanwhile, SLB gained +48.6% and HAL gained +87.4% over the same 12-month window — the broader oilfield services sector is thriving. CLB's drop is entirely event-specific, tied to a binary geopolitical scenario where a resolution of Hormuz flows restores demand rapidly. The balance sheet is clean: 1.2x leverage, 19 consecutive years of dividends maintained.
CMTL: Speculative Volatility, Not a Compounder Selloff
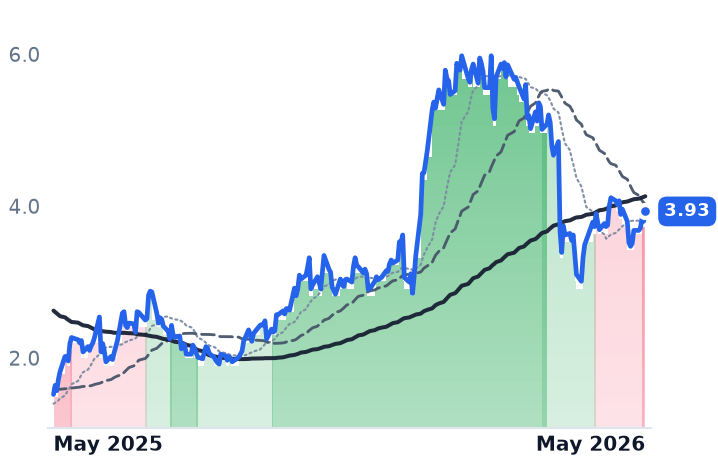
CMTL is UP 158.6% over 12 months, from $1.52 to $3.93. The 3-month pullback from ~$5.87 is a normalization of speculative excess around a restructuring thesis, not a rotation selloff. CMTL's SEC filing history confirms the company reported seven quarters of going-concern warnings and posted an FY2025 operating loss of $139M — it was never a "quality compounder." CMTL remains capital-structure-fragile: ~$228M in credit/subordinated debt plus $213M in convertible preferred liquidation preference, with covenant testing suspended through January 2027. Peer Iridium (IRDM) is up 53.7% over 12 months and +100.7% over the past month, further ruling out a satcom-sector explanation.
Why the Rotation Narrative Fails
The hypothesis predicted a "continuous gradual bleed" — the data shows discrete event-driven dislocations. CCOI's single-day 35% drop is entirely earnings/event-driven. CLB's discrete 7.4% selloff on April 30 followed a guidance cut tied to a specific geopolitical event. IDCC's move clusters around an earnings/guidance announcement. Every peer benchmark across OFS (SLB, HAL), satcom (IRDM), and fiber (Cogent Classic business) is holding flat-to-sharply higher. The "funding source rotation" framing requires a correlated, sector-independent decline — what exists instead is four separate company-specific stories that happen to share a calendar.
Valuations diverge widely: IDCC trades at 13.3x EV/EBITDA with an 8.0% FCF yield and a record ARR backlog; CLB at 8.8x EV/EBITDA with a geopolitical recovery call embedded in the thesis; CCOI at 17.8x with negative FCF yield reflecting the Sprint integration burden. The stories are distinct and require distinct analytical frameworks.