

AI Cooling Bifurcation: NVT and MOD Lead Gradual Uptrends as AAON Goes Post-Blowoff
Prompt v1.0
Within the AI2: Cooling & Thermal Management cohort, a sharp bifurcation has emerged: NVT (+48% 90d) and MOD (+25% 90d) offer the most intact gradual-uptrend setups with confirmed liquid-cooling backlog and hyperscaler design wins, while VRT's 68% run leaves it at peak valuation, AAON entered post-blowoff consolidation after its 50% one-day surge, and SPXC, ECL, PNR, and GTLS lag on structural mix grounds.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
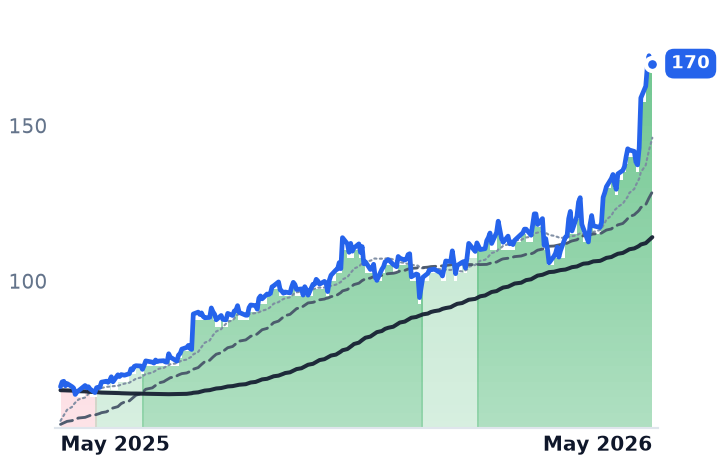
NVT | nVent Electric | Power Distribution Systems | 🟢 Cont. Bull | +30.4% | +157.4% |
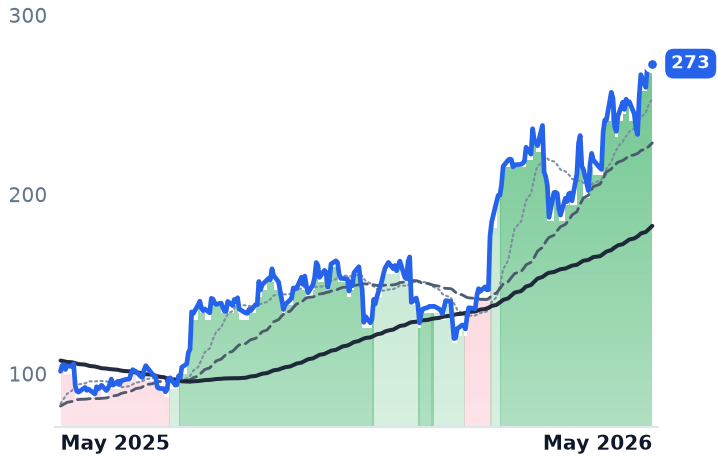
MOD | Modine Manufacturing | HVAC & Refrigeration Systems | 🟢 Cont. Bull | +13.1% | +169.2% |
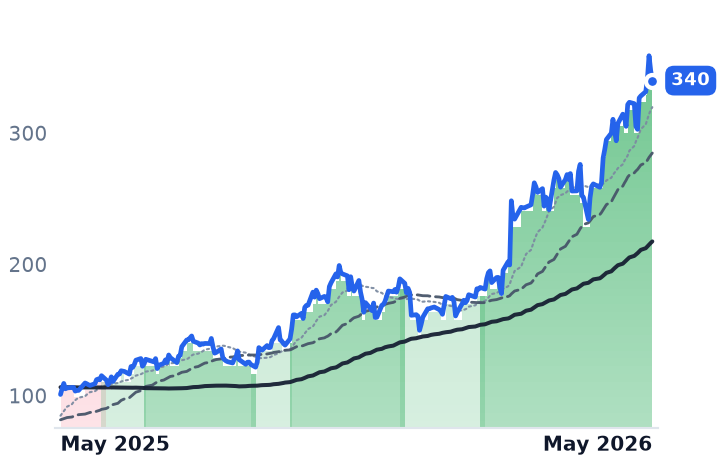
VRT | Vertiv | Advanced Power Systems | 🟢 Cont. Bull | +15.2% | +236.9% |
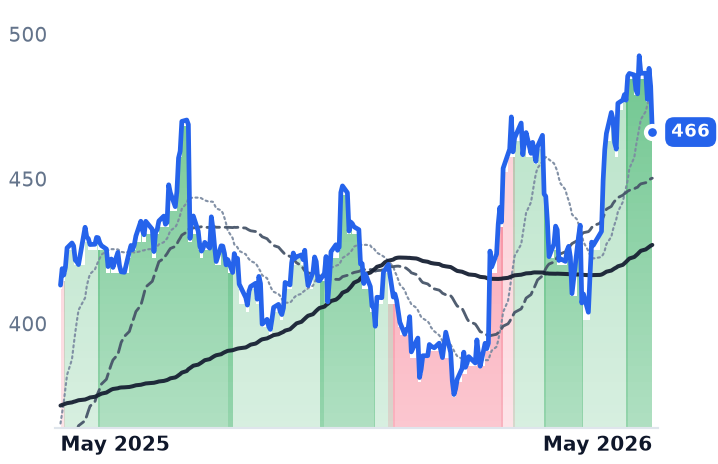
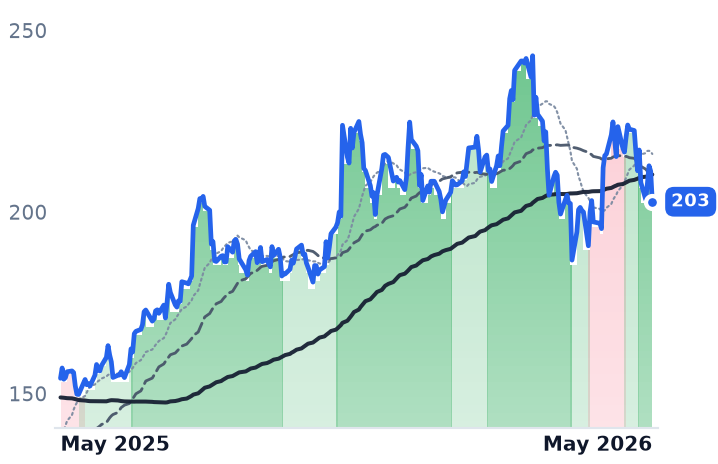
TT | Trane Technologies | HVAC & Refrigeration Systems | 🟢 Cont. Bull | +0.1% | +12.8% |
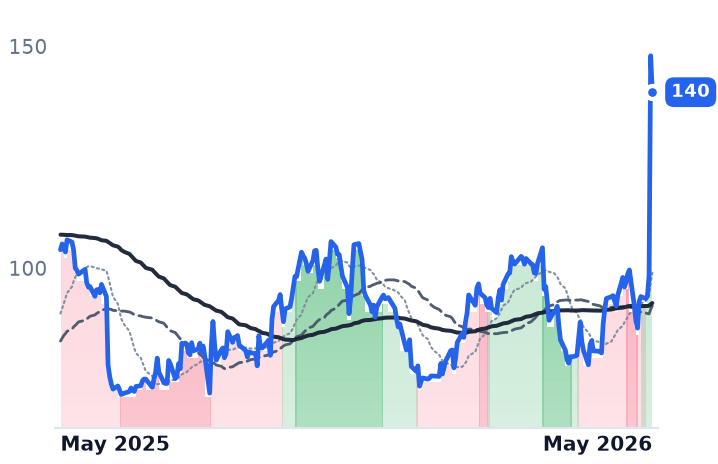
AAON | AAON | HVAC & Refrigeration Systems | 🌱 Emerging Bull | +49.9% | +34.1% |
SPXC | SPX Technologies | HVAC & Building Systems | 🟢 Cont. Bull | −6.1% | +31.5% |
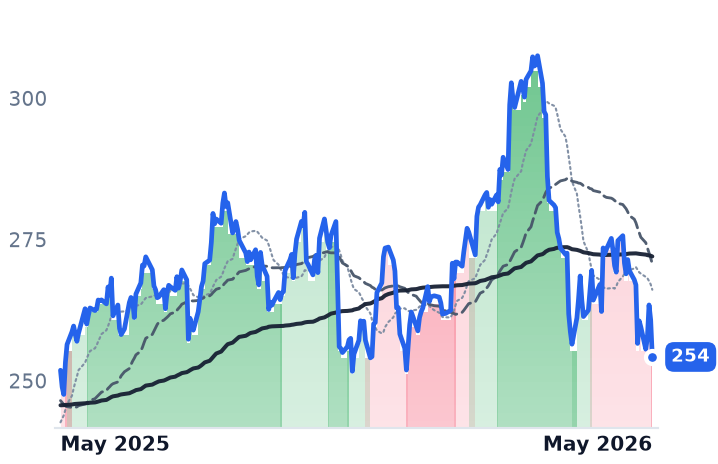
ECL | Ecolab | Water, Hygiene & Maintenance Products | ⚠️ Emerging Bear | −7.0% | +0.9% |
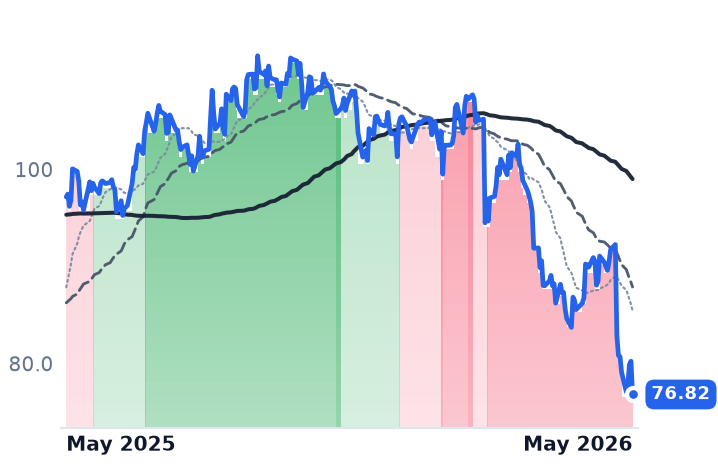
PNR | Pentair | Pumps, Valves & Filtration | 🔴 Cont. Bear | −14.6% | −20.9% |
GTLS | Chart Industries | Filtration & Separation | 🟢 Cont. Bull | −0.2% | +21.6% |
FIX | Comfort Systems USA | Building Systems | 🟢 Cont. Bull | +22.6% | +333.3% |
EME | EMCOR | Power Grid & Distribution | 🟢 Cont. Bull | +14.9% | +101.9% |
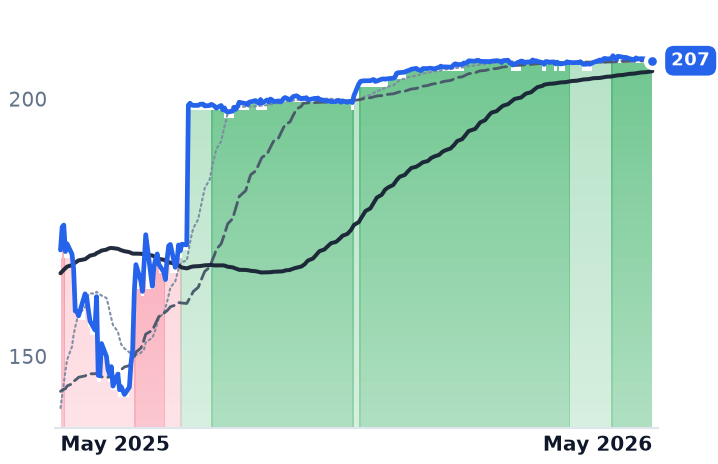
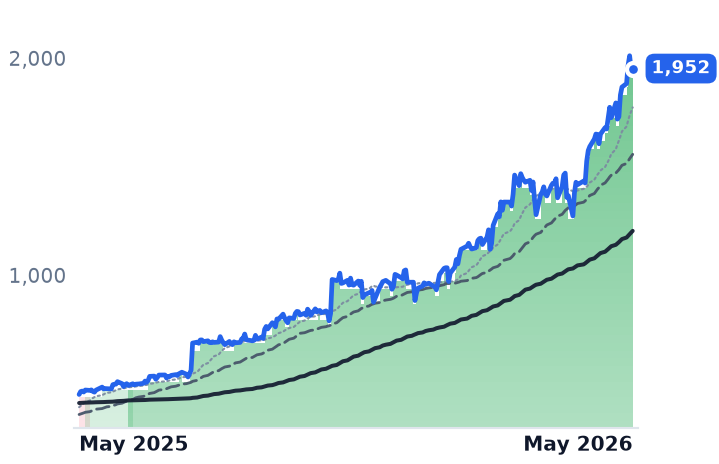
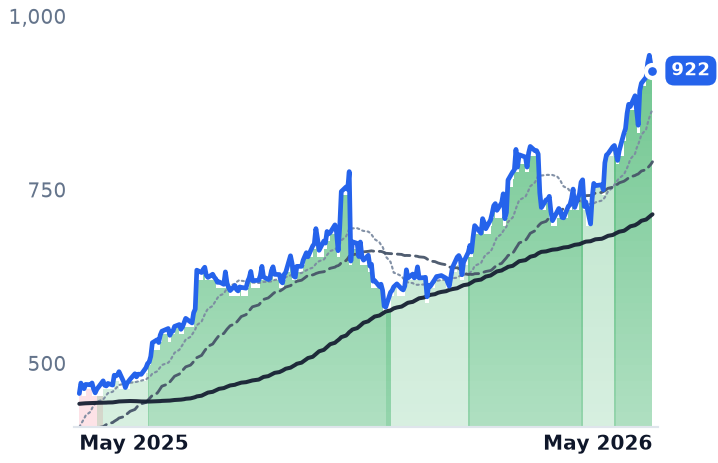
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NVT | $18.2B | 26.8x | 20.9x | 3.4x | 3.1x | 9.4x | 8.6x | 16.5x | 3.5% |
MOD | $5.1B | 40.4x | 17.5x | 1.4x | 1.6x | 6.5x | 7.2x | 17.8x | -0.7% |
VRT | $74.8B | 35.5x | 27.1x | 5.7x | 5.1x | 15.0x | 13.4x | 24.6x | 4.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TT | $87.9B | 28.3x | 26.3x | 3.8x | 3.6x | 10.8x | 10.4x | 20.5x | 4.3% |
AAON | $4.7B | 29.5x | 24.1x | 2.4x | 2.0x | 9.5x | 8.0x | 17.3x | -2.5% |
SPXC | $7.2B | 23.9x | 17.0x | 2.8x | 2.6x | 6.9x | 6.5x | 14.8x | 3.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ECL | $80.7B | 38.4x | 35.3x | 4.8x | 4.5x | 10.9x | 10.2x | 24.8x | 2.3% |
PNR | $8.3B | 13.0x | 11.2x | 2.1x | 2.1x | 5.0x | 5.1x | 10.8x | 8.1% |
GTLS | $10.0B | n/m | 30.1x | 2.4x | 2.5x | 7.7x | 7.8x | 26.0x | 0.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FIX | $34.0B | 20.8x | 18.9x | 2.7x | 2.5x | 10.6x | 9.7x | 14.2x | 7.2% |
EME | $26.1B | 17.2x | 17.1x | 1.3x | 1.2x | 6.6x | 6.3x | 10.8x | 5.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NVT | Revenue | +51.0% | +30.6% | +14.3% |
| EPS | +61.3% | +30.2% | +20.4% | |
MOD | Revenue | +22.6% | +3.7% | +34.5% |
| EPS | +33.4% | +16.0% | +73.7% | |
VRT | Revenue | +43.2% | +32.8% | +21.3% |
| EPS | +73.3% | +37.7% | +26.8% | |
TT | Revenue | +13.5% | +10.5% | +8.8% |
| EPS | +17.4% | +16.1% | +15.0% | |
AAON | Revenue | +65.9% | +17.6% | +16.0% |
| EPS | +68.5% | +51.5% | +26.4% | |
SPXC | Revenue | +23.3% | +15.6% | +9.4% |
| EPS | +24.7% | +16.3% | +12.8% | |
ECL | Revenue | +11.4% | +7.8% | +6.0% |
| EPS | +8.2% | +15.1% | +14.2% | |
PNR | Revenue | −4.8% | +11.7% | +4.1% |
| EPS | −5.0% | +11.4% | +7.2% | |
GTLS | Revenue | −6.0% | +4.7% | +3.9% |
| EPS | −37.2% | +13.9% | +19.3% | |
FIX | Revenue | +56.0% | +26.7% | +16.0% |
| EPS | +93.9% | +31.2% | +19.5% | |
EME | Revenue | +24.5% | +14.1% | +8.9% |
| EPS | +37.3% | +17.5% | +13.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The Cohort Splits Cleanly
The AI2: Cooling & Thermal Management category is no longer a monolith. Ninety-day price action across 12+ members reveals three distinct tiers: already-moved flagships at stretched valuations, gradual-uptrend names with intact runway, and structural laggards whose flatness is fundamental rather than pre-catalyst.
Tier 1 — Already Moved, Valuation Stretched: VRT gained +68% over 90 days ($202 to ~$340) and now trades at ~53x forward P/E, with trailing P/E near 83x. The underlying results are exceptional — Q1 2026 organic sales +23%, adj. EPS +83% YoY, full-year EPS guidance raised to $6.35 (+51%) — and VRT's $15B backlog (2x prior year) and book-to-bill of ~2.9x confirm the secular thesis. But at these multiples the stock has become the category's reference price rather than its best risk/reward. AAON is similarly post-spike: the stock surged roughly 50% on May 7, 2026 after a blowout Q1 — revenue of $496.9M (+54% YoY) crushed the $381M estimate, and its BASX data center backlog soared 160% to $1.62B. The 90-day gain of +41% understates the intraday spike to $147.87; the stock closed May 8 at $139.66 at ~105x trailing earnings — a genuine post-blowoff zone.
NVT: The Highest-Conviction Gradual Setup
nVent Electric gained +48% over 90 days and +34% over 30 days — a sustained, multi-month uptrend rather than a single-day event. The fundamental underpinning is direct: Q1 2026 delivered organic orders up ~40% driven by AI data center build-out, backlog grew to $2.6B (up low-double digits sequentially), and adjusted EPS rose 63% to $1.09 against prior guidance. Full-year organic sales guidance was raised to 21-23% with adj. EPS guided to $4.45–$4.55.
NVT revenue jumped 42% in Q1 as data center demand topped its own guidance, with liquid-cooling wins described as broad-based across hyperscalers, neo-clouds, and multi-tenant customers. Critically, NVT has a confirmed hyperscaler design win: the company is a participant in Google's Project Deschutes 5.0, a next-generation liquid cooling reference architecture validating NVT's CDU technology at the chip level. Earlier visibility came in Q3 2025, when organic orders were up ~65% with management confirming most of the increase came from large liquid cooling orders for hyperscaler programs with visibility into 2026 and 2027. At ~37x forward P/E on $4.48 FY2026 EPS consensus — and with backlog extending 8–12 months into 2027 — NVT is not yet at a valuation extreme for a liquid-cooling compounder guiding 27%+ organic growth.
MOD: Cheaper Multiple, Near-Term Catalyst
Modine Manufacturing gained +25% over 90 days and +16% over 30 days — a more moderate but equally sustained trend. Q3 FY2026 results showed Climate Solutions revenues up 51% YoY, data center sales up 78% YoY, and adjusted EPS of $1.19 beating the $0.99 consensus by 20%; management raised full-year FY2026 guidance to +20–25% total sales growth with data center revenue expected to exceed +70% for the full fiscal year. The multi-year target is $2B+ in DC revenue by FY2028, implying a 33%+ CAGR from $644M in FY2025.
MOD trades at ~34x forward P/E versus VRT's ~53x, offering a comparable growth rate at a meaningfully cheaper multiple. A structural catalyst is also approaching: the planned Reverse Morris Trust spinoff of Performance Technologies to Gentherm (targeted Q4 2026) will create a pure-play data center cooling vehicle valued at approximately $1.0B (6.8x trailing EBITDA), with MOD shareholders receiving 40% of the combined entity and ~$210M in cash proceeds to MOD. Before that, the Q4 FY2026 earnings report on May 27, 2026 represents a near-term data point — management guided for Q4 Climate Solutions margins recovering to ~20–21% as new production lines come online.
TT: Slower Runway, Structural Positioning
Trane Technologies gained only +1.4% over 90 days — the flattest large-cap mover in the cohort — but Q1 2026 fundamentals are stronger than the price action suggests: Americas commercial HVAC applied bookings were up 160% for the third consecutive quarter above 100%, and enterprise backlog hit a record $10.7B, up 30% vs. year-end 2025. TT expanded its thermal management stack via acquisitions: Stellar Energy Americas (modular chiller plants targeting $1B revenue in 2–3 years) and LiquidStack (chip-level CDUs) now extend its reach from conventional chillers to direct liquid cooling. Consensus analyst targets sit near $505 vs. the current ~$466 price, roughly 8% upside — meaningful but limited versus the NVT/MOD setups — and at ~31.5x forward P/E TT is near historically full valuation.
Confirmed Laggards and Why
SPXC (-9.4% 90d), ECL (-11.8%), PNR (-21.2%), and GTLS (-0.05%) are not pre-catalyst setups — their underperformance reflects structural mix: cooling tower commoditization (SPXC), industrial water/chemicals with no liquid-cooling AI upside (ECL), water treatment/flow control (PNR), and LNG/industrial gas equipment (GTLS). No confirmed liquid-cooling or direct-to-chip revenue driver was identified for any of these names.
The Bifurcation in Summary
The category has self-sorted. The violent movers (VRT, AAON) have absorbed the re-rating; the gradual setups (NVT, MOD) still carry confirmed backlog, hyperscaler design wins, and analyst targets above current prices; and the laggards reflect fundamental business-mix constraints rather than overlooked optionality.