

AMD at $455: Re-rating Confirmed, but 'Easy Money' Phase Has Passed
Prompt v1.0
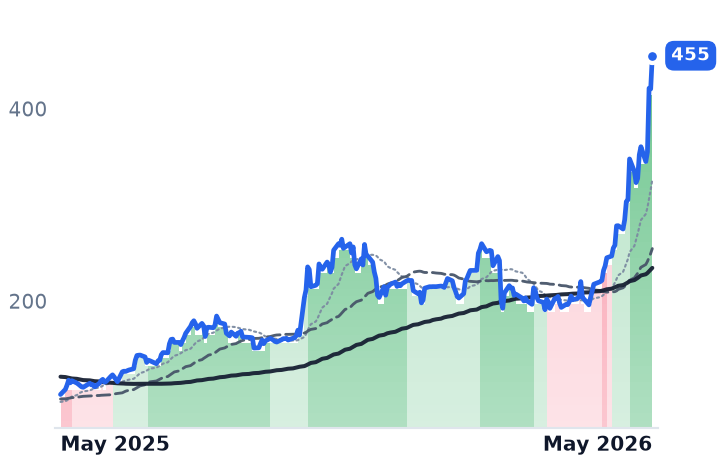
AMD's ~+96% one-month / ~+121% three-month surge to $455 is structurally supported by a blowout Q1'26 earnings print and landmark AI deals, but the stock has now crossed from 'undervalued breakout' into 'fully priced for success' territory — bull-case headroom runs to ~$500-525, with a credible bear-case mean-reversion to the $300-340s on any execution stumble.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
AMD | Advanced Micro Devices | AI & Data Center GPUs | 🟢 Cont. Bull | +92.4% | +342.6% |
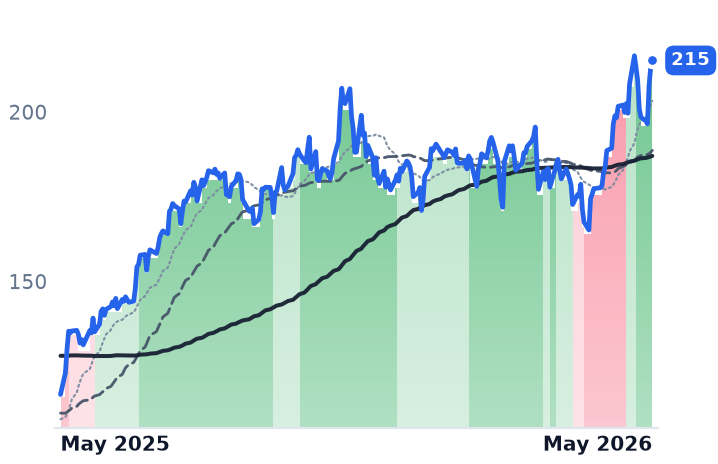
NVDA | NVIDIA | AI & Data Center GPUs | 🟢 Cont. Bull | +17.0% | +84.5% |
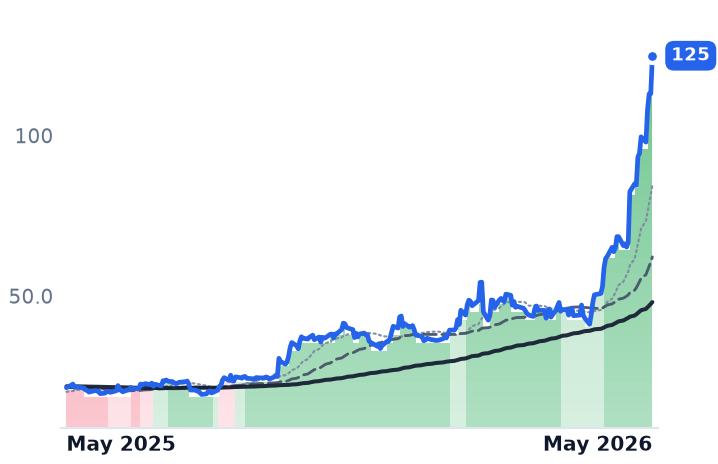
INTC | Intel | Specialty Semiconductors | 🟢 Cont. Bull | +102.4% | +483.1% |
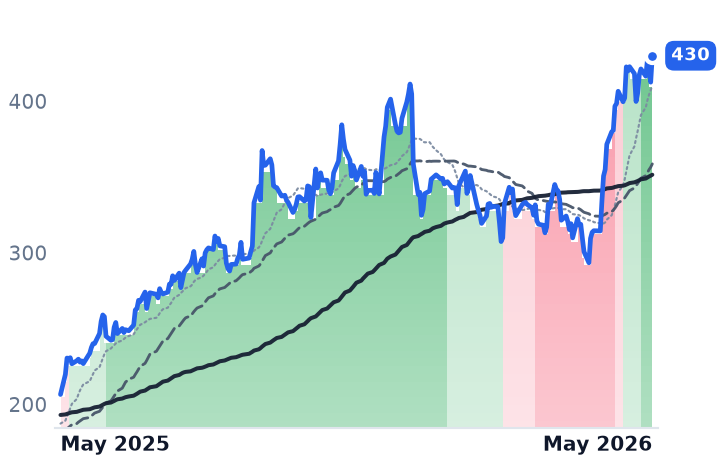
AVGO | Broadcom | Semiconductor Subsystems | ⚠️ Emerging Bear | +21.2% | +108.2% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AMD | $789.8B | 122.9x | 63.7x | 19.1x | 15.5x | 35.9x | 29.1x | 73.6x | 1.1% |
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
INTC | $546.7B | n/m | 101.3x | 10.2x | 9.4x | 28.7x | 26.5x | 50.4x | -0.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AVGO | $1.8T | 61.4x | 32.8x | 24.0x | 17.1x | 35.8x | 25.6x | 44.1x | 1.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AMD | Revenue | +49.6% | +68.8% | +37.0% |
| EPS | +91.9% | +98.7% | +42.7% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% | |
INTC | Revenue | +10.8% | +10.5% | +10.1% |
| EPS | +211.5% | +39.0% | +41.2% | |
AVGO | Revenue | +66.6% | +65.5% | +33.9% |
| EPS | +71.7% | +68.7% | +33.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What Happened
AMD's move to $455 is not a single-week squeeze — it compounded roughly +96% in one month (April 8 → May 8) and approximately +121% over three months, emerging from a ~six-month base consolidation in the $150–260 range. That base-building phase is what distinguishes AMD from the more parabolic single-catalyst squeezes seen elsewhere in semis. The trend band only flipped from mildly bullish to strongly bullish on April 24, 2026, meaning the institutional validation of this breakout is real but still very fresh.
The Fundamental Catalyst
The ignition event was Q1'26 earnings on May 5: revenue of $10.25B (+38% YoY), data center revenue +57% YoY, and Q2 guidance of $11.2B (+46% YoY). Those are not incremental beats — they are a step-change in the trajectory of AMD's AI accelerator business.
Underpinning the guide, management has disclosed a cluster of gigawatt-scale partnerships that go beyond the typical "design win" language:
- Meta: A 6GW MI450 deal that includes up to 160 million AMD warrant shares — a structural alignment, not a spot purchase.
- OpenAI: A 6GW partnership announced alongside the Meta deal, extending AMD's GPU footprint into one of the highest-velocity AI training environments.
- Oracle: A 50,000-GPU Helios supercluster commitment, providing hyperscaler credibility beyond the usual Meta/Microsoft axis.
- Management has also raised its server CPU TAM estimate to $120B by 2030 and framed a strategic target of >$20 EPS, implying the datacenter GPU ramp is intended to compound alongside — not instead of — the core CPU business.
Valuation: The Tension
Here is where the thesis gets complicated. The re-rating has been so fast that AMD now trades at:
- Trailing P/E ~133x
- Forward P/E ~56x on FY26 consensus EPS of ~$7.27
- Forward P/S ~13.5x
Consensus sell-side price targets had clustered around $289–290 pre-earnings. The fastest-moving bulls (Bernstein, Barclays, Cantor, BofA) have since raised targets into the $450–525 range; Jefferies sits more measured at $415. AMD has already printed through the pre-earnings consensus PT and is now threading the needle between updated bull targets.
Insider Activity: Structural, Not Directional
Insiders — Lisa Su, Hu, Norrod, Papermaster, Grasby — have been net sellers all year under 10b5-1 plans. Sale prices ($162–219) were executed well below today's $455 print, so this reads as systematic diversification rather than a conviction topping signal. There has been no insider buying on record. Neither fact is particularly alarming, but neither is it a green light.
The Remaining Question
The original AI-GPU re-rating thesis for AMD was predicated on share-gain against NVDA being underpriced. At $455, that narrative appears substantially priced in. The incremental bull case now requires: (1) successful MI450 ramp at the gigawatt scale Meta and OpenAI have committed to, and (2) at least one additional major hyperscaler commitment to sustain the revenue trajectory that the $11.2B Q2 guide implies is already baking in.
The upside scenario (~$500–525) is achievable if execution is clean. The risk scenario (~$300–340) would materialize on any supply-chain delay, yield miss in the MI450 program, or a macro environment where hyperscalers throttle capex. AMD has moved from 'easy share-gain narrative' to 'execution story' — a distinction that matters for how much margin of safety remains at current prices.