

RKLB vs. POET: One Fundamental Re-Rating, One Speculative Bounce
Prompt v1.0
Rocket Lab's +27% five-day surge is backed by record earnings, a $2.2B backlog, and major defense wins — a genuine re-rating, not sector rotation. POET's +54% bounce sits on shakier ground: a cancelled Marvell purchase order, active securities litigation, and meme-driven volatility. The two moves look similar on a chart but are structurally worlds apart.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
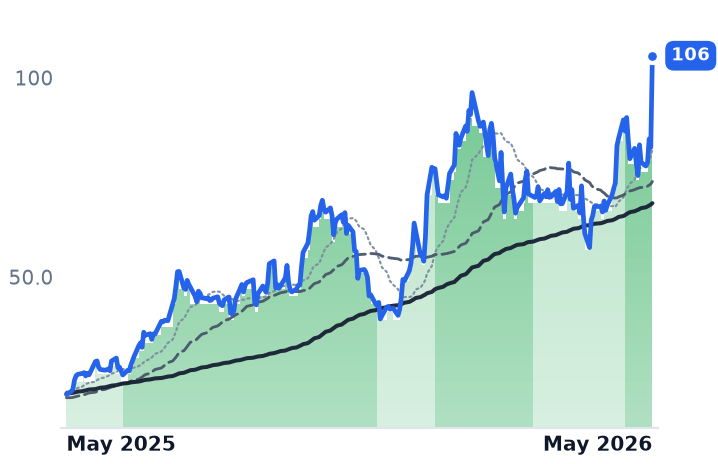
RKLB | Rocket Lab USA | Unmanned Systems & ISR | 🟢 Cont. Bull | +58.1% | +414.6% |
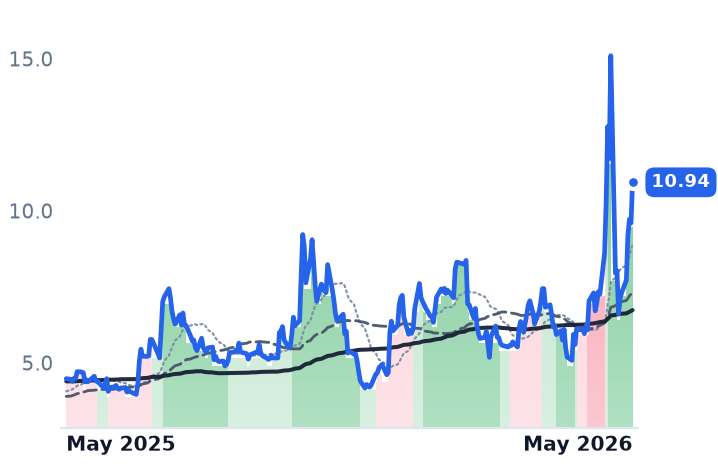
POET | POET Technologies | Discrete & Power | 🟢 Cont. Bull | +79.9% | +144.1% |
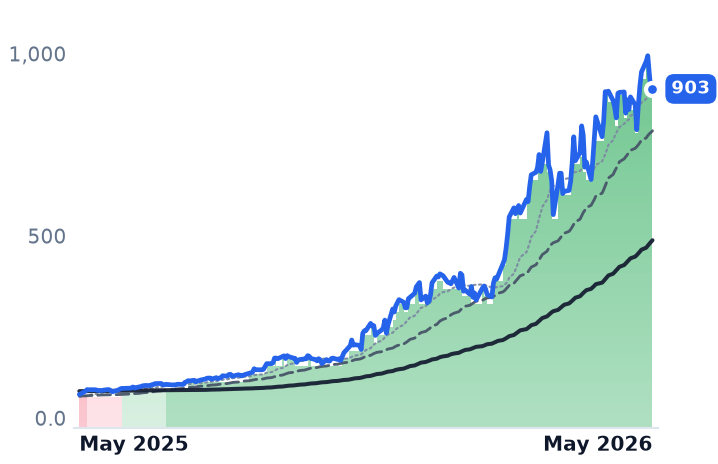
LITE | Lumentum | Optical Transport & Switching | 🟢 Cont. Bull | +1.0% | +1292.7% |
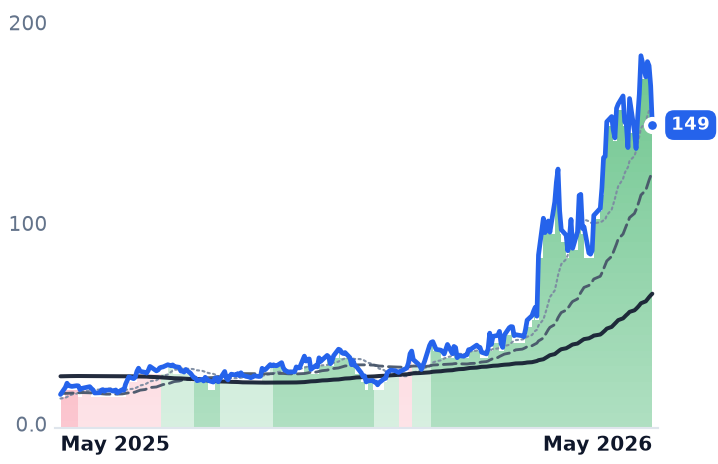
AAOI | Applied Optoelectronics | RF & Wireless | 🟢 Cont. Bull | +11.7% | +915.3% |
PL | Planet Labs PBC | Unmanned Systems & ISR | 🟢 Cont. Bull | +14.1% | +996.6% |
SATL | Satellogic | Specialty Manufacturing & Components | 🌱 Emerging Bull | +5.1% | +77.3% |
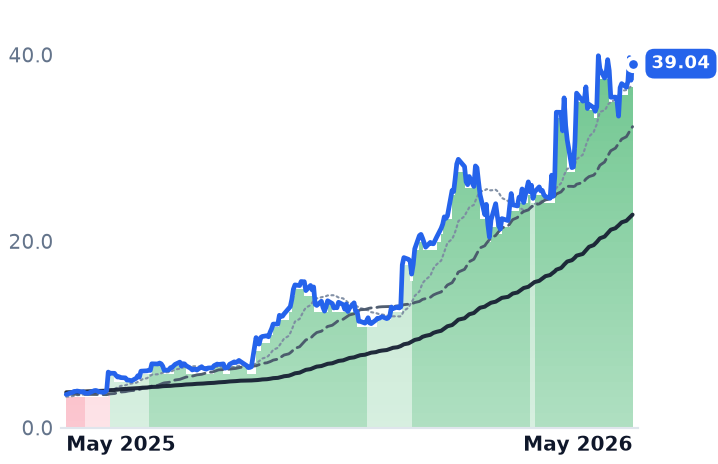
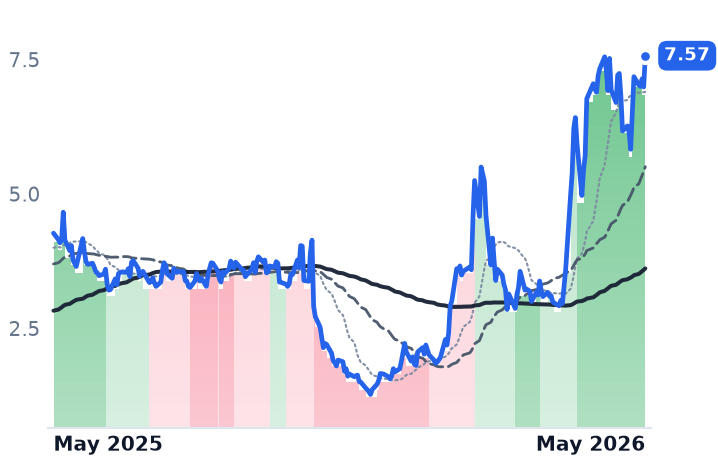
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RKLB | $72.2B | n/m | — | 106.3x | 79.7x | 290.7x | 218.0x | n/m | -0.4% |
POET | $1.2B | n/m | — | 724.4x | 137.5x | — | — | n/m | -3.3% |
LITE | $75.4B | n/m | 52.1x | 25.0x | 13.3x | 60.0x | 31.9x | n/m | 0.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AAOI | $12.4B | n/m | 149.9x | 20.9x | 11.9x | 72.1x | 41.3x | n/m | -3.3% |
PL | $8.2B | n/m | — | 24.5x | 18.8x | 44.1x | 34.0x | n/m | 0.6% |
SATL | $798.4M | n/m | — | 25.0x | 18.2x | 31.7x | 23.0x | n/m | -5.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
RKLB | Revenue | +51.0% | +39.0% | +27.0% |
| EPS | −41.8% | −100.1% | +68844.3% | |
POET | Revenue | +684.9% | +609.0% | +1.6% |
| EPS | −8.9% | −41.2% | −113.3% | |
LITE | Revenue | +83.9% | +89.0% | +54.6% |
| EPS | +314.0% | +125.9% | +58.9% | |
AAOI | Revenue | +129.8% | +169.3% | +48.7% |
| EPS | −417.3% | +454.2% | +102.6% | |
PL | Revenue | +21.9% | +46.2% | +30.7% |
| EPS | −56.0% | +25.8% | −78.2% | |
SATL | Revenue | +186.7% | +39.1% | +47.4% |
| EPS | +192.5% | −93.6% | −25.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What's Happening
Both RKLB and POET posted eye-catching five-day gains through May 8, 2026, but the evidence pack makes clear these are not two versions of the same story.
RKLB climbed from $83.18 to $105.47 — a +26.8% move on 76 million shares traded on May 8 alone, versus a typical 15–20 million daily float. The catalyst was unmistakable: blowout Q1 2026 results showing record $200.3M revenue, up 63.5% year-over-year, surpassing every guidance metric including revenue, margin, and adjusted EBITDA. Gross margins expanded to 38.2% GAAP / 43% non-GAAP in Q1, up from 26.6% GAAP just two years ago.
POET rose from $7.12 to $10.95 — a +53.8% move. But the 30-day chart tells a darker story: POET spiked to $15.10 on April 24, then crashed 47.2% to $7.97 on April 27 after Marvell Technology cancelled the purchase orders that a POET CFO had publicly confirmed. The current bounce is being driven by WallStreetBets attention, leveraged ETF amplification, and elevated options flow, not new fundamentals. POET's 30-day range was $6.08–$15.10 (148% peak-to-trough); RKLB's was $66.74–$105.47 (58%). Same five-day return, radically different volatility profiles.
The RKLB Case: Execution Driving Re-Rating
The earnings report came loaded with catalysts beyond the revenue beat. RKLB's total backlog hit $2.2B in Q1 2026 — up 20% sequentially and 108% year-over-year — split 41.5% launch and 58.5% space systems. The company announced its largest contract ever: five Neutron flights plus three Electron missions through 2029 for a confidential customer.
Defense momentum is accelerating. RKLB was selected alongside Raytheon for a Golden Dome Space-Based Interceptor demonstration, plugging it directly into the $185B missile defense program. Separately, a $30M multi-launch HASTE hypersonic contract from Anduril means HASTE missions now represent roughly one-third of a 70+ launch backlog when combined with a prior $190M TRMC order.
Q2 2026 guidance of $225M–$240M — midpoint $232.5M — sits materially above the prior $205M Street consensus, implying 16% sequential growth. CFRA reaffirmed a Strong Buy and raised its 12-month price target from $80 to $100 (note: stock has already surpassed $100 post-earnings). RKLB also announced the acquisition of Motiv Space Systems and closed the Mynaric laser optical terminal deal, deepening vertical integration ahead of SDA program deliveries. The company ended Q1 with $1.48B in cash and over $2B in total liquidity with substantially no debt.
Neutron carries a real risk flag: a Stage 1 tank rupture during hydrostatic testing in January 2026 pushed first flight to Q4 2026. This is the third Neutron slip, and at ~52x forward sales the stock prices in considerable execution. But the backlog acceleration and margin expansion provide a genuine fundamental floor that wasn't there a year ago.
Critically, the space cohort confirms this is idiosyncratic: PL gained +7.1% and SATL gained +16.5% over the same five-day window — well below RKLB's move, not suggestive of a broad sector melt-up lifting all boats.
The POET Case: Real Technology, Fragile Setup
POET's underlying technology — a photonic interposer platform enabling co-packaged optics — addresses a real and growing market. NVIDIA shipped Quantum-X InfiniBand switches with CPO in late 2025, and Spectrum-X switches with the Rubin AI platform are expected H2 2026, validating the addressable opportunity. POET's November 2025 collaboration with Quantum Computing Inc. targets 3.2 Tbps optical engines for CPO and AI data centers with an H2 2026 delivery window. Partnerships with Foxconn, Luxshare, LITEON, and Lessengers on 1.6T transceiver modules show real industry interest in the platform.
The commercial execution gap, however, is enormous. POET's 2025 full-year revenue was $1.07M — entirely NRE and licensing, with no product revenue at scale. The sole analyst forward estimate for 2026 is $10M, implying a forward P/S of ~117x at the current $1.17B market cap. First profitable year is not projected until 2027. The Marvell cancellation episode has also triggered active securities class action lawsuits alleging misrepresentations around the NDA breach and PFIC tax disclosures. The window to prove pilot-to-production scale is narrowing as the CPO market consolidates between suppliers who can demonstrate yields by 2027.
Optical comps AAOI (-9.4%) and LITE (-0.8%) declined over the same window, further isolating POET's bounce as sentiment-driven rather than photonics-sector driven.
The Divergence in One Line
RKLB's five-day move reflects a fundamental re-rating anchored in record revenue, backlog acceleration, defense contract wins, and a Q2 guide well above consensus. POET's five-day move reflects a partial recovery from a 47% crash caused by a cancelled anchor customer order, amplified by retail momentum. The optical cohort's weakness while POET bounced is a telling tell.