

POET Technologies: Speculative Rebound or Catch-Up Trade? The Evidence Is Mixed
Prompt v1.0
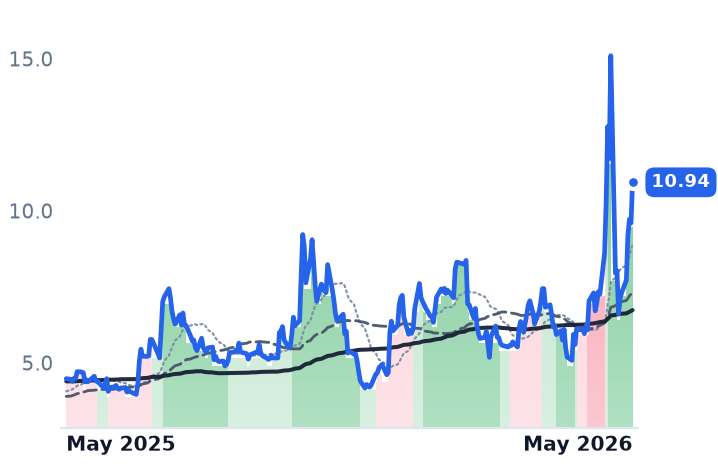
POET's apparent 5-day/1-month breakout is an artifact of a +107% spike and -47% crash driven by a governance failure (Marvell order cancellation), not a clean technical breakout. With ~$430M in cash, genuine technology awards, and sector tailwinds from large-cap peers, POET has structural support — but serial dilution, pre-revenue financials, class-action investigations, and a Zacks fair-value estimate below current price make this a high-risk speculative story, not a straightforward catch-up trade.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
POET | POET Technologies | Discrete & Power | 🟢 Cont. Bull | +79.9% | +144.1% |
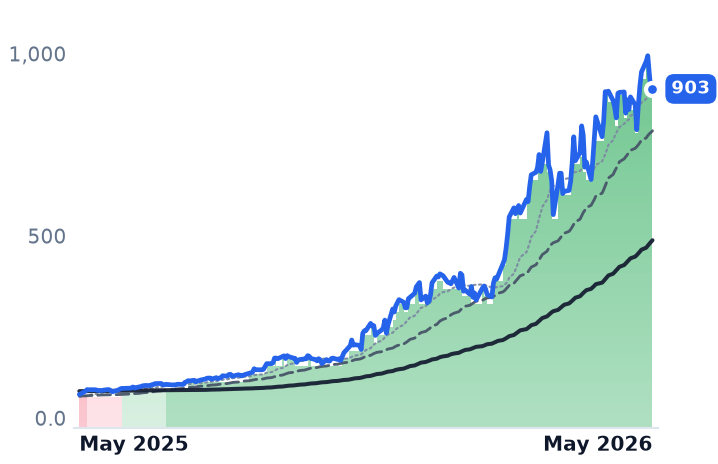
LITE | Lumentum | Optical Transport & Switching | 🟢 Cont. Bull | +1.0% | +1292.7% |
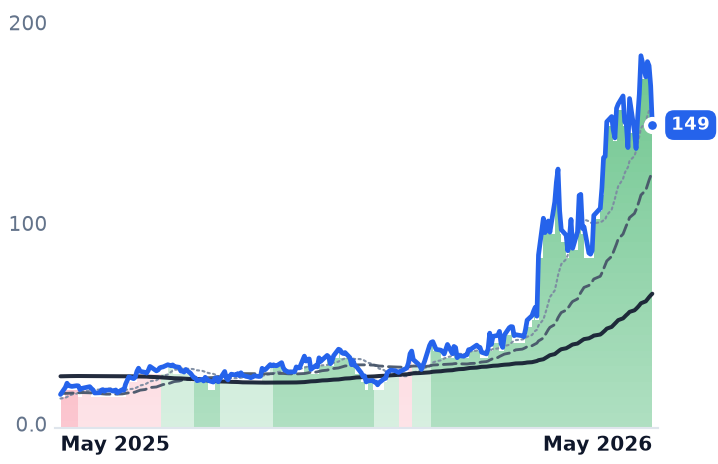
AAOI | Applied Optoelectronics | RF & Wireless | 🟢 Cont. Bull | +11.7% | +915.3% |
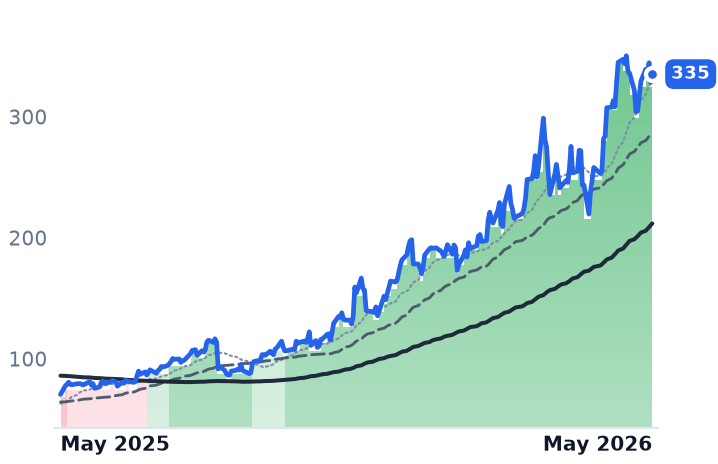
COHR | Coherent | Instrumentation & Test Equipment | 🟢 Cont. Bull | +18.0% | +375.1% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
POET | $1.2B | n/m | — | 724.4x | 137.5x | — | — | n/m | -3.3% |
LITE | $75.4B | n/m | 52.1x | 25.0x | 13.3x | 60.0x | 31.9x | n/m | 0.7% |
AAOI | $12.4B | n/m | 149.9x | 20.9x | 11.9x | 72.1x | 41.3x | n/m | -3.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
COHR | $68.7B | 80.7x | 42.0x | 9.7x | 7.1x | 25.7x | 18.9x | 53.7x | -85.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
POET | Revenue | +684.9% | +609.0% | +1.6% |
| EPS | −8.9% | −41.2% | −113.3% | |
LITE | Revenue | +83.9% | +89.0% | +54.6% |
| EPS | +314.0% | +125.9% | +58.9% | |
AAOI | Revenue | +129.8% | +169.3% | +48.7% |
| EPS | −417.3% | +454.2% | +102.6% | |
COHR | Revenue | +21.9% | +37.7% | +38.2% |
| EPS | +55.9% | +53.4% | +58.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What Actually Happened to the Price
The framing of POET (TSX-V: PTK / OTC: POETF) as a "gradual breakout" misreads the price action almost entirely. POET surged from ~$7.26 (Apr 17) to $15.10 (Apr 24) — a +107% move in five sessions — then collapsed -47.4% on Apr 27 after Marvell Semiconductor, which acquired Celestial AI, cancelled ALL purchase orders citing an alleged confidentiality breach. The current price of ~$10.95 (May 8) is a recovery from the crash, not an organic breakout from a depressed base.
The governance context is damaging: the cancellation was reportedly triggered by POET's own CFO publicly disclosing confidential order details in a Stocktwits TV interview, a self-inflicted wound that raises real questions about management discipline. Volume in the recovery phase (82M shares May 5, 68M May 6, 71M May 8) dwarfs the pre-spike average of ~8–10M daily — consistent with retail-driven speculation, not institutional accumulation.
Adding to the overhang, multiple securities class action investigations have been filed by law firms including Schall, Block & Leviton, and Johnson Fistel for potential misleading disclosures.
Fundamentals: Cash-Rich, Revenue-Starved
POET reported FY2025 revenue of just $1.07M against a net loss of $62.96M — essentially pre-revenue at commercial scale. At ~$10.95/share the stock trades at roughly 1,086x trailing sales and ~116x forward 2026 consensus revenue of ~$10M (single-analyst estimate). The forward ramp to $80M in FY2027 is extremely steep and requires successful hyperscaler-grade qualification, volume manufacturing ramp in Malaysia, and new customer wins.
However, the cash position provides a genuine structural floor. POET raised approximately $375M in equity during Q4 2025 and added another $150M in January 2026, resulting in ~$430M cash. With Q4 2025 cash operating burn of ~$11.6M, that implies 9+ years of runway at current rates — the most credible bull-case pillar.
The cost: serial dilution. Shares outstanding grew from ~46.5M (Q1 2024) to ~93.2M by Q4 2025. The October 2025 $150M registered direct offering caused a ~10% single-day drop; the January 2026 $150M offering caused a ~13–17% single-day decline — a consistent dilution-driven negative price pattern that shareholders must price in.
Technology Credentials vs. Revenue Reality
POET's technology differentiation is genuine. The POET Teralight 1.6T optical engine won Best AI Hardware Innovation at the 2025 AI Breakthrough Awards, competing against much larger players, and POET won its 7th industry award in 15 months at ECOC 2025 in Copenhagen. The partnership pipeline is active — Semtech for 1.6T receivers, QCi for 3.2 Tbps TFLN-based optical engines, and Sivers Semiconductors on AI datacenter light engines. Management is guiding for 30,000+ optical engine shipments in 2026 with Malaysia manufacturing readiness for high-volume 800G engines in Q3 2026 per investor relations summaries.
But none of these partnerships have converted to material revenue. The new $5M+ POET Infinity production order from an unnamed technology company — disclosed after the Marvell cancellation — is directionally positive but orders of magnitude below what the stock's implied revenue trajectory demands.
Peer Context: Sector Tailwind Is Real, but POET Is a Different Animal
Large-cap photonics peers remain in confirmed strongly bullish signal bands: LITE is up ~94% in three months ($465 → $903), AAOI is up ~273% ($39.90 → $148.94), and COHR is up ~59% ($211 → $335). The sector tailwind from hyperscaler AI buildout is not in question. The issue is whether POET is a clean catch-up or a late-cycle micro-cap echo with its own idiosyncratic risks.
The Zacks sell-side model (the only disclosed coverage) values POET at ~$9.65/share on FY2027 revenue estimates of $80M at 11.6x EV/Sales — implying current prices are at or above the most optimistic fundamental scenario. The May 1, 2026 launch of the Defiance Daily Target 2X Long POET ETF (POEL) signals meme-stock-adjacent retail dynamics that can amplify moves in both directions. PFIC tax status (Canadian domicile) adds a structural headwind for US taxable accounts, though management has announced plans to redomicile.
The Honest Scorecard
| Factor | Bullish | Bearish |
|---|---|---|
| Cash runway | ~9+ years at current burn | Achieved via 2x share count in 18 months |
| Technology | 7 industry awards in 15 months | Near-zero commercial revenue |
| Sector peers | LITE/AAOI/COHR all strongly bullish | POET not in same quality tier |
| Catalysts | Malaysia ramp, 800G volume (Q3 2026) | Marvell cancellation removed biggest near-term revenue event |
| Governance | Redomicile positive | CFO confidentiality breach; class actions |
| Valuation | $430M cash partially offsets market cap | 1,086x trailing sales; above Zacks fair value |
The thesis is not broken — the technology is differentiated and the sector is right. But calling this a "gradual breakout" obscures that the current price is a speculative recovery from a governance-induced crash, with the prior near-term revenue catalyst gone and valuation already stretched against the only disclosed sell-side model.