

Cloud Dev-Tools Bifurcation: Earnings Catalysts Split AI Winners from Legacy Laggards
Prompt v1.0
A sharp intra-cohort split has opened in cloud infrastructure / developer tools, anchored to Q1 FY26 earnings: DDOG surged on genuine AI re-acceleration while FSLY and KVYO cratered on structural and guidance concerns. AKAM and FROG rode DDOG's coattails, making their moves harder to sustain.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
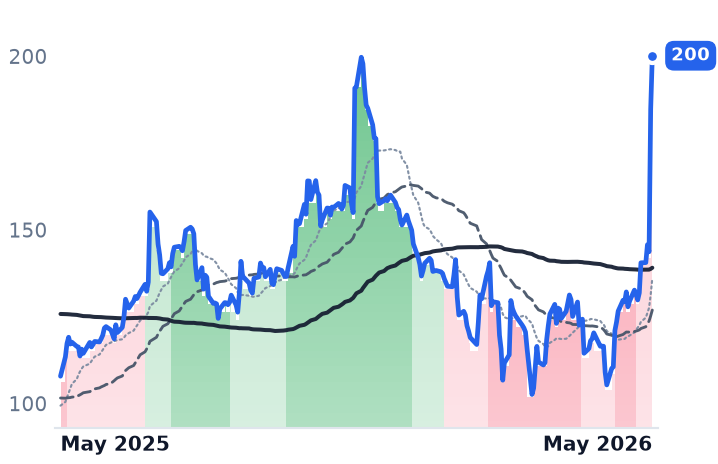
DDOG | Datadog | Data & Analytics Platforms | ⚠️ Emerging Bear | +83.7% | +85.5% |
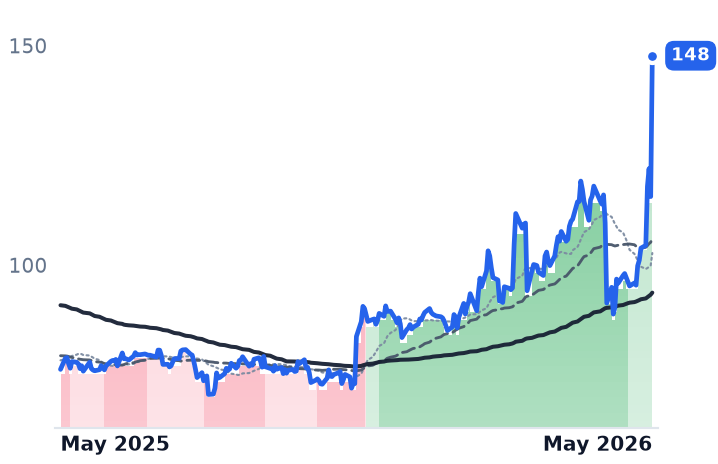
AKAM | Akamai Technologies | Network & Application Delivery | 🌱 Emerging Bull | +34.8% | +93.7% |
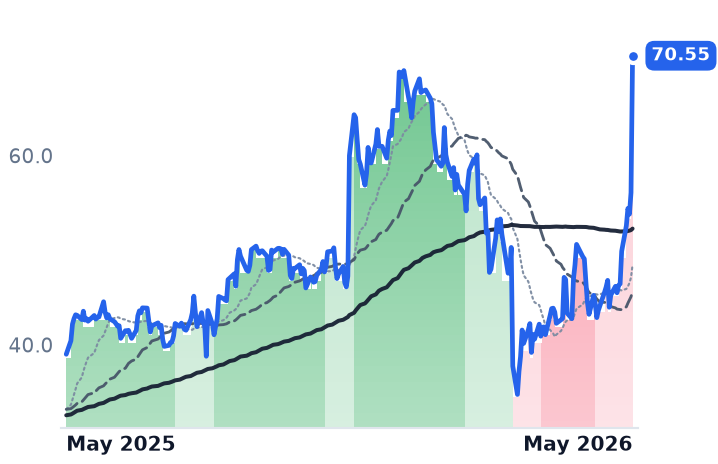
FROG | JFrog | Developer Tools & DevOps | ⚠️ Emerging Bear | +58.7% | +80.9% |
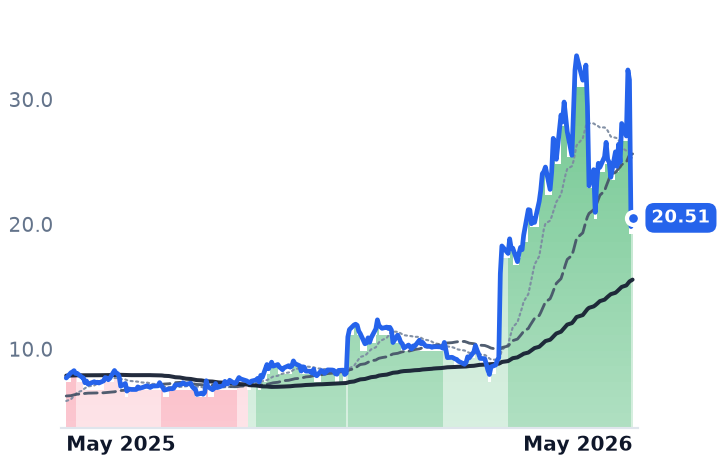
FSLY | Fastly | Cloud Infrastructure & Platform | 🟢 Cont. Bull | −30.4% | +167.1% |
KVYO | Klaviyo | Marketing Automation | 🔴 Cont. Bear | −14.5% | −54.4% |
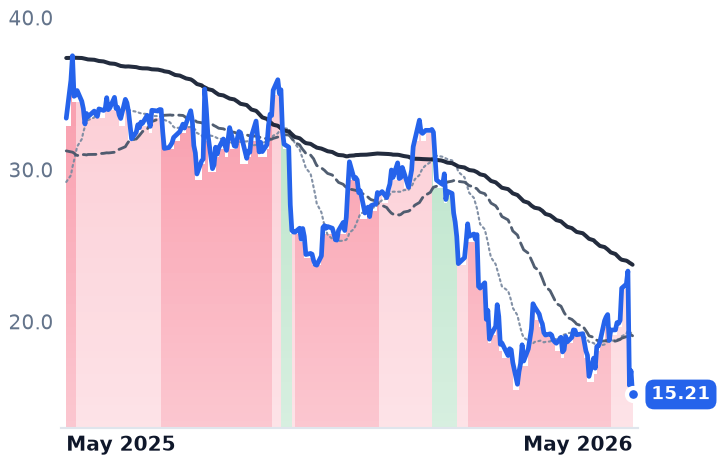
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DDOG | $88.0B | 497.4x | 101.3x | 22.2x | 20.1x | 27.9x | 25.3x | 337.6x | 1.3% |
AKAM | $16.7B | 40.6x | 17.2x | 3.9x | 3.7x | 6.9x | 6.6x | 19.1x | 3.8% |
FROG | $11.1B | n/m | 96.0x | 18.5x | 17.5x | 23.8x | 22.5x | n/m | 1.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FSLY | $4.7B | n/m | 58.7x | 6.8x | 6.3x | 11.1x | 10.3x | n/m | 0.9% |
KVYO | $5.7B | n/m | 22.3x | 4.3x | 3.7x | 5.8x | 5.0x | 309.0x | 4.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DDOG | Revenue | +28.9% | +21.5% | +23.5% |
| EPS | +20.9% | +17.3% | +23.1% | |
AKAM | Revenue | +7.4% | +11.0% | +10.4% |
| EPS | −5.0% | +6.5% | +11.1% | |
FROG | Revenue | +20.6% | +17.5% | +19.4% |
| EPS | +20.4% | +17.6% | +27.4% | |
FSLY | Revenue | +20.6% | +11.9% | +10.6% |
| EPS | +870.1% | +11.5% | +13.1% | |
KVYO | Revenue | +24.8% | +19.5% | +18.4% |
| EPS | +31.2% | +22.3% | +23.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What's Happening
The five-day moves across DDOG (+42%), AKAM (+41%), FROG (+34%), FSLY (-24%), and KVYO (-32%) look like a clean sector rotation on the surface, but the mechanics underneath are more specific — and more important — than a simple AI-vs-legacy narrative.
The pivot point was May 7, when Datadog reported Q1 FY26 results that were genuinely transformational: revenue climbed 32% year-over-year to $1.01B, and full-year FY26 guidance was lifted from $4.06–4.10B to $4.30–4.34B, with management citing AI-native workload acceleration and new logo bookings doubling year-over-year as the core drivers. The stock jumped ~29% on the single session. That is a catalyst-anchored move — the kind of earnings print that rewires how the market prices a name going forward.
The Laggards: Two Different Failure Modes
Fastly and Klaviyo both technically beat and raised — yet both were punished hard, which tells you the market was already pricing in perfection.
FSLY fell roughly 38% on May 7. The issue: Network Services revenue decelerated to 11% YoY growth even as security and edge-compute held up. The stock had approximately tripled year-to-date heading into the print, so the valuation reset on forward growth fears was brutal. The core CDN business is structurally slower, and no amount of security upside fully offsets that narrative.
KVYO dropped ~32% on May 6. Two simultaneous shocks: CFO Amanda Whalen announced her departure, and Q2 guidance implied a deceleration to 23–24% growth from the 28% posted in Q1. Carrier fee absorption is compressing future margins. Neither issue is a one-quarter blip.
How Much Runway Remains for the Winners?
This is where the evidence pack introduces important differentiation.
DDOG at ~16x forward EV/sales is still elevated by historical standards, but the re-acceleration thesis is real — revenue growth is reaccelerating into AI workloads, not flatlining. The multiple is harder to dismiss when the underlying business is inflecting upward.
AKAM at ~3.8x forward sales is the cheapest re-rating candidate in the cohort. The Akamai Connected Cloud (Linode lineage) and Cloud Innovation Suite are guiding to 45–50% CIS growth for 2026, and the security segment has been a steady compounder. Critically, AKAM's +28% move on May 8 came after DDOG's print, in sympathy — not on its own catalyst. That distinction matters for durability.
FROG at ~11x forward sales carries the most asymmetric risk in the cohort. JFrog's artifact-management-for-AI angle is a legitimate story, but the +26% May 8 move was also sympathy-driven, and there are open questions about how much AI-native development tooling actually displaces or accelerates JFrog's use case versus competing with it.
Why It Matters
The bifurcation is part fundamental, part expectations mismatch. DDOG's move is the most defensible: genuine revenue re-acceleration, raised guidance, and AI-workload commentary that goes beyond marketing language. FSLY and KVYO's declines reflect real business-model friction, not just valuation reset.
The sympathy moves in AKAM and FROG are the more vulnerable legs of this trade. Investors who rode them up in the 24–48 hours post-DDOG's print are now holding positions with less fundamental anchor. Whether those moves consolidate or fade depends on whether each name can produce its own AI-infrastructure catalyst on its own earnings cycle — not borrowed conviction from a neighbor's quarter.
The structural story — AI-observability and artifact management pulling ahead of legacy CDN and marketing automation — appears durable. The pricing of that story, for AKAM and FROG specifically, moved very fast on limited direct evidence.