

AI Interconnect Sub-Layer: NVT, CRDO, and APH Emerge as Runway Names
Prompt v1.0
With optical peers AAOI and LITE already blown off 200–300% in 90 days, the actionable gradual-uptrend stories in the AI server/interconnect sub-layer are narrowing to three: NVT (power/cooling infrastructure, 48% 90-day move with 6–18% PT upside still intact), CRDO (PCIe/AEC retimer franchise, 53% 90-day move with ~10% PT upside and DustPhotonics optical optionality), and APH (connector compounder, -11% 90-day pullback against record fundamentals, ~32% upside to median PT). DELL is confirmed blown-off (+115% in 90 days), SMCI remains structurally impaired, and ALAB is high-quality but re-rated.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
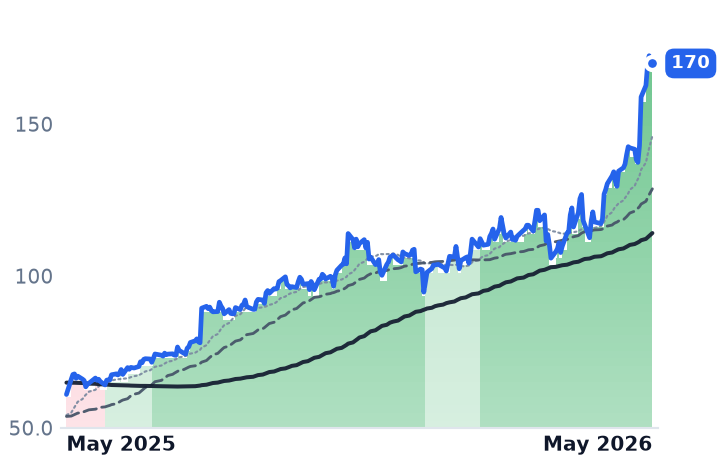
NVT | nVent Electric | Data Center Power & Thermal | 🟢 Cont. Bull | +32.3% | +178.6% |
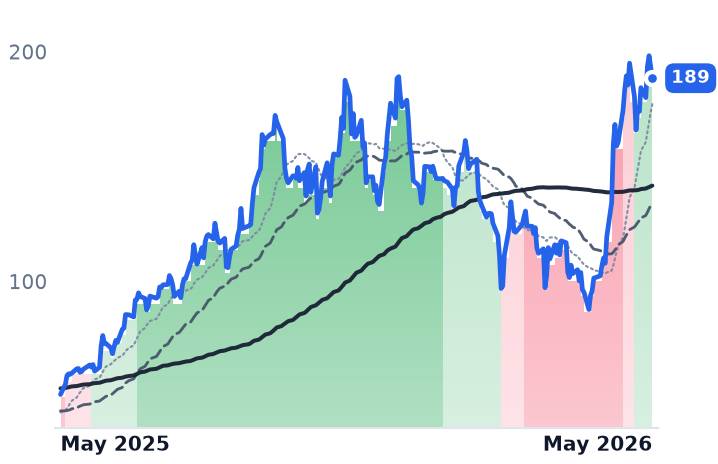
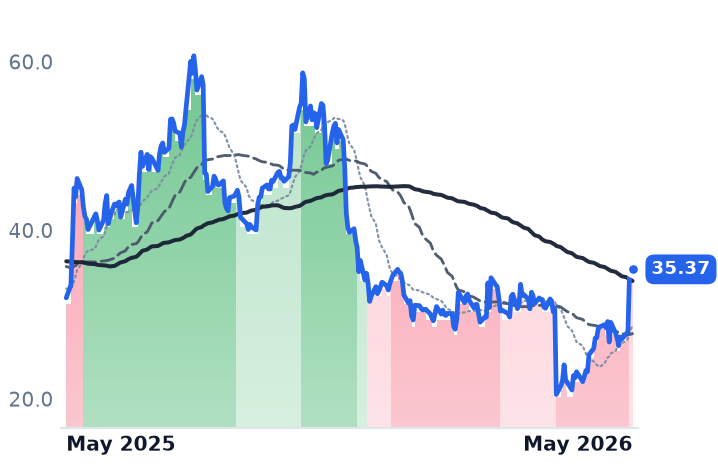
CRDO | Credo Technology | Optical Transport & Switching | ⚠️ Emerging Bear | +74.7% | +271.1% |
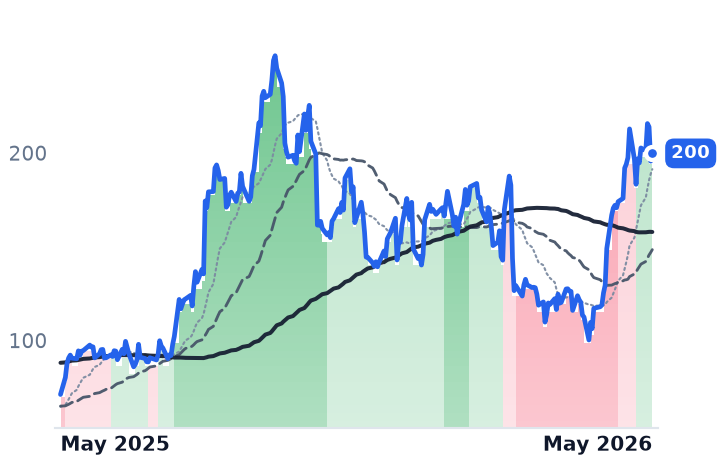
ALAB | Astera Labs | Specialty Semiconductors | ⚠️ Emerging Bear | +54.3% | +180.6% |
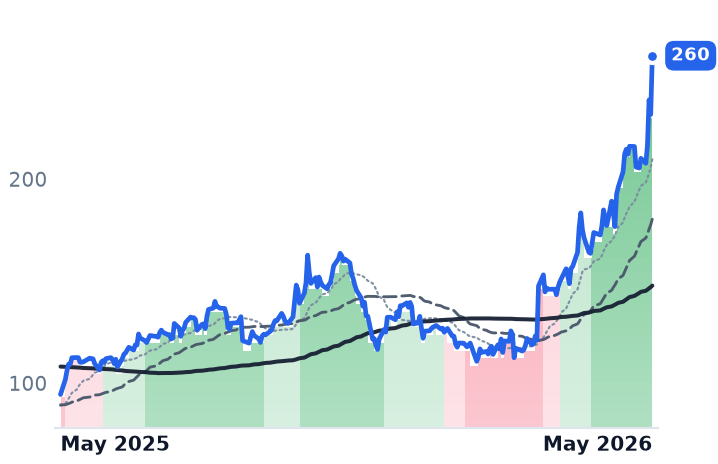
DELL | Dell Technologies | Enterprise Storage & Software | 🟢 Cont. Bull | +44.0% | +175.7% |
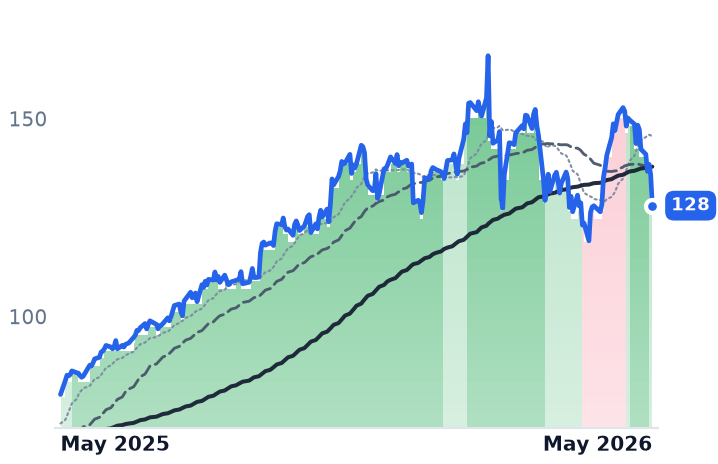
APH | Amphenol | Connectors & Interconnect Systems | 🟢 Cont. Bull | −7.0% | +59.4% |
SMCI | Super Micro Computer | Server & Infrastructure Systems | ⚠️ Emerging Bear | +52.3% | +10.6% |
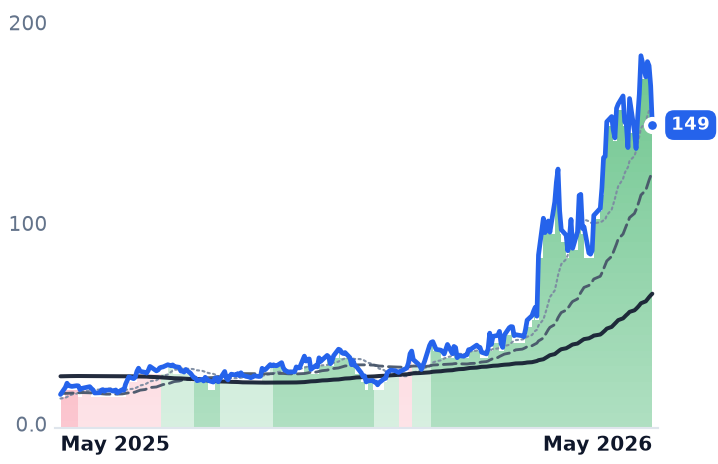
AAOI | Applied Optoelectronics | RF & Wireless | 🟢 Cont. Bull | +11.7% | +915.3% |
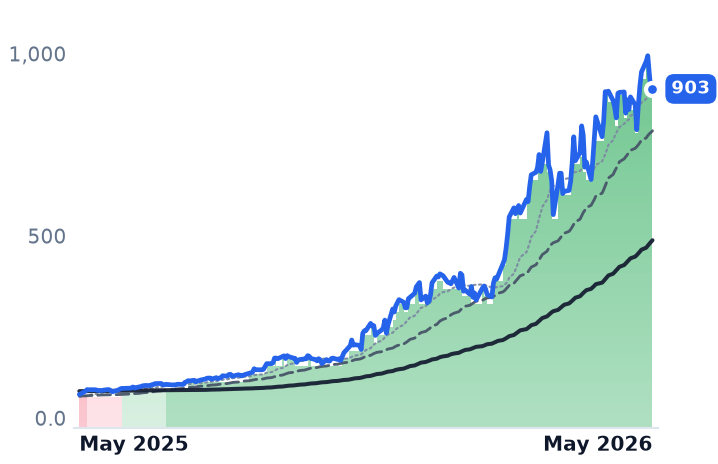
LITE | Lumentum | Optical Transport & Switching | 🟢 Cont. Bull | +1.0% | +1292.7% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NVT | $27.3B | 55.8x | 37.0x | 6.3x | 5.5x | 17.1x | 14.9x | 31.3x | 1.4% |
CRDO | $52.7B | 107.9x | 46.2x | 39.5x | 21.6x | 58.1x | 31.8x | 101.1x | 0.8% |
ALAB | $54.9B | 147.5x | 81.4x | 45.7x | 29.5x | 60.8x | 39.3x | 164.0x | 0.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DELL | $311.3B | 36.6x | 25.4x | 2.3x | 1.8x | 12.2x | 9.5x | 22.4x | 3.0% |
APH | $206.0B | 39.8x | 31.7x | 7.1x | 5.8x | 18.4x | 15.2x | 23.5x | 2.3% |
SMCI | $25.8B | 10.9x | 12.3x | 0.7x | 0.5x | 6.1x | 4.5x | 8.2x | -27.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AAOI | $12.4B | n/m | 149.9x | 20.9x | 11.9x | 72.1x | 41.3x | n/m | -3.3% |
LITE | $75.4B | n/m | 52.1x | 25.0x | 13.3x | 60.0x | 31.9x | n/m | 0.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NVT | Revenue | +29.7% | +14.7% | +13.2% |
| EPS | +36.9% | +22.2% | +16.5% | |
CRDO | Revenue | +211.9% | +83.3% | +49.4% |
| EPS | +423.2% | +85.0% | +47.8% | |
ALAB | Revenue | +123.4% | +59.4% | +26.8% |
| EPS | +121.0% | +61.4% | +25.0% | |
DELL | Revenue | +16.2% | +53.6% | +14.2% |
| EPS | +27.3% | +85.4% | +21.0% | |
APH | Revenue | +54.2% | +17.7% | +12.2% |
| EPS | +59.4% | +22.0% | +13.0% | |
SMCI | Revenue | +77.7% | +34.0% | +19.7% |
| EPS | +33.5% | +15.5% | +13.7% | |
AAOI | Revenue | +129.8% | +169.3% | +48.7% |
| EPS | −417.3% | +454.2% | +102.6% | |
LITE | Revenue | +83.9% | +89.0% | +54.6% |
| EPS | +314.0% | +125.9% | +58.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What's Happening
The AI server/interconnect investment landscape has bifurcated sharply over the past 90 days. Optical leaders have already captured their largest moves — AAOI surged from ~$48 to ~$149 (+211%) and LITE from ~$577 to ~$904 (+57%) over the same window, leaving little "gradual uptrend" thesis remaining. Meanwhile, several power-delivery, connector, and retimer names have been moving in a more measured cadence — or pulling back outright — even as their fundamental underpinnings accelerate.
NVT: The Clearest Gradual Follower
nVent Electric posted a historically strong Q1 2026: record sales of $1.242B (+53% YoY, +34% organic), adjusted EPS of $1.09 versus $0.64 consensus — a 70% beat — and a backlog that tripled year-over-year to $2.6B. The company raised full-year 2026 EPS guidance to $4.45–$4.55 on $4.9–$5.0B revenue. Data center infrastructure (liquid cooling, enclosures, power management) now represents over 55% of total sales, up from 12% at spin-off, with that segment growing 80%+ organically in Q1.
The price response has been sustained but not parabolic: NVT moved from $114.62 to $169.95 over 90 days (+48.3%), including a 30-day surge of +32.1% following earnings. After the blowout Q1 report, at least six Wall Street firms raised price targets, with RBC lifting to $180, UBS to $200, and Roth Capital to $185, all citing AI data center demand and backlog momentum. At ~$170, consensus post-earnings PT range of $180–$200 implies 6–18% further upside. Forward P/E of ~37x is premium but grounded in 21–23% organic growth guidance — well below the multiples commanded by optical blowoff peers.
CRDO: Parabolic but Thesis Intact
Credo Technology has delivered the group's strongest 90-day move (+53%, from $123 to $188), yet the fundamental thesis continues to expand rather than exhaust. Q3 FY26 revenue came in at $407M (+201% YoY) with non-GAAP gross margins of 68.5%, and Q4 guidance of $335–$345M implies the company remains on track for >170% full-year FY26 growth exceeding $1.3B.
On the product side, Credo's Toucan PCIe retimer achieved PCI-SIG compliance at 32.0 GT/s for PCIe 6.0 in February 2026, and the Blue Heron 224G AI scale-up retimer launched targeting UALink, ESUN, and Ethernet protocols on a 3nm process. The company confirmed PCIe Gen 5 and Gen 6 retimer design wins across five hyperscaler AEC customers, each representing >10% of revenue. The PCIe retimer market is projected to reach $2.8B by 2033 at an 11.5% CAGR, while CRDO's scale-up networking TAM could top $40B by 2030.
The $750M DustPhotonics acquisition adds silicon photonics PIC capability in-house, with optical revenues expected to exceed $500M in fiscal 2027; Needham maintained its Buy/$220 PT post-announcement. Consensus PT of ~$208 implies ~10% further upside from current $188 — modest, but the DustPhotonics optionality is not yet in most models.
APH: Pulled Back, Fundamentals Unbroken
Amphenol is the outlier in this set: the stock has declined 11.2% over 90 days (from $144 to $128) even as its fundamental metrics hit records. Q1 2026 saw sales of $7.62B (+58% YoY, +33% organic), adjusted EPS of $1.06 (+68% YoY), and a book-to-bill of 1.24x — indicating orders outpacing shipments. IT datacom (primarily AI-driven) accounted for 41% of revenue, up 99% YoY.
The January 2026 acquisition of CommScope's CCS business for ~$14.8B materially expanded APH's fiber optic interconnect and data center penetration; CCS is expected to contribute $4.1B in FY2026 sales and $0.15 EPS accretion. 23 Wall Street analysts cover APH with a median price target of $169 (range $135–$210), with an overall Strong Buy consensus, implying ~32% upside from $128 — well above the 15% hurdle set in the hypothesis screen.
Exclusions and Why
DELL is a confirmed blown-off name: the stock surged from $121 to $260 (+115%) over 90 days. Goldman Sachs raised its Dell price target to $215 with a Buy rating in April 2026, but at $260, the stock has already blown through most targets. Dell's Q4 FY26 AI server revenue surged 342% YoY, and the CFO confirmed the pipeline 'has never been higher', but the upside cadence is no longer "gradual."
SMCI remains structurally impaired. The stock is up only 5.5% over 90 days, but that masks a trough of $23.22 in late March before a partial recovery. Gross margins collapsed to 6.4% in Q2 FY26 (vs. historical 14–17% targets), and FY26 full-year guidance remains single-digit. SMCI also faces a federal export-control overhang following U.S. charges for allegedly smuggling AI technology to China, adding legal risk to an already-compressed margin structure.
ALAB is high-quality but recently re-rated: Astera Labs reported Q1 2026 revenue of $308M (+93% YoY) with Q2 guidance of $355–$365M, but the stock's 90-day path (peak $188 → trough $100 → back to $200) reflects a sharp post-earnings re-rating rather than gradual accumulation. Forward P/E of ~67x and P/S of ~22x leave limited cushion if execution falters.
Bottom Line
NVT, CRDO, and APH are the three names in the AI server/interconnect sub-layer where the combination of confirmed hyperscaler/platform catalysts, sustained (not single-day) price moves, and intact sell-side PT upside remains most coherent. NVT is the cleanest gradual-uptrend story with the largest backlog acceleration; CRDO has the strongest revenue growth momentum and optical expansion optionality; APH offers the most PT upside from a position of fundamental strength and post-acquisition scope.